

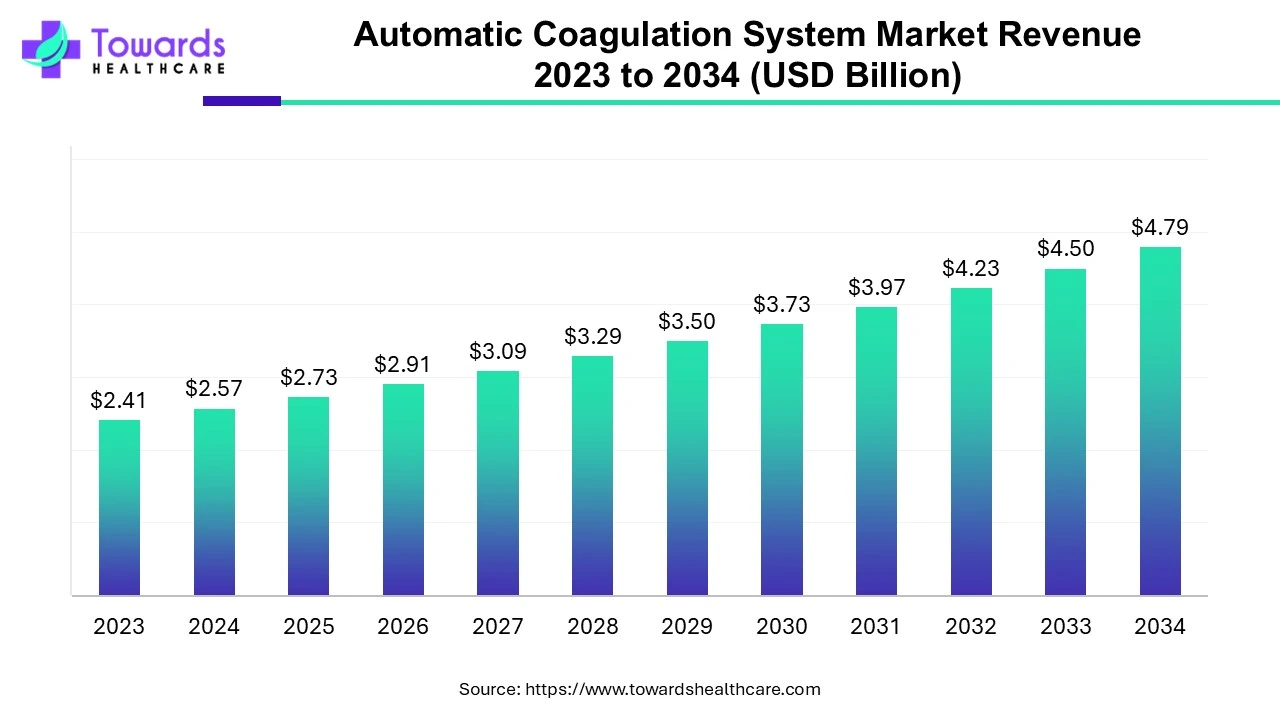
The automatic coagulation system market was estimated at US$ 2.73 billion in 2025 and is projected to grow to US$ 4.79 billion by 2034, rising at a compound annual growth rate (CAGR) of 6.44% from 2025 to 2034. The increasing incidences of chronic disorders, technological advancements, and growing research and development drive the market.
Automatic coagulation systems are equipment used to measure the levels of blood coagulation factors. They are either semi- or fully-automatic multi-parameter hemostasis analyzers used to perform coagulation tests, and chromogenic and immunologic assays. Various parameters such as fibrinogen levels, platelet count, clot retraction, clotting time, prothrombin time, thrombin time, etc. can be measured using automated coagulation systems. There may be different types of coagulation systems: benchtop analyzers, required to be placed on a laboratory bench, and portable analyzers, for carrying out tests at the bedside.
The rising incidences of hematological disorders like hemophilia, liver disease, and nutrient malabsorption promote the use of automatic coagulation systems. They are also used to monitor patients who are at high risk of bleeding before and after surgery. The increasing demand for point-of-care (PoC) diagnostics and growing research and development augment market growth.
An automated coagulation system does not require any skilled professional during the analysis or working of the instrument. Advanced research has an inclination towards point-of-care (PoC) testing, primarily focused on improved systems miniaturization and functional integration. The demand for PoC coagulation technologies increases due to central laboratories’ inability to deliver data quickly enough to enable anticoagulant medication to be started and administered on time.
PoC testing involves analyzing blood coagulation at the patient’s bedside, i.e. in the emergency department, operating rooms, clinics, and ICUs. The three different methods for PoC include simple anticoagulation monitoring devices, PoC coagulation tests available to assess primary hemostasis and platelet function, and viscoelastic coagulation monitoring devices. Hence, PoC coagulation testing is faster and more comprehensive than traditional laboratory tests and enables effective and economical management.
Automated coagulation systems are diagnostic instruments that automatically measure blood-clotting parameters to assess coagulation function and support the diagnosis and monitoring of bleeding and thrombotic disorders. The market is growing as healthcare facilitites increasingly prioritize rapid, standardized, and efficient laboratory testing. A major trend is the shift from manual coagulation testing toward automated platforms that improve workflow efficient and reduce operator-dependent variability. Technological advancements include optical and mechanical clot detection, integrated sample handling, barcode identification, and digital connectivity. Future opportunities are emerging from the expansion of decentralized anticoagulant management and advanced hemostasis testing. Rising surgical volumes, increasing use of anticoagulant therapies, growing diagnostic laboratory networks, and demand for early disease detection are supporting adoption. Integration with laboratory information systems and automation-enabled data management is further strengthening market development.
The major challenge of the market is the high cost of the equipment, resulting in less affordability for several small and medium enterprises. The cost of an automated coagulation system usually ranges from a thousand euros to several tens of thousands of euros. Apart from the equipment, the cost of reagents, maintenance, and other supplies contribute to overall expense, limiting adoption. Another major challenge of the market is the increased risk of downtime. Lack of regular calibration and maintenance leads to critical system failures and inaccurate results, impacting workflow efficiency.
North America held the largest share of the automatic coagulation system market in 2025. The presence of key players, increasing investments & collaborations, advanced healthcare infrastructure, rising incidences of hematological disorders, and favorable government policies drive the market. The automated coagulation systems are regulated by government agencies like the US Food and Drug Administration and Health Canada. The presence of key players in the US constitutes a major share of the market.
The increasing incidences of hemophilia and other hematological disorders potentiate the demand for automatic coagulation systems for early diagnosis. According to the Centers for Disease Control and Prevention, around 33,000 males in the US are estimated to be living with hemophilia. While in Canada, about 3,900 people are affected by hemophilia A, and 800 people are affected by hemophilia B.
U.S. Advances Through Strong Diagnostic Infrastructure
The U.S. automated coagulation systems market is growing significantly due to advanced healthcare infrastructure, high adoption of automated laboratory technologies, and increasing demand for efficient diagnostic testing. Rising surgical procedures, growing use of anticoagulant therapies, and the presence of well-equipped clinical laboratories are supporting adoption. Continuous technological innovation and integration with digital laboratory systems further strengthen market expansion across hospitals and diagnostic centers.
Canada Expands Through Modern Laboratory Automation
Canada’s automated coagulation systems market is notably growing due to expanding healthcare infrastructure, increasing adoption of automated diagnostic technologies, and rising demand for efficient blood-clotting assessments. Growing awareness of coagulation disorders, increasing surgical procedures, and investments in laboratory modernization are supporting market development. Integration of advanced analyzers with digital healthcare systems and the need for standardized testing are further creating opportunities across hospitals and diagnostic laboratories.
Asia-Pacific is expected to grow at the fastest rate in the automatic coagulation system market during the forecast period. The rising incidences of blood disorders, increasing number of surgeries, growing research and development, and increasing demand for PoC testing drive the market. Patients with a high risk of bleeding are assessed before and after surgery. Hence, the increasing number of surgeries in the region increases the demand for automatic coagulation systems.
In 2023, around 1,735 surgeries per 100,000 population underwent surgery in Hong Kong, China. In 2022, Korea reported around 3,235 surgeries per 100,000 population surgeries. In India, it is estimated that approximately 30 million surgeries are performed annually. Additionally, the surge in COVID-19 cases in the region increases the demand for coagulation parameters like D-dimer and prothrombin time. Furthermore, the growing healthcare and biotech sector and rising adoption of advanced diagnostics boost the market.
China Strengthens Its Position Through Expanding Healthcare Infrastructure
China has a notable market share in automated coagulation systems due to its expanding healthcare infrastructure, growing diagnostic laboratory networks, and increasing adoption of automated testing technologies. Rising awareness of coagulation disorders, growing surgical volumes, and investments in modern clinical laboratories are supporting demand. Advancements in automation, improved testing capabilities, and increasing healthcare expenditure further contribute to the country’s market position.
India Expands Through Growing Diagnostic Demand
India’s automated coagulation systems market is significantly expanding due to increasing healthcare investments, growing diagnostic laboratory networks, and rising adoption of automated testing technologies. Higher demand for efficient blood-clotting assessment, increasing surgical procedures, and greater awareness of coagulation disorders are supporting market development. Modernization of hospitals and laboratories, along with improving access to advanced diagnostic equipment, is further creating growth opportunities.
By type, the fully automatic segment is anticipated to gain traction in the automatic coagulation system market in the upcoming years. A fully automated coagulation system operates autonomously without requiring a trained professional. Hence, organizations with a lack of skilled personnel can incorporate an automated system. It offers numerous benefits including reducing the risks of manual errors, streamlining lab operations, enhancing workflow, and minimizing turnaround time.
By application, the hospital segment dominated the automatic coagulation system market in 2025. The segmental growth is attributed to the increasing number of patients in hospitals, the increasing number of surgeries, and favorable infrastructure. In addition, the growing demand for PoC coagulation testing potentiates the segment’s growth.
The biotechnology company segment is predicted to grow with the highest CAGR in the automatic coagulation system market during the studied years. The growing biotech R&D activities and increasing investments favor the segment’s growth. An automated coagulation system aids in effective hemostasis testing and diagnosing causes of hemorrhages, potentiating the development of novel anti-coagulant therapies.
By Type
By Application
By Region

Principal Consultant
Payal Rabde is a Healthcare Market Research Analyst at Towards Healthcare Research & Consulting with 4+ years of experience in pharmaceuticals, biotechnology, medical devices, and life sciences.
Learn more about Payal Rabde
Reviewed By
Aditi Shivarkar is a seasoned professional with over 14 years of experience in healthcare market research. As a content reviewer, Aditi ensures the quality and accuracy of all market insights and data presented by the research team.
Learn more about Aditi Shivarkar