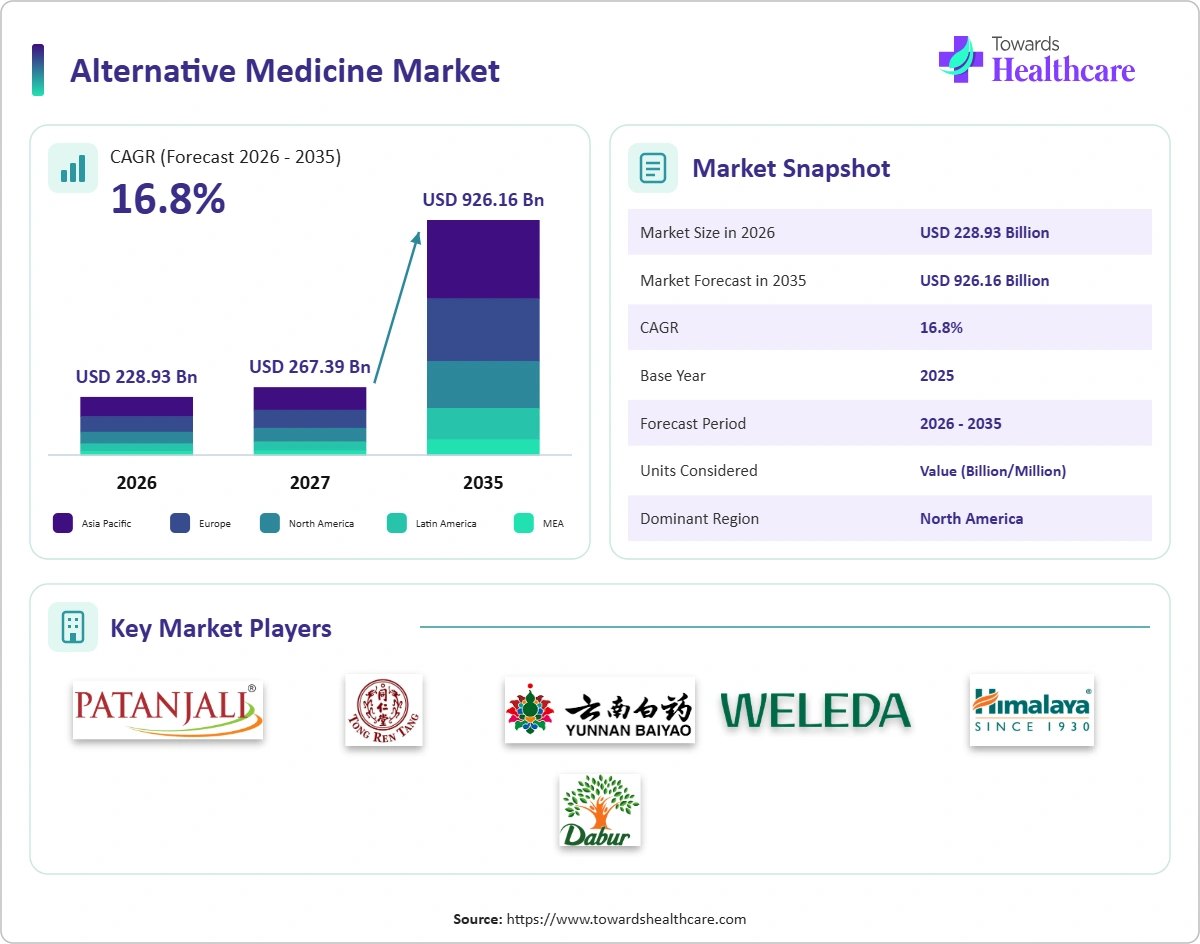
The market is projected to grow from USD 196.00 billion in 2025 to USD 926.16 billion by 2035 because many people across the globe use traditional and complementary therapies, and governments and the WHO are making significant efforts to integrate them into health systems. A strong market growth is being supported by natural health preferences, chronic disease, government support, and digital access. The market is expected to reach USD 426.06 billion by 2030 and sustain a CAGR of 16.80% during the forecast period. Alternative medicine overlaps with probiotics, telehealth, and cosmeceuticals.
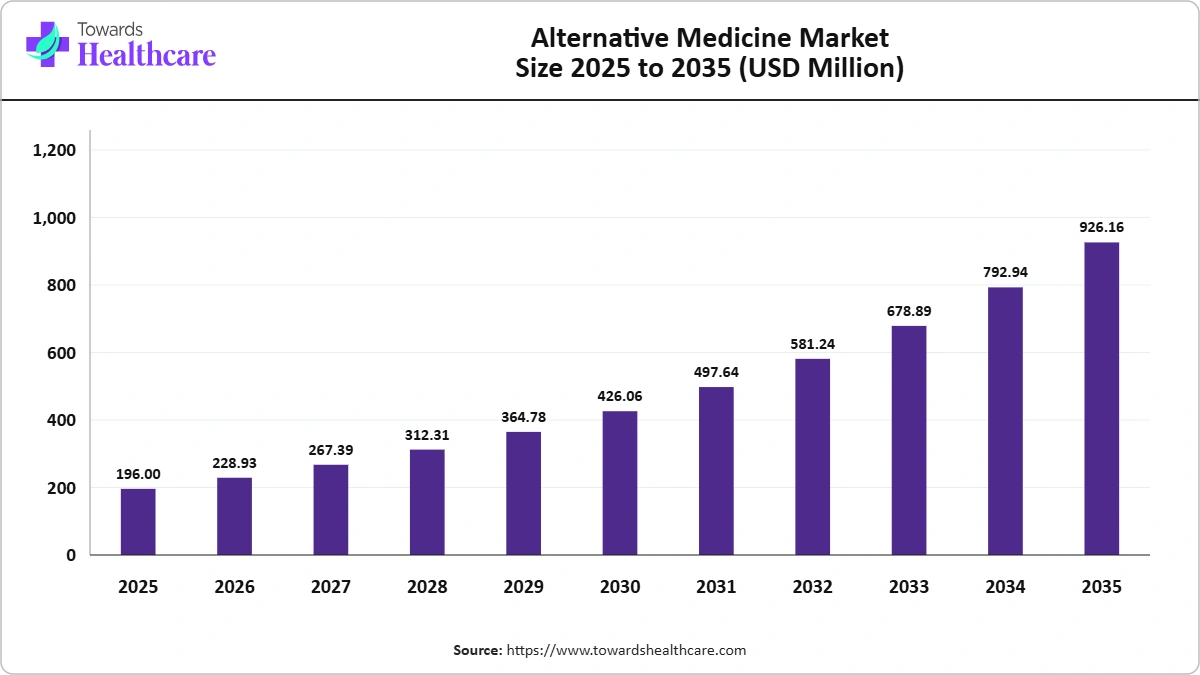
Analyst View: We built the estimate from spending on traditional and complementary products and services by intervention and region, cross-checked against national health data and company revenues. Our value sits just above published comparable estimates.
| Driver | Impact | ≈ CAGR Contribution | Time Horizon | Key Regions |
| Consumers seek natural options | High | +6.56 pp | Short to long term | Global, strongest in Asia Pacific |
| Chronic disease and stress | Medium | +5.53 pp | Medium to long term | Global, fastest uptake in Asia Pacific |
| Government support in Asia | Medium | +4.71 pp | Short to medium term | Global |
| WHO strategy | Low | +3.69 pp | Long term | Developed and emerging markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
These drivers together add about 20.50 percentage points to the annual growth of the market, with consumers seeking natural options having the largest influence. Their effect is strongest in Asia Pacific, while uptake grows at the highest rate in Asia Pacific.
| Restraint | Impact | ≈ Negative CAGR Contribution | Time Horizon | Key Regions |
| Limited clinical evidence | High | -1.66 pp | Short to medium term | Global |
| Safety and quality concerns | High | -1.22 pp | Medium term | Price-sensitive and emerging markets |
| Regulatory differences | Medium | -0.81 pp | Short term | Asia Pacific and other mature markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
These restraints are expected to decrease the annual growth rate of the market by about 3.70 percentage points, with the largest contributor being limited clinical evidence. Their effect decreases over the forecast period as suppliers, buyers, and regulators adapt, leaving a net CAGR of 16.80% from 2026 to 2035.
Integrative healthcare, digital mind-body services, and standardized herbal products are being rapidly adopted, which creates new opportunities in the market. Expansion of wellness tourism and increased research investments are benefiting the market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
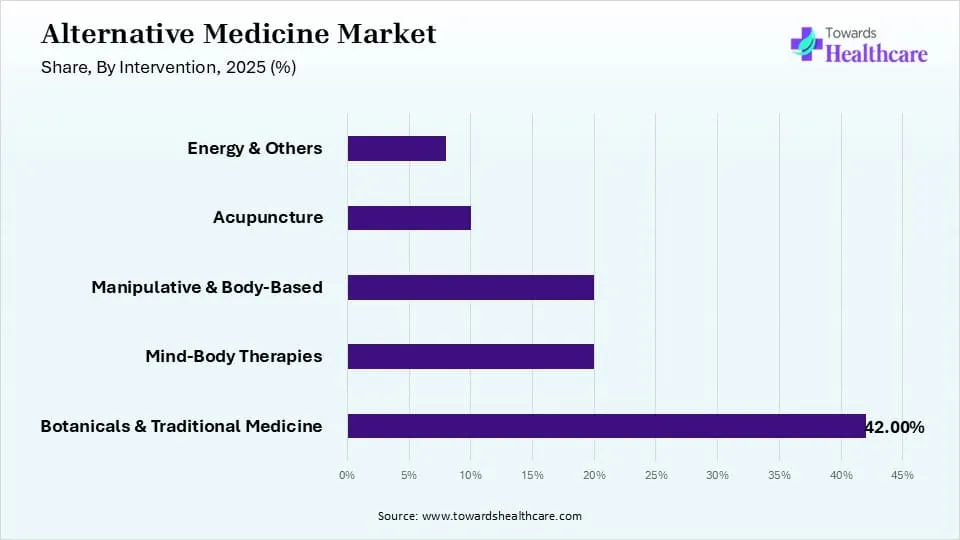
Botanicals & Traditional Medicine accounted for 42.00% of revenue in 2025 and is projected to expand at a CAGR of 16.14% from 2026 to 2035. This segment has secured the leading position because herbal remedies, Ayurveda, and TCM have been widely adopted. This segment is expected to grow at a slower rate than the overall market over the forecast period.
Mind-Body Therapies such as yoga and meditation grow fastest. This segment is expected to grow at a faster rate than the market from 2026 to 2035.
Manipulative & Body-Based therapies include chiropractic and massage. The manipulative & body-based segment is expected to grow broadly in line with the overall market over the forecast period.
Acupuncture is used for pain. The growth of this segment is expected to stay aligned with the market between 2026 and 2035.
Energy & Others interest in diverse alternative treatment modalities is increasing, which supports the demand for this segment. The growth of this segment is expected to stay aligned with the market over the forecast period.
Segment Outlook: Botanicals & Traditional Medicine continue to hold the largest share in the intervention category through 2035, holding about 39.67% of the market in 2035, while Mind-Body Therapies records the highest CAGR of 18.54% from 2026 to 2035. Energy & Others holds the smallest share today and serves more specialized needs within the market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Direct Contact accounted for 62.00% of the market in 2025 and is projected to expand at a CAGR of 16.04% from 2026 to 2035. Direct contact leads because most therapies need practitioners. This segment is expected to grow at a slower rate than the overall market over the forecast period.
E-Training & Online is growing at the fastest rate owing to the expansion of apps and the virtual classes ecosystem. This segment is expected to grow faster than the market between 2026 and 2035.
Distance Correspondence completes demand. The distance correspondence segment is expected to grow slower than the overall market over the forecast period.
Segment Outlook: Direct Contact is expected to be the largest distribution segment through 2035, as it is projected to account for 58.10% of the market in 2035, while E-Training & Online is expected to grow at the highest CAGR of 18.44% during the forecast period. Currently, Distance Correspondence holds the smallest share and serves more specialized needs within the market.
Analyst View: Segment shares were allocated from demand, product portfolios, and pricing in each category. Botanicals & Traditional Medicine and Direct Contact are leaders in their respective categories because they meet the core needs of today's buyers. We expect Mind-Body Therapies and E-Training & Online to gain share as newer technologies, users, and applications grow faster.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
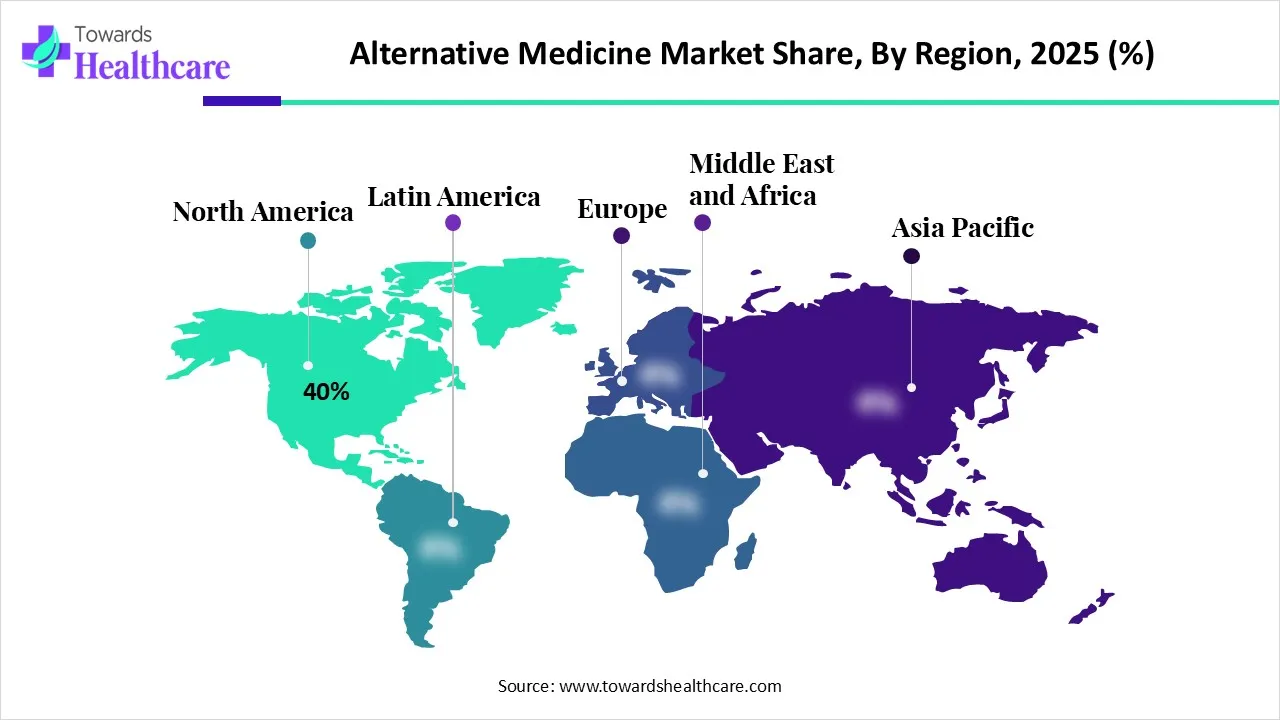
Asia Pacific accounted for 40.00% of the market in 2025 and is projected to expand at a CAGR of 17.51% from 2026 to 2035. Asia Pacific leads and grows fastest because traditional medicine is part of care in China and India. Asia Pacific is expected to grow faster than the overall market over the forecast period.
Europe has a mature homeopathy and herbal medicine ecosystem and spa traditions. The growth rate of this region is expected to be lower than the overall market from 2026 to 2035.
North America has high spending on chiropractic, supplements and wellness. North America is expected to grow at a slower rate than the overall market throughout the forecast period.
Latin America region benefits from widespread adoption of traditional herbal medicines. The growth rate of this region is expected to be lower than that of the market between 2026 and 2035.
Middle East & Africa is significant usage of traditional medicines in this region. Middle East & Africa is expected to grow at a lower pace than the overall market throughout the forecast period.
Analyst View: Regional shares were built from demand, installed base, spending, and supplier presence in each region. Asia Pacific leads because of its mature demand base and strong suppliers. We assign Asia Pacific the highest growth premium because investment, adoption, and capacity are expanding fastest there.
| Rank | Company Name | 2025 Share (%) | Key Products / Business | Headquarters |
| 1 | Patanjali Ayurved | 3.00% | Ayurvedic products | India |
| 2 | Tong Ren Tang | 3.00% | Traditional Chinese medicine | China |
| 3 | Dabur | 2.00% | Ayurvedic and herbal medicines | India |
| 4 | Yunnan Baiyao | 2.00% | TCM products | China |
| 5 | Tsumura | 1.00% | Kampo medicines | Japan |
| 6 | Himalaya Wellness | 1.00% | Herbal products | India |
| 7 | Weleda | 1.00% | Anthroposophic and natural products | Switzerland |
| 8 | Boiron | 1.00% | Homeopathic medicines | France |
| 9 | Nature's Sunshine | 1.00% | Herbal supplements | United States |
| 10 | The Joint Corp. | 1.00% | Chiropractic clinics | United States |
Note: Company shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources,Towards Healthcare database, and Towards Healthcare analysts.
Patanjali Ayurved led the market with a 3.00% share in 2025, followed by Tong Ren Tang at 3.00% share and Dabur at 2.00% share.
Patanjali Ayurved is the leader owing to its Ayurvedic products, Tong Ren Tang stays competitive with traditional Chinese medicine, and Dabur offers Ayurvedic and herbal medicines. Yunnan Baiyao, Tsumura, Himalaya Wellness, Weleda, Boiron, Nature's Sunshine and The Joint Corp. compete through TCM products, kampo medicines, herbal products, anthroposophic and natural products, homeopathic medicines, herbal supplements and chiropractic clinics.
The top 10 companies accounted for 16.00% of revenue in 2025, while the remaining 84.00% was shared among millions of independent practitioners, clinics and small brands. This market is highly fragmented, and competition centers on practitioner networks, product quality and standardization, evidence, regulation, brand trust, and price.
Patanjali Ayurved is headquartered in India. The company captured 3.00% of the market in 2025. Its offerings centre on Ayurvedic products. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Tong Ren Tang, part of China Beijing Tong Ren Tang Group Co., Ltd., is headquartered in China. It held a market share of 3.00% in 2025. Its offering revolves around Traditional Chinese medicine. It has been positioned as a Leader in the Towards Healthcare Companies Quadrant.
Dabur has its global headquarters in India. It accounted for 2.00% of revenue in 2025. Dabur’s portfolio comprises Ayurvedic and herbal medicines. In the Towards Healthcare Companies Quadrant, it is positioned as a Leader.
Yunnan Baiyao has its corporate headquarters in China. The company held a 2.00% share in 2025. Its offering centres on TCM products. It has been awarded the status of a Leader in the Towards Healthcare Companies Quadrant.
The headquarters of Tsumura is in Japan. It captured 1.00% of net market revenue in 2025. Its offering revolves around Kampo medicines. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Himalaya Wellness is headquartered in India. It accounted for 1.00% of the market in 2025. It provides Herbal products. Himalaya Wellness has been positioned as a Leader in the Towards Healthcare Companies Quadrant.
Weleda has its global headquarters in Switzerland. It held a 1.00% share in 2025. Its offering centres on Anthroposophic and natural products. In the Towards Healthcare Companies Quadrant, it is positioned as an Innovator.
The corporate headquarters of Boiron is in France. The company captured 1.00% of the market in 2025. Its offering revolves around Homeopathic medicines. In the Towards Healthcare Companies Quadrant, it is positioned as an Innovator.
Nature's Sunshine is headquartered in the United States. It accounted for 1.00% of revenue in 2025. Its offering centres on Herbal supplements. The company has been awarded the status of an Innovator in the Towards Healthcare Companies Quadrant.
The Joint Corp. has its corporate headquarters in the United States. It held a 1.00% share in 2025. Its offering centres on Chiropractic clinics. It is positioned as an Innovator in the Towards Healthcare Companies Quadrant.
The alternative medicine ecosystem links raw material growers, product manufacturers, practitioners & clinics, retail & online, and regulators, and each stage adds value before products reach end users.
| Ecosystem Stage | Role in the Market | Key Companies |
| Raw Material Growers | Grow herbs and botanicals | Farmers and collectors |
| Product Makers | Make remedies | Patanjali, Tong Ren Tang, Dabur, Tsumura |
| Practitioners & Clinics | Deliver therapies | Ayurveda, TCM, chiropractic, yoga providers |
| Retail & Online | Sell products and classes | Pharmacies, e-commerce, apps |
| Regulators | Set rules | WHO, AYUSH ministry, NMPA, FDA |
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Raw Material Growers: Grow herbs and botanicals. Key participants include Farmers and collectors.
Product Makers: Make remedies. Key participants include Patanjali, Tong Ren Tang, Dabur, and Tsumura.
Practitioners & Clinics: Deliver therapies. Key participants include Ayurveda, TCM, chiropractic, and yoga providers.
Retail & Online: Sell products and classes. Key participants include Pharmacies, e-commerce, and apps.
Regulators: Set rules. Key participants include WHO, AYUSH ministry, NMPA, FDA.
Value in the market flows from upstream material and technology suppliers to manufacturers and service providers, then through distribution partners to end users. Companies that integrate several stages or build long-term relationships with end users capture a larger share of this value.
The Towards Healthcare Companies Quadrant positions key participants in the alternative medicine market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 share of the alternative medicine market and our assessment of its product innovation, portfolio breadth, and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Leaders: Patanjali Ayurved, Tong Ren Tang, Dabur, Yunnan Baiyao, Tsumura and Himalaya Wellness combine high market share with broad portfolios and strong innovation.
Innovators: Weleda, Boiron, Nature's Sunshine and The Joint bring newer technologies and specialized products.
By Intervention
By Distribution
By Region
The market is defined as complementary and alternative medicine products and services, including traditional medicine systems such as Ayurveda and traditional Chinese medicine, botanical and herbal remedies, acupuncture, mind-body therapies such as yoga and meditation, manipulative and body-based therapies such as chiropractic and massage, and energy and other therapies, delivered through direct contact, e-training and online, and distance correspondence channels.
The 2025 base year was built bottom-up from demand volumes and average prices by intervention and distribution and region, and checked top-down against the market-specific revenues of leading companies and published estimates. Segment, regional, and company values were allocated from intervention and distribution and region demand. Key estimates were verified by cross-checking company disclosures, regulatory and industry data, and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional, and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View: The market is well-positioned to grow at a steady rate as natural health preferences and related demand are continuously growing. Our estimate links value to underlying demand, installed base, and pricing, so the forecast follows real adoption rather than headline hype. The market benefits from integrative care and digital services, while the main risks are limited evidence and safety concerns.