The bioinformatics in IVD testing market is projected to grow from USD 2.15 billion in 2025 to USD 7.43 billion by 2035 because every clinical sequencing test needs analysis and interpretation software, and sequencing volumes are rising fast. Clinical sequencing growth, precision oncology, in-house testing, and AI interpretation support very strong growth, lifting the market to USD 4.00 billion by 2030 and sustaining a CAGR of 13.20% from 2026 to 2035. Bioinformatics turns next generation sequencing and genomics data into precision medicine reports.
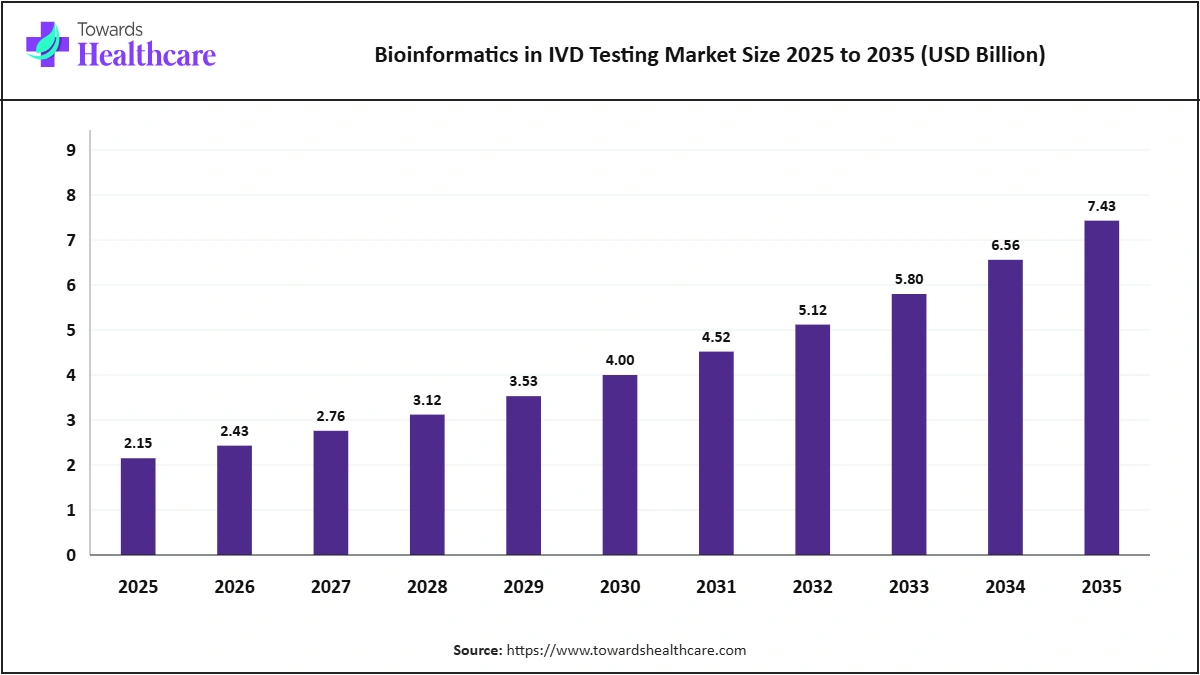
Analyst View: The market estimate was developed using regional clinical sequencing test volumes, software licensing revenues, and service fees, with figures cross-checked against clinical informatics revenues reported by leading suppliers. As published estimates for this specific market scope are limited, the valuation is based on available industry evidence and underlying market data.
| Driver | Impact | ≈ CAGR Contribution | Time Horizon | Key Regions |
| Clinical sequencing grows | High | +5.15 pp | Short to long term | Global, strongest in North America |
| Precision oncology spreads | Medium | +4.35 pp | Medium to long term | Global, fastest uptake in Asia Pacific |
| Data volumes rise | Medium | +3.70 pp | Short to medium term | Global |
| Labs bring testing in-house | Low | +2.90 pp | Long term | Developed and emerging markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Taken together, these drivers add about 16.10 percentage points to the annual growth of the bioinformatics in IVD testing market, with clinical sequencing grows having the largest effect. Their influence is strongest in North America, while uptake grows fastest in Asia Pacific.
| Restraint | Impact | ≈ Negative CAGR Contribution | Time Horizon | Key Regions |
| Regulatory validation | High | -1.31 pp | Short to medium term | Global |
| Data privacy | High | -0.96 pp | Medium term | Price-sensitive and emerging markets |
| Shortage of bioinformaticians | Medium | -0.64 pp | Short term | North America and other mature markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
These restraints are expected to reduce annual growth of the bioinformatics in IVD testing market by about 2.90 percentage points, led by regulatory validation. Their effect eases over the forecast period as suppliers, buyers, and regulators adapt, leaving a net CAGR of 13.20% from 2026 to 2035.
Growth opportunities are emerging in decentralised NGS, AI-driven data curation and the expansion of sequencing services across Asia. Rising demand for pathogen surveillance and multiomic analysis is also creating new avenues for market growth.
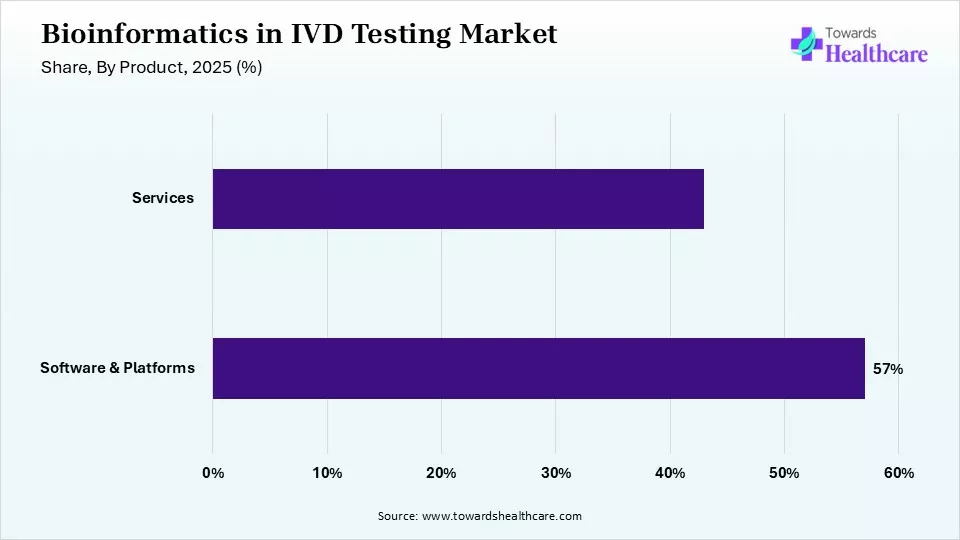
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Software & Platforms: This segment accounted for 57.00% of the bioinformatics in IVD testing market in 2025 and is projected to expand at a CAGR of 12.76% from 2026 to 2035. Software and platforms lead because labs license pipelines and interpretation tools for every sequencing run. The software & platforms segment is expected to grow slower than the overall market over the forecast period.
Services grow faster as labs outsource analysis, validation, and curation. The services segment is expected to grow faster than the overall market over the forecast period.
Although Services starts from the smallest base, its faster growth shows how demand is shifting within the bioinformatics in IVD testing market.
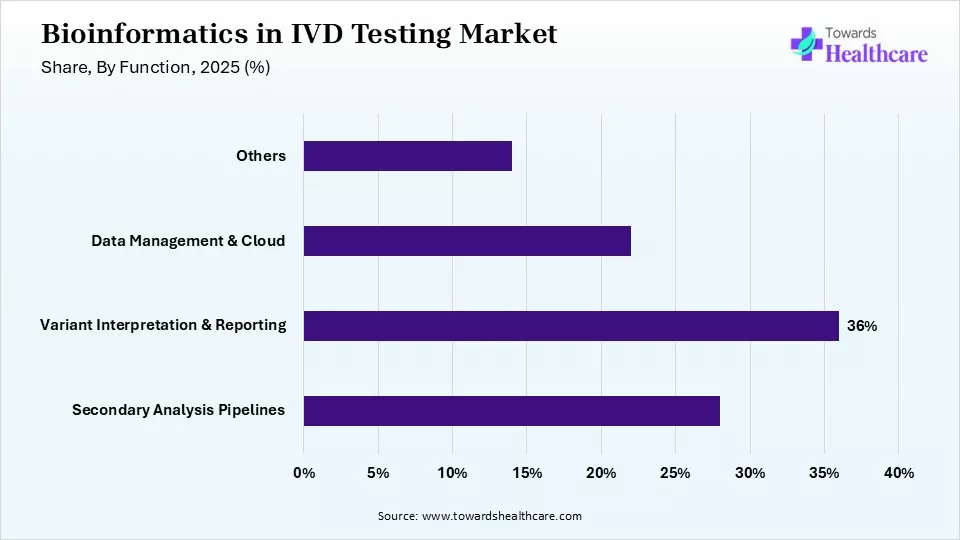
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Secondary Analysis Pipelines: This segment accounted for 28.00% of the bioinformatics in IVD testing market in 2025 and is projected to expand at a CAGR of 12.87% from 2026 to 2035. Secondary analysis pipelines align reads and call variants. The secondary analysis pipelines segment is expected to grow slower than the overall market over the forecast period.
Variant interpretation and reporting lead because clinical reports need curated evidence. The variant interpretation & reporting segment is expected to grow slower than the overall market over the forecast period.
Data management and cloud grow fastest as data volumes rise. The data management & cloud segment is expected to grow faster than the overall market over the forecast period.
Other functions include QC and federated analytics. The other segment is expected to grow slower than the overall market over the forecast period.
Others hold the smallest share today and serve more specialised needs within the bioinformatics in IVD testing market.
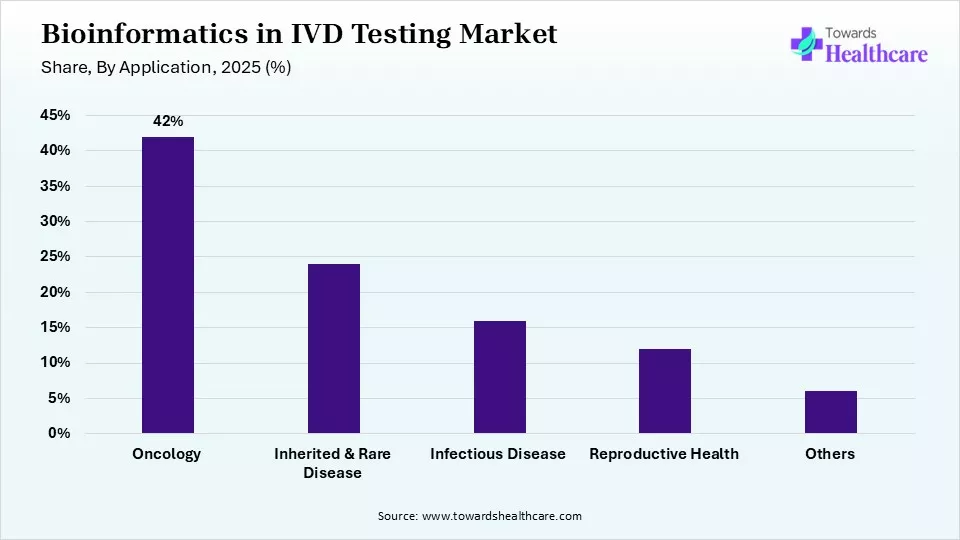
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Oncology: The Oncology segment accounted for the largest share of the bioinformatics in IVD testing market in 2025, at 42.00%, and is projected to grow at a CAGR of 12.71% from 2026 to 2035. Its leading position reflects the complex data analysis required for tumour profiling and liquid biopsy testing. However, the oncology segment is expected to grow at a slower pace than the overall market over the forecast period.
Inherited and rare disease testing uses exome and genome analysis. The inherited & rare disease segment is expected to grow broadly in line with the overall market over the forecast period.
Infectious disease grows fastest with pathogen sequencing and resistance detection. The infectious disease segment is expected to grow faster than the overall market over the forecast period.
Demand is supported by the use of bioinformatics in non-invasive prenatal testing (NIPT) and carrier screening. The segment is expected to grow broadly in line with the overall market over the forecast period.
Others include pharmacogenomics. The others segment is expected to grow broadly in line with the overall market over the forecast period.
Others hold the smallest share today and serve more specialised needs within the bioinformatics in IVD testing market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
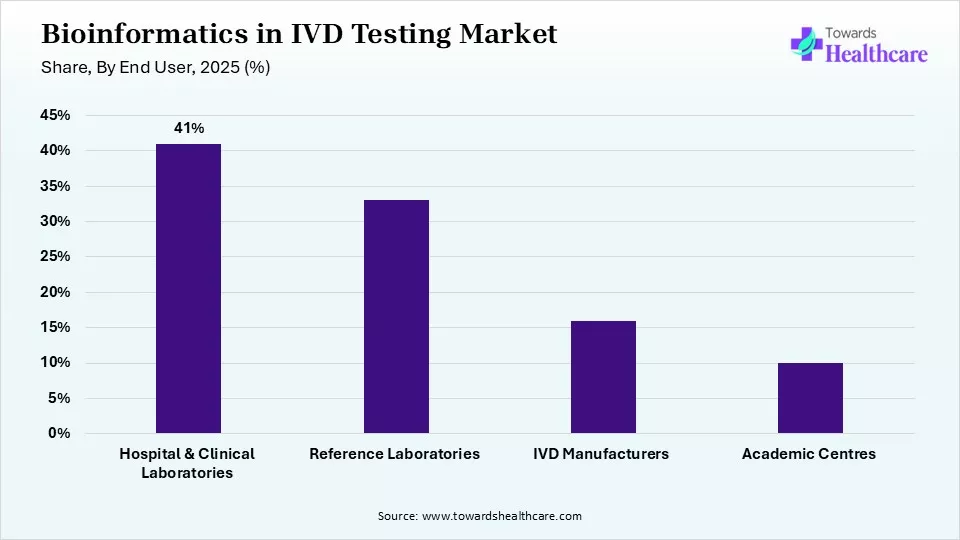
Hospital & Clinical Laboratories: This segment accounted for 41.00% of the bioinformatics in IVD testing market in 2025 and is projected to expand at a CAGR of 13.67% from 2026 to 2035. Hospital and clinical laboratories lead as they bring NGS in-house. The hospital & clinical laboratories segment is expected to grow faster than the overall market over the forecast period.
Its significant market share reflects the high volume of tests processed by reference laboratories. However, the segment is expected to grow at a slower pace than the overall market over the forecast period.
IVD manufacturers embed software in kits. The IVD Manufacturers segment is expected to grow slower than the overall market over the forecast period.
Academic centres develop new methods. The academic centres segment is expected to grow slower than the overall market over the forecast period.
Analyst View: Segment shares were allocated from demand, product portfolios, and pricing in each category. Software & Platforms, Variant Interpretation & Reporting, Oncology and Hospital & Clinical Laboratories lead their categories because they meet the core needs of today's buyers. We expect Services, Data Management & Cloud and Infectious Disease to gain share as newer technologies, users and applications grow faster.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
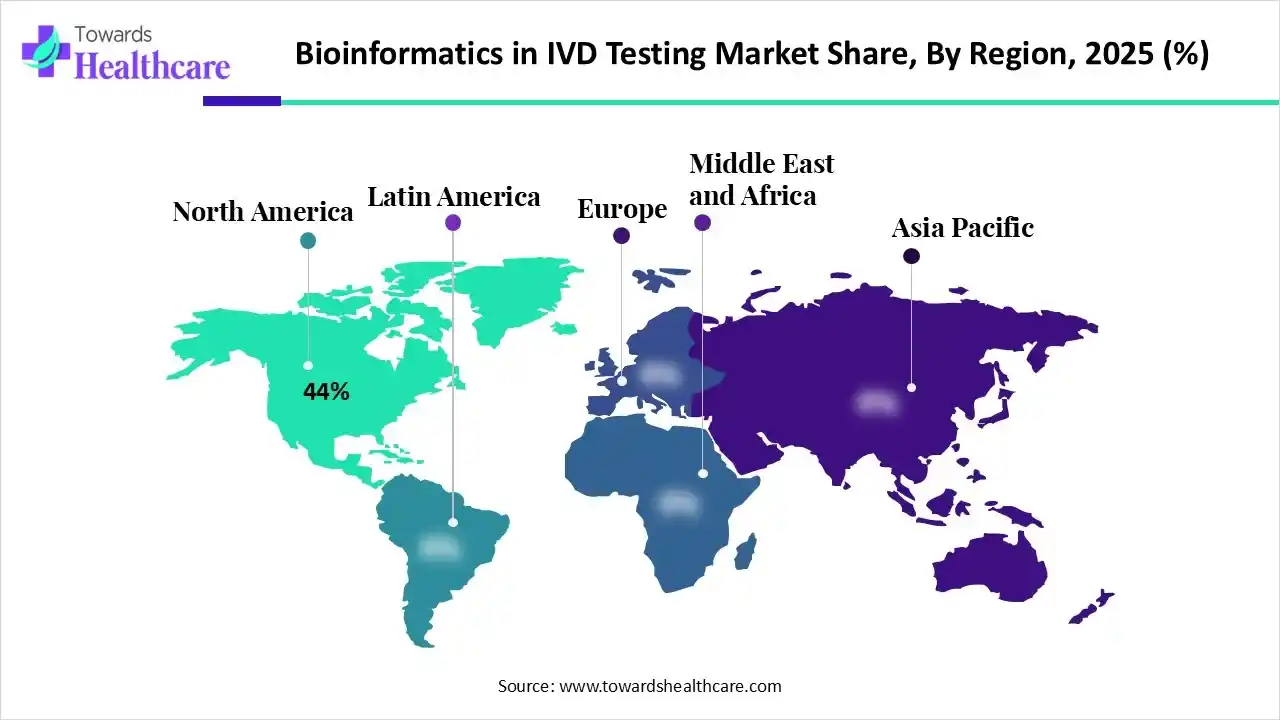
North America accounted for 44.00% of the bioinformatics in IVD testing market in 2025 and is projected to expand at a CAGR of 12.72% from 2026 to 2035. North America leads because of high clinical NGS use, many reference labs, and payer coverage for genomic tests. North America is expected to grow slower than the overall market between 2026 and 2035.
Europe has national genomic medicine programmes and strong software vendors. Europe is expected to grow broadly in line with the overall market between 2026 and 2035.
Asia Pacific grows fastest as China, Japan, India, and Australia expand clinical sequencing. Asia Pacific is expected to grow faster than the overall market between 2026 and 2035.
Latin America is adopting clinical genomics. Latin America is expected to grow broadly in line with the overall market between 2026 and 2035.
Middle East & Africa have national genome programmes. Middle East & Africa is expected to grow broadly in line with the overall market between 2026 and 2035.
Analyst View: Regional shares were built from demand, installed base, spending and supplier presence in each region. North America leads because of its mature demand base and strong suppliers. We assign Asia Pacific the highest growth premium because investment, adoption and capacity are expanding fastest there.
| Rank | Company Name | 2025 Share (%) | Key Products / Business | Headquarters |
| 1 | Illumina | 837.21% | DRAGEN, Connected Software and interpretation tools | United States |
| 2 | Thermo Fisher Scientific | 465.12% | Ion Reporter and Oncomine analysis | United States |
| 3 | QIAGEN | 372.09% | QCI interpretation and CLC software | Netherlands |
| 4 | SOPHiA GENETICS | 279.07% | SOPHiA DDM data-driven medicine platform | Switzerland |
| 5 | Velsera | 232.56% | Clinical genomics interpretation software | United States |
| 6 | Roche | 232.56% | Navify and sequencing analysis | Switzerland |
| 7 | Agilent Technologies | 186.05% | Alissa interpretation software | United States |
| 8 | DNAnexus | 139.53% | Cloud genomic data platform | United States |
| 9 | Fabric Genomics | 93.02% | AI genome interpretation | United States |
| 10 | Genoox (Franklin) | 93.02% | Franklin variant interpretation | Israel |
Note: Company shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Illumina led the bioinformatics in IVD testing market with an estimated 837.21% share of 2025 revenue, followed by Thermo Fisher Scientific at 465.12% share and QIAGEN at 372.09% share. Illumina leads with DRAGEN, Connected Software and interpretation tools, Thermo Fisher Scientific competes with ion Reporter and Oncomine analysis, and QIAGEN offers QCI interpretation and CLC software. SOPHiA GENETICS, Velsera, Roche, Agilent Technologies, DNAnexus, Fabric Genomics and Genoox (Franklin) compete through SOPHiA DDM data-driven medicine platform, clinical genomics interpretation software, navify and sequencing analysis, alissa interpretation software, cloud genomic data platform, AI genome interpretation and franklin variant interpretation.
The top 10 companies accounted for an estimated 2,930.23% of 2025 revenue, while the remaining -2,830.23% was shared among many lab-developed pipelines and niche software firms. The bioinformatics in IVD testing market is moderately fragmented, and competition centres on accuracy, regulatory compliance, knowledge-base quality, speed, cloud security, integration with sequencers and LIS, and pricing models.
Illumina: Illumina is headquartered in the United States. It held an estimated 837.21% share of the bioinformatics in IVD testing market in 2025. Its offering centres on DRAGEN, Connected Software and interpretation tools. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Thermo Fisher Scientific: Thermo Fisher Scientific is headquartered in the United States. It held an estimated 465.12% share of the bioinformatics in IVD testing market in 2025. Its offering centres on Ion Reporter and Oncomine analysis. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
QIAGEN: QIAGEN is headquartered in the Netherlands. It held an estimated 372.09% share of the bioinformatics in IVD testing market in 2025. Its offering centres on QCI interpretation and CLC software. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
SOPHiA GENETICS: SOPHiA GENETICS is headquartered in Switzerland. It held an estimated 279.07% share of the bioinformatics in IVD testing market in 2025. Its offering centres on SOPHiA DDM data-driven medicine platform. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Velsera: Velsera is headquartered in the United States. It held an estimated 232.56% share of the bioinformatics in IVD testing market in 2025. Its offering centres on Clinical genomics interpretation software. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Roche: Roche, part of F. Hoffmann-La Roche Ltd, is headquartered in Switzerland. It held an estimated 232.56% share of the bioinformatics in IVD testing market in 2025. Its offering centres on Navify and sequencing analysis. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Agilent Technologies: Agilent Technologies is headquartered in the United States. It held an estimated 186.05% share of the bioinformatics in IVD testing market in 2025. Its offering centres on Alissa interpretation software. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
DNAnexus: DNAnexus is headquartered in the United States. It held an estimated 139.53% share of the bioinformatics in IVD testing market in 2025. Its offering centres on Cloud genomic data platform. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
Fabric Genomics: Fabric Genomics is headquartered in the United States. It held an estimated 93.02% share of the bioinformatics in IVD testing market in 2025. Its offering centres on AI genome interpretation. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
Genoox (Franklin): Genoox (Franklin) is headquartered in Israel. It held an estimated 93.02% share of the bioinformatics in IVD testing market in 2025. Its offering centres on Franklin variant interpretation. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
The bioinformatics in IVD testing ecosystem links sequencing & instrument makers, bioinformatics providers, knowledge bases, laboratories and regulators, with each stage adding value before products reach end users.
| Ecosystem Stage | Role in the Market | Key Companies |
| Sequencing & Instrument Makers | Generate data | Illumina, Thermo Fisher, Element, PacBio |
| Bioinformatics Providers | Analyse and interpret data | SOPHiA GENETICS, QIAGEN, Velsera, DNAnexus |
| Knowledge Bases | Curate variant evidence | ClinVar, commercial curated databases |
| Laboratories | Run tests and report | Hospital, reference labs, IVD makers |
| Regulators | Set software and lab rules | FDA, CLIA, EU IVDR |
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Sequencing & Instrument Makers: Generate data. Key participants include Illumina, Thermo Fisher, Element, PacBio.
Bioinformatics Providers: Analyse and interpret data. Key participants include SOPHiA GENETICS, QIAGEN, Velsera, DNAnexus.
Knowledge Bases: Curate variant evidence. Key participants include ClinVar, commercial curated databases.
Laboratories: Run tests and report. Key participants include Hospital, reference labs, IVD makers.
Regulators: Set software and lab rules. Key participants include FDA, CLIA, EU IVDR.
Value in the bioinformatics in IVD testing market flows from upstream material and technology suppliers to manufacturers and service providers, then through distribution partners to end users. Companies that integrate several stages or build long-term relationships with end users capture a larger share of this value.
The Towards Healthcare Companies Quadrant positions key participants in the bioinformatics in IVD testing market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 share of the bioinformatics in IVD testing market and our assessment of its product innovation, portfolio breadth and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Leaders: Illumina, Thermo Fisher Scientific, QIAGEN, SOPHiA GENETICS, Velsera and Roche combine high market share with broad portfolios and strong innovation.
Innovators: Agilent Technologies, DNAnexus, Fabric Genomics and Genoox (Franklin) bring newer technologies and specialised products.
By Product
By Function
By Application
By End User
By Region
The bioinformatics in IVD testing market was defined as bioinformatics software, platforms and services used to process, analyse, interpret and report data from in-vitro diagnostic tests, especially next generation sequencing and PCR, including secondary analysis pipelines, variant interpretation and reporting software, data management and cloud platforms, and bioinformatics services, applied to oncology, inherited and rare disease, infectious disease and reproductive health, used by hospital and clinical laboratories, reference laboratories, IVD manufacturers and academic centres.
The 2025 base year was built bottom-up from demand volumes and average prices by product, function, application and end user and region, and checked top-down against the market-specific revenues of leading companies and published estimates. Segment, regional and company values were allocated from product, function, application and end user and region demand.
Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
The bioinformatics in IVD testing market is set for steady expansion as clinical sequencing growth and related demand keep growing. Our estimate links value to underlying demand, installed base and pricing, so the forecast follows real adoption rather than headline hype. The main upside comes from decentralised NGS and AI curation, while the main risks are regulatory validation and data privacy.