The siRNA chemical linkers reagents market is projected to grow from USD 460.00 million in 2025 to USD 1,675.64 million by 2035 because siRNA drugs are moving from rare diseases to large cardiometabolic indications, raising demand for GMP building blocks. siRNA approvals, larger patient populations, GalNAc chemistry, CDMO expansion, and some new delivery ligands support strong growth, lifting the market to USD 877.95 million by 2030 and sustaining a CAGR of 13.80% from 2026 to 2035. siRNA is a key modality in precision medicine and builds on genomics research.
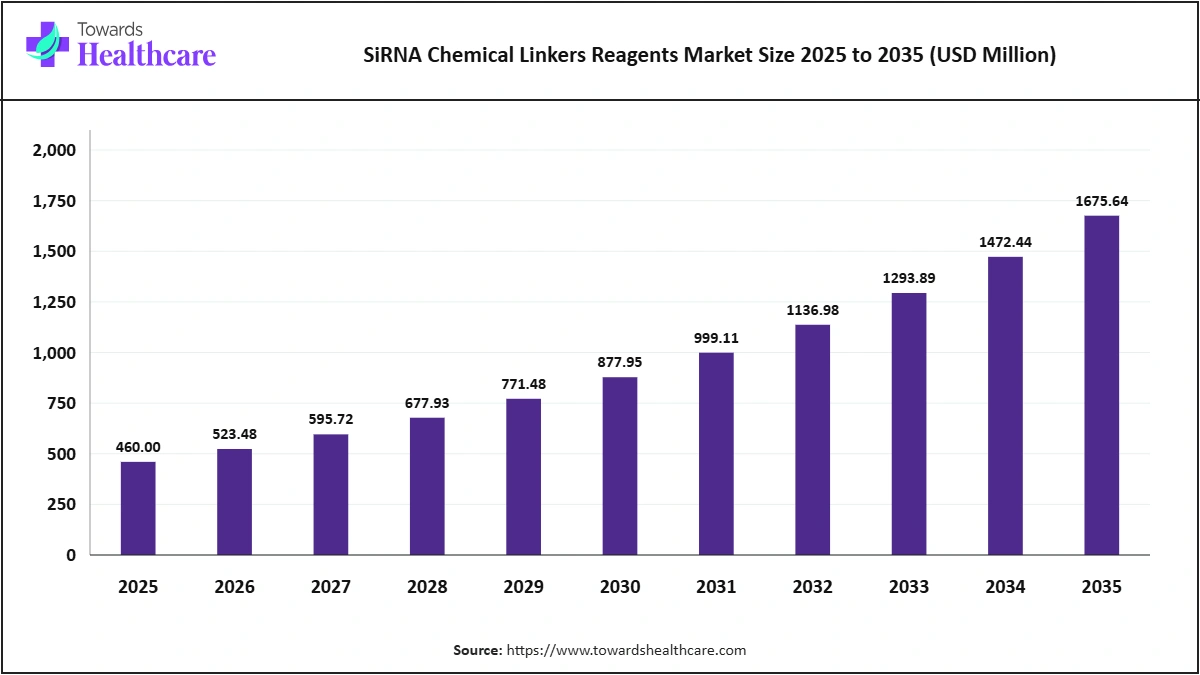
Analyst View: The market estimate was developed using siRNA synthesis volumes and the associated costs of amidites, ligands, and reagents per kilogram. These estimates were then cross-checked against supplier revenue figures to improve accuracy. Since published data covering this specific market scope is limited, the market size reflects an evidence-based assessment of available industry and supplier data.
Driver: Growing siRNA drug approvals and expanding development pipelines are driving market demand. The rising use of siRNA therapies in cardiometabolic diseases is also increasing the need for larger production volumes. As a result, demand for GMP-grade materials is growing, prompting CDMOs to expand their manufacturing capacity.
Restraint: High raw material costs and complex synthesis processes can increase production expenses. The market also faces challenges related to dependence on a limited number of suppliers and growing regulatory scrutiny, particularly around quality, consistency, and GMP compliance.
Opportunity: Emerging opportunities include the development of extrahepatic delivery ligands, increasing demand for siRNA therapies targeting large patient populations, and advances in enzymatic synthesis. Asia Pacific is also gaining attention as a potential supply base, while the growing need for custom linkers is creating new opportunities for specialized suppliers.
Market Drivers - Impact & CAGR Contribution (2026-2035)
| Driver | Impact | ≈ CAGR Contribution | Time Horizon | Key Regions |
| siRNA approvals grow | High | +5.39 pp | Short to long term | Global, strongest in North America |
| Pipelines expand | Medium | +4.55 pp | Medium to long term | Global, fastest uptake in Asia Pacific |
| Cardiometabolic drugs need large volumes | Medium | +3.87 pp | Short to medium term | Global |
| GMP demand rises | Low | +3.03 pp | Long term | Developed and emerging markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Taken together, these drivers add about 16.84 percentage points to the annual growth of the siRNA chemical linkers reagents market, with siRNA approvals growth having the largest effect. Their influence is strongest in North America, while uptake grows fastest in Asia Pacific.
Market Restraints - Impact & Negative CAGR Contribution (2026-2035)
| Restraint | Impact | ≈ Negative CAGR Contribution | Time Horizon | Key Regions |
| Raw material costs | High | -1.37 pp | Short to medium term | Global |
| Complex synthesis | High | -1.00 pp | Medium term | Price-sensitive and emerging markets |
| Supply concentration | Medium | -0.67 pp | Short term | North America and other mature markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
These restraints are expected to reduce annual growth of the siRNA chemical linkers reagents market by about 3.04 percentage points, led by raw material costs. Their effect eases over the forecast period as suppliers, buyers, and regulators adapt, leaving a net CAGR of 13.80% from 2026 to 2035.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
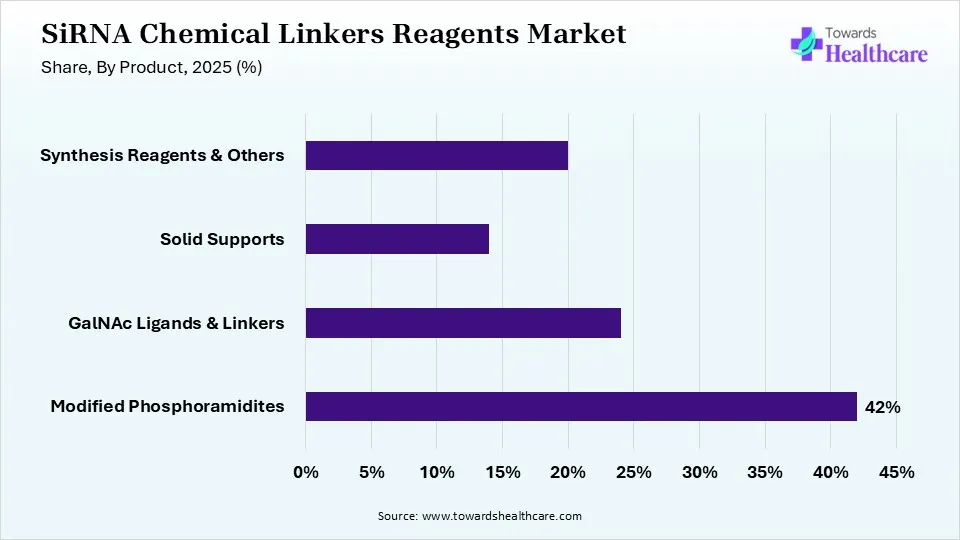
Modified Phosphoramidites: The modified phosphoramidites segment held the largest share of the siRNA chemical linkers and reagents market in 2025, accounting for 42.00% of total revenue. It is projected to grow at a CAGR of 12.77% from 2026 to 2035. Its leading position is driven by the use of 2'-F and 2'-OMe modified building blocks, which are essential for constructing siRNA strands. However, the segment is expected to grow at a slower pace than the overall market during the forecast period.
GalNAc ligands and linkers grow fastest because most approved and late-stage siRNA drugs use GalNAc to target the liver. The galnac ligands & linkers segment is expected to grow faster than the overall market over the forecast period.
Solid supports play an important role in siRNA production by providing a stable surface on which the synthesis process takes place. However, the segment is expected to grow at a slower pace than the overall market during the forecast period.
Activators, oxidisers, and deprotection reagents complete synthesis. The synthesis reagents & others segment is expected to grow slower than the overall market over the forecast period.
Solid Supports holds the smallest share today and serves more specialised needs within the siRNA chemical linkers reagents market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
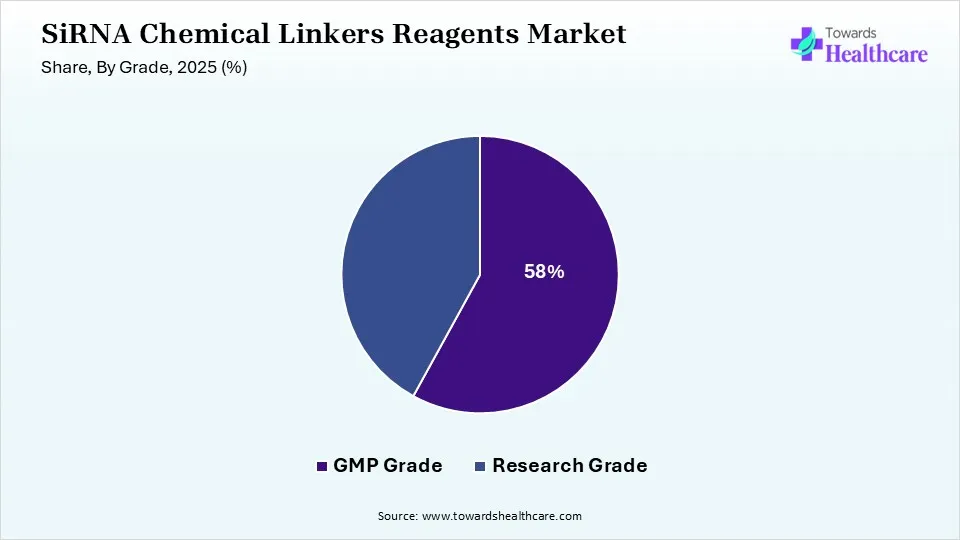
GMP Grade: The GMP Grade segment held the largest share of the siRNA chemical linkers and reagents market in 2025, accounting for 58.00% of total revenue. It is projected to grow at a CAGR of 14.21% from 2026 to 2035. Its leading position and strong growth are driven by the increasing shift of siRNA therapies towards commercial-scale production, which is creating greater demand for high-quality materials that meet stringent manufacturing standards. The segment is expected to grow faster than the overall market during the forecast period.
Research grade supports discovery. The research grade segment is expected to grow slower than the overall market over the forecast period.
Strengthening its lead in the siRNA chemical linkers reagents market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
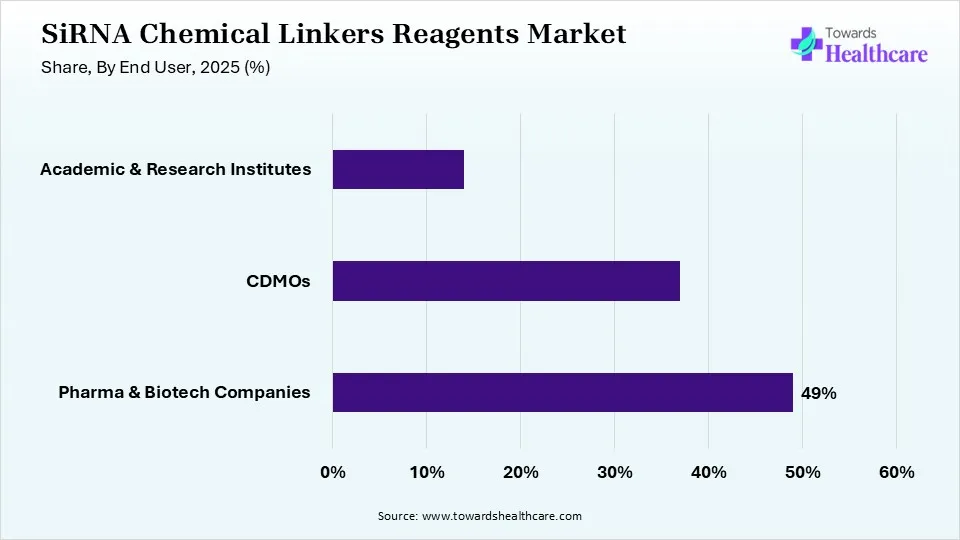
Pharma & Biotech Companies: The Pharmaceutical and Biotechnology Companies segment accounted for the largest share of the siRNA chemical linkers and reagents market in 2025, representing 49.00% of total revenue. It is projected to grow at a CAGR of 12.81% from 2026 to 2035. The segment's leading position reflects the significant use of siRNA-based materials by pharmaceutical and biotechnology companies for drug development and manufacturing. However, it is expected to grow at a slower pace than the overall market during the forecast period.
CDMOs grow fastest as oligonucleotide manufacturing is outsourced. The CDMOs segment is expected to grow faster than the overall market over the forecast period.
Demand from this segment is supported by ongoing RNA interference (RNAi) research and the use of siRNA materials in laboratory studies and early-stage therapeutic development. However, the segment is expected to grow at a slower pace than the overall market during the forecast period.
Academic & Research Institutes hold the smallest share today and serve more specialised needs within the siRNA chemical linkers reagents market.
Analyst View: Segment shares were estimated based on demand patterns, supplier product portfolios, and pricing across each category. Modified Phosphoramidites, GMP Grade, and Pharma & Biotech Companies hold leading positions in their respective segments because they address the current needs of siRNA manufacturers and end users. Meanwhile, GalNAc Ligands & Linkers and CDMOs are expected to gain market share as new technologies emerge, and the adoption of siRNA therapies expands across a wider range of users and applications.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
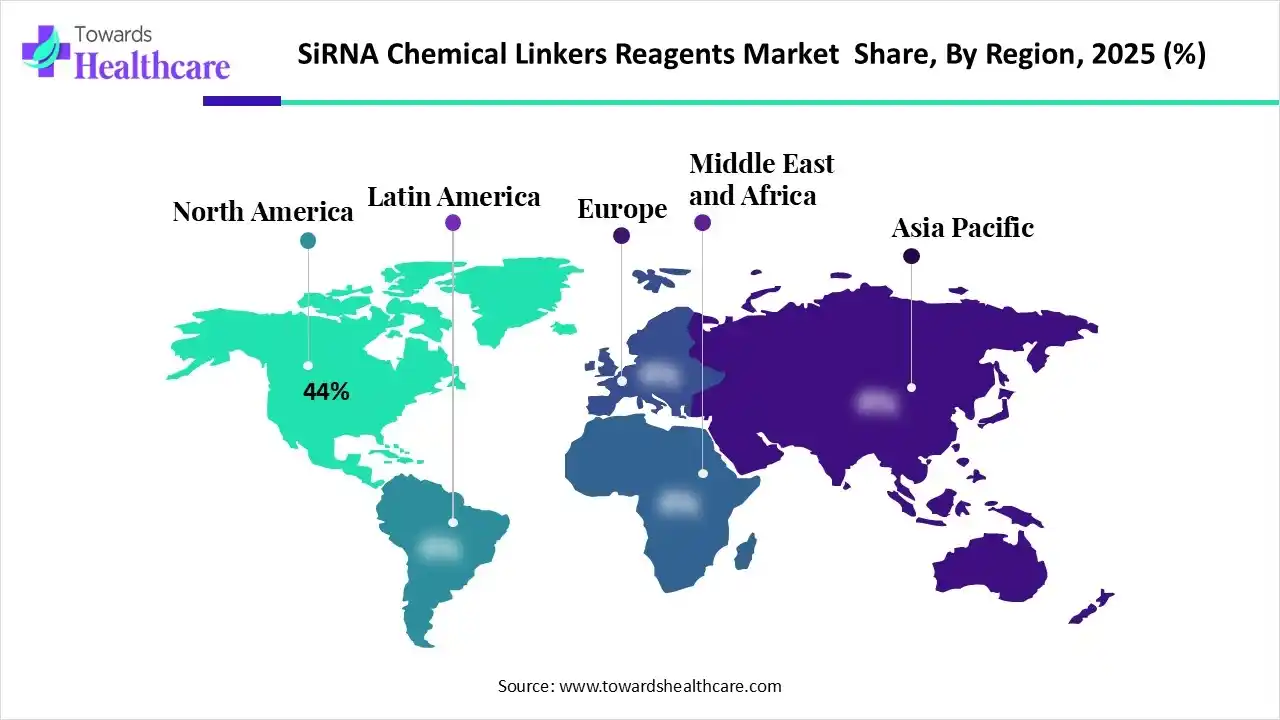
North America: North America held the largest regional share of the siRNA chemical linkers and reagents market in 2025, accounting for 44.00% of total revenue. The region is projected to grow at a CAGR of 13.26% from 2026 to 2035. Its leading position is supported by the presence of established siRNA developers, including Alnylam and Arrowhead, along with a strong network of suppliers and biotechnology companies. However, North America is expected to grow at a slower pace than the overall market during the forecast period.
Europe has strong chemistry suppliers and CDMOs. Europe is expected to grow broadly in line with the overall market between 2026 and 2035.
Asia Pacific Growth in the region is supported by the expansion of China's oligonucleotide CDMOs and reagent manufacturers, which are increasing their production capabilities to meet rising demand. Asia Pacific is expected to grow faster than the overall market during the forecast period.
Latin America has limited activity. Latin America is expected to grow broadly in line with the overall market between 2026 and 2035.
Middle East & Africa Market development in the region is still at an early stage, with siRNA research and related activities gradually gaining traction. The region is expected to grow broadly in line with the overall market during the forecast period.
Analyst View: Regional shares were built from demand, installed base, spending, and supplier presence in each region. North America leads because of its mature demand base and strong suppliers. We assign Asia Pacific the highest growth premium because investment, adoption, and capacity are expanding fastest there.
| Rank | Company Name | 2025 Share (%) | Key Products / Business | Headquarters |
| 1 | Thermo Fisher Scientific | 12.61% | Phosphoramidites and synthesis reagents | United States |
| 2 | Merck KGaA (MilliporeSigma) | 10.43% | Phosphoramidites and oligo reagents | Germany |
| 3 | Hongene Biotech | 9.57% | Nucleosides, phosphoramidites and GalNAc | United States |
| 4 | Agilent Technologies | 6.52% | Oligonucleotide manufacturing and reagents | United States |
| 5 | Glen Research (LGC) | 4.78% | Phosphoramidites and modifiers | United States |
| 6 | WuXi STA | 4.35% | Oligonucleotide CDMO and chemistry | China |
| 7 | Biosearch Technologies (LGC) | 3.91% | Oligo synthesis reagents and supports | United States |
| 8 | Nitto Avecia | 3.48% | Oligonucleotide CDMO and supports | United States |
| 9 | Bachem | 3.04% | Oligonucleotide CDMO | Switzerland |
| 10 | ChemGenes | 2.61% | Phosphoramidites and linkers | United States |
Note: Company shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Thermo Fisher Scientific led the siRNA chemical linkers reagents market with an estimated 12.61% share of 2025 revenue, followed by Merck KGaA (MilliporeSigma) at 10.43% share and Hongene Biotech at 9.57% share. Thermo Fisher Scientific leads with phosphoramidites and synthesis reagents, Merck KGaA (MilliporeSigma) competes with phosphoramidites and oligo reagents, and Hongene Biotech offers nucleosides, phosphoramidites, and GalNAc. Agilent Technologies, Glen Research (LGC), WuXi STA, Biosearch Technologies (LGC), Nitto Avecia, Bachem and ChemGenes compete through oligonucleotide manufacturing and reagents, phosphoramidites and modifiers, oligonucleotide CDMO and chemistry, oligo synthesis reagents and supports, oligonucleotide CDMO and supports, oligonucleotide CDMO and phosphoramidites and linkers.
The top 10 companies accounted for an estimated 61.30% of the siRNA chemical linkers and reagents market revenue in 2025, while the remaining 38.70% was distributed among specialty chemical suppliers and CDMOs. This indicates a moderately concentrated market, where competition is shaped by product purity, GMP documentation, manufacturing scale-up capabilities, expertise in GalNAc chemistry, supply reliability, and pricing.
Thermo Fisher Scientific: Thermo Fisher Scientific is headquartered in the United States. It held an estimated 12.61% share of the siRNA chemical linkers reagents market in 2025. Its offering centres on Phosphoramidites and synthesis reagents. In the Towards Heathcare Companies Quadrant it is positioned as a Leader.
Merck KGaA (MilliporeSigma): Merck KGaA (MilliporeSigma) is headquartered in Germany and held an estimated 10.43% share of the siRNA chemical linkers and reagents market in 2025. Its product portfolio focuses on phosphoramidites and oligonucleotide synthesis reagents. In the Towards Heathcare Companies Quadrant, the company is positioned as a Leader.
Hongene Biotech: Hongene Biotech is headquartered in the United States. It held an estimated 9.57% share of the siRNA chemical linkers reagents market in 2025. Its offering centres on Nucleosides, phosphoramidites, and GalNAc. In the Towards Heathcare Companies Quadrant it is positioned as a Leader.
Agilent Technologies: Agilent Technologies is headquartered in the United States and accounted for an estimated 6.52% share of the siRNA chemical linkers and reagents market in 2025. Its portfolio includes oligonucleotide manufacturing solutions and related reagents. In the Towards Heathcare Companies Quadrant, Agilent Technologies is positioned as a leader.
Glen Research (LGC): Glen Research (LGC) is headquartered in the United States. It held an estimated 4.78% share of the siRNA chemical linkers reagents market in 2025. Its offering centres on Phosphoramidites and modifiers. In the Towards Heathcare Companies Quadrant it is positioned as a Leader.
WuXi STA: WuXi STA is headquartered in China. It held an estimated 4.35% share of the siRNA chemical linkers reagents market in 2025. Its offering centres on Oligonucleotide CDMO and chemistry. In the Towards Heathcare Companies Quadrant it is positioned as a Leader.
Biosearch Technologies (LGC): Biosearch Technologies (LGC) is headquartered in the United States. It held an estimated 3.91% share of the siRNA chemical linkers reagents market in 2025. Its offering centres on Oligo synthesis reagents and supports. In the Towards Heathcare Companies Quadrant it is positioned as an innovator.
Nitto Avecia: Nitto Avecia is headquartered in the United States. It held an estimated 3.48% share of the siRNA chemical linkers reagents market in 2025. Its offering centres on Oligonucleotide CDMO and support. In the Towards Heathcare Companies Quadrant it is positioned as an Innovator.
Bachem: Bachem is headquartered in Switzerland. It held an estimated 3.04% share of the siRNA chemical linkers reagents market in 2025. Its offering centres on Oligonucleotide CDMO. In the Towards Heathcare Companies Quadrant it is positioned as an Innovator.
ChemGenes: ChemGenes is headquartered in the United States. It held an estimated 2.61% share of the siRNA chemical linkers reagents market in 2025. Its offering centres on Phosphoramidites and linkers. In the Towards Heathcare Companies Quadrant it is positioned as an Innovator.
The siRNA chemical linkers reagents ecosystem links chemistry suppliers, CDMOs, drug developers, researchers, and regulators, with each stage adding value before products reach end users.
| Ecosystem Stage | Role in the Market | Key Companies |
| Chemistry Suppliers | Make amidites and ligands | Thermo Fisher, Merck KGaA, Hongene |
| CDMOs | Synthesise siRNA | Agilent, WuXi STA, Nitto Avecia, Bachem |
| Drug Developers | Develop siRNA drugs | Alnylam, Arrowhead, Novartis |
| Researchers | Use siRNA in research | Universities and biotech labs |
| Regulators | Approve drugs and set GMP | FDA, EMA |
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Chemistry Suppliers: Make amidites and ligands. Key participants include Thermo Fisher, Merck KGaA, Hongene.
CDMOs: Synthesise siRNA. Key participants include Agilent, WuXi STA, Nitto Avecia, Bachem.
Drug Developers: Develop siRNA drugs. Key participants include Alnylam, Arrowhead, Novartis.
Researchers: Use siRNA in research. Key participants include Universities and biotech labs.
Regulators: Approve drugs and set GMP. Key participants include FDA, EMA.
Value in the siRNA chemical linkers reagents market flows from upstream material and technology suppliers to manufacturers and service providers, then through distribution partners to end users. Companies that integrate several stages or build long-term relationships with end users capture a larger share of this value.
The Towards Healthcare Companies Quadrant positions key participants in the siRNA chemical linkers reagents market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 share of the siRNA chemical linkers reagents market and our assessment of its product innovation, portfolio breadth and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Leaders: Thermo Fisher Scientific, Merck KGaA (MilliporeSigma), Hongene Biotech, Agilent Technologies, Glen Research (LGC) and WuXi STA combine high market share with broad portfolios and strong innovation.
Innovators: Biosearch Technologies (LGC), Nitto Avecia, Bachem and ChemGenes bring newer technologies and specialised products.
By Product
By Grade
By End User
By Region
The siRNA chemical linkers reagents market was defined as chemicals, linkers and reagents used to synthesise and modify small interfering RNA, including modified nucleoside phosphoramidites (2'-F, 2'-OMe), GalNAc and other targeting ligands and linkers, solid supports, activators and synthesis reagents, in research and GMP grades, used for therapeutic siRNA development and manufacturing, research and diagnostics by pharmaceutical and biotechnology companies, CDMOs and academic institutes. The 2025 base year was built bottom-up from demand volumes and average prices by product, grade and end user and region, and checked top-down against the market-specific revenues of leading companies and published estimates.
Segment, regional and company values were allocated from product, grade and end user and region demand. Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View: The siRNA chemical linkers reagents market is set for steady expansion as siRNA approvals and related demand keep growing. Our estimate links value to underlying demand, installed base and pricing, so the forecast follows real adoption rather than headline hype. The main upside comes from large-volume siRNA drugs and new ligands, while the main risks are raw material costs and supply concentration.
1.3.1 Market Value (USD) and Annual Growth
1.3.2 Historical Market Analysis
1.3.3 Market Growth Analysis and CAGR 2026–2035
2.2.1 siRNA approvals grow
2.2.2 Pipelines expand
2.2.3 Cardiometabolic drugs need large volumes
2.2.4 GMP demand rises
2.4.1 Raw material costs
2.4.2 Complex synthesis
2.4.3 Supply concentration
2.4.4 Regulatory scrutiny
2.7.1 Extrahepatic delivery ligands
2.7.2 Large-volume siRNA drugs
2.7.3 Enzymatic synthesis
2.7.4 Asia Pacific supply
2.8.1 GalNAc and extrahepatic ligands
2.8.2 Scale-up of GMP amidites
2.8.3 Liquid-phase and enzymatic synthesis
2.8.4 Supply chain diversification
2.8.5 New modifications for durability
2.8.6 Cardiometabolic siRNA drugs
3.1.1 Modified Phosphoramidites: Market Share and CAGR
3.1.2 GalNAc Ligands & Linkers: Market Share and CAGR
3.1.3 Solid Supports: Market Share and CAGR
3.1.4 Synthesis Reagents & Others: Market Share and CAGR
3.2.1 GMP Grade: Market Share and CAGR
3.2.2 Research Grade: Market Share and CAGR
3.3.1 Pharma & Biotech Companies: Market Share and CAGR
3.3.2 CDMOs: Market Share and CAGR
3.3.3 Academic & Research Institutes: Market Share and CAGR
4.1.1 Market Size and Forecast, 2025–2035
4.1.2 Market Share by Product
4.1.3 Demand Drivers, Regulation and Local Competition
4.2.1 Market Size and Forecast, 2025–2035
4.2.2 Market Share by Product
4.2.3 Demand Drivers, Regulation and Local Competition
4.3.1 Market Size and Forecast, 2025–2035
4.3.2 Market Share by Product
4.3.3 Demand Drivers, Regulation and Local Competition
4.4.1 Market Size and Forecast, 2025–2035
4.4.2 Market Share by Product
4.4.3 Demand Drivers, Regulation and Local Competition
4.5.1 Market Size and Forecast, 2025–2035
4.5.2 Market Share by Product
4.5.3 Demand Drivers, Regulation and Local Competition
5.5.1 Product Portfolio Benchmarking
5.5.2 Geographic Presence Benchmarking
5.5.3 Technology and Innovation Benchmarking
6.1.1 Instrument list price and discount analysis
6.1.2 Consumables and reagent pricing per test or sample
6.1.3 Service contract and subscription pricing
6.1.4 Academic vs. biopharma pricing tiers
7.1.1 Pharmaceutical and biotechnology companies
7.1.2 Academic and government research institutes
7.1.3 CROs, CDMOs and core facilities
7.1.4 Clinical and diagnostic laboratories
9.1.1 Key raw materials and component sourcing
9.1.2 OEM and contract manufacturing
9.1.3 Distributor and e-procurement channels
9.1.4 Cold chain and logistics requirements
11.1.1 Automation and high-throughput workflows
11.1.2 Digital, cloud and AI-enabled analysis
11.1.3 Next-generation platforms and consumables
11.1.4 Patent and IP landscape
12.1.1 Research-use-only vs. IVD regulatory pathways
12.1.2 GMP and quality standards for bioprocessing
12.1.3 Biosafety and laboratory standards
12.1.4 Data integrity and compliance requirements
17.1.1 Company Overview
17.1.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.1.3 Financial Performance and Market Share
17.1.4 Recent Developments and Strategy
17.1.5 SWOT Analysis
17.2.1 Company Overview
17.2.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.2.3 Financial Performance and Market Share
17.2.4 Recent Developments and Strategy
17.2.5 SWOT Analysis
17.3.1 Company Overview
17.3.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.3.3 Financial Performance and Market Share
17.3.4 Recent Developments and Strategy
17.3.5 SWOT Analysis
17.4.1 Company Overview
17.4.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.4.3 Financial Performance and Market Share
17.4.4 Recent Developments and Strategy
17.4.5 SWOT Analysis
17.5.1 Company Overview
17.5.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.5.3 Financial Performance and Market Share
17.5.4 Recent Developments and Strategy
17.5.5 SWOT Analysis
17.6.1 Company Overview
17.6.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.6.3 Financial Performance and Market Share
17.6.4 Recent Developments and Strategy
17.6.5 SWOT Analysis
17.7.1 Company Overview
17.7.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.7.3 Financial Performance and Market Share
17.7.4 Recent Developments and Strategy
17.7.5 SWOT Analysis
17.8.1 Company Overview
17.8.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.8.3 Financial Performance and Market Share
17.8.4 Recent Developments and Strategy
17.8.5 SWOT Analysis
17.9.1 Company Overview
17.9.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.9.3 Financial Performance and Market Share
17.9.4 Recent Developments and Strategy
17.9.5 SWOT Analysis
17.10.1 Company Overview
17.10.2 SiRNA Chemical Linkers Reagents Product Portfolio
17.10.3 Financial Performance and Market Share
17.10.4 Recent Developments and Strategy
17.10.5 SWOT Analysis