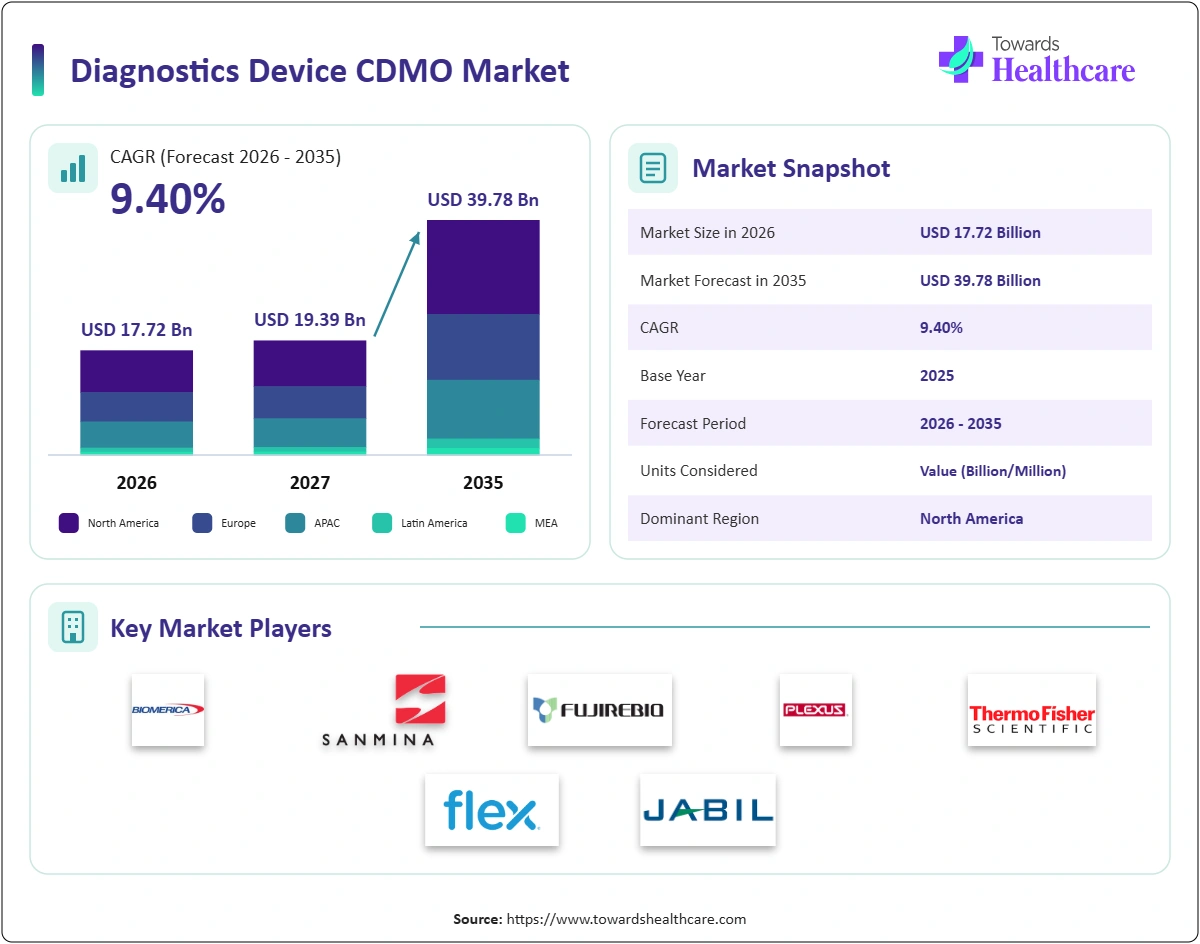
The diagnostics device CDMO market is projected to grow from USD 16.20 billion in 2025 to USD 39.78 billion by 2035 because diagnostic companies increasingly outsource development and manufacturing to move faster and avoid building plants. Diagnostic innovation, start-up growth, regulatory complexity, and point-of-care demand support strong growth, lifting the market to USD 25.39 billion by 2030 and sustaining a CAGR of 9.40%throughout the forecast timeframe. CDMOs also support 3D-printed medical device prototypes and precision medicine companion tests.
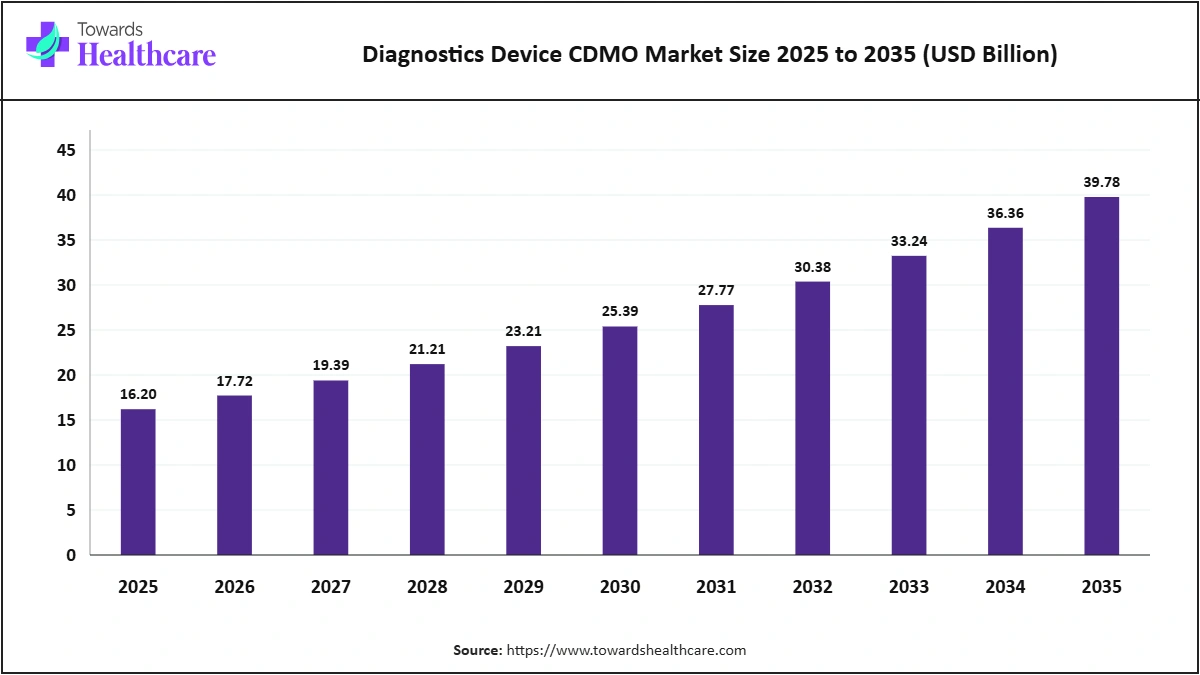
Analyst View: We built the estimate from outsourced share of diagnostic device production and development spending by technology and region, cross-checked against diagnostic revenues of leading contract manufacturers. Our value sits above published comparable estimates because it includes instruments and development services.
| Driver | Impact | ≈ CAGR Contribution | Time Horizon | Key Regions |
| Diagnostic innovation grows | High | +3.67 pp | Short to long term | Global, strongest in North America |
| Start-ups lack plants | Medium | +3.10 pp | Medium to long term | Global, fastest uptake in Asia Pacific |
| Regulation is more complex | Medium | +2.64 pp | Short to medium term | Global |
| Point-of-care demand rises | Low | +2.06 pp | Long term | Developed and emerging markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
Taken together, these drivers add about 11.47 percentage points to the annual growth of the diagnostics device CDMO market, with diagnostic innovation growing having the largest effect. Their influence is strongest in North America, while uptake grows fastest in Asia Pacific.
| Restraint | Impact | ≈ Negative CAGR Contribution | Time Horizon | Key Regions |
| Quality and compliance risks | High | -0.93 pp | Short to medium term | Global |
| IP concerns | High | -0.68 pp | Medium term | Price-sensitive and emerging markets |
| Pricing pressure | Medium | -0.45 pp | Short term | North America and other mature markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
These restraints are expected to reduce annual growth of the diagnostics device CDMO market by about 2.07 percentage points, led by quality and compliance risks. Their effect eases over the forecast period as suppliers, buyers, and regulators adapt, leaving a net CAGR of 9.40% from 2026 to 2035.
Growing demand for molecular point-of-care diagnostics is creating opportunities for CDMOs to develop and manufacture compact testing platforms, cartridges, and consumables. Expansion of companion diagnostics is encouraging pharmaceutical companies to outsource specialized assay development and validation. Additionally, Asia's expanding manufacturing infrastructure offers cost-efficient production opportunities, while increasing regulatory requirements are supporting demand for compliance and validation services. Rising home-testing adoption further creates opportunities for portable diagnostic devices and rapid test manufacturing.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
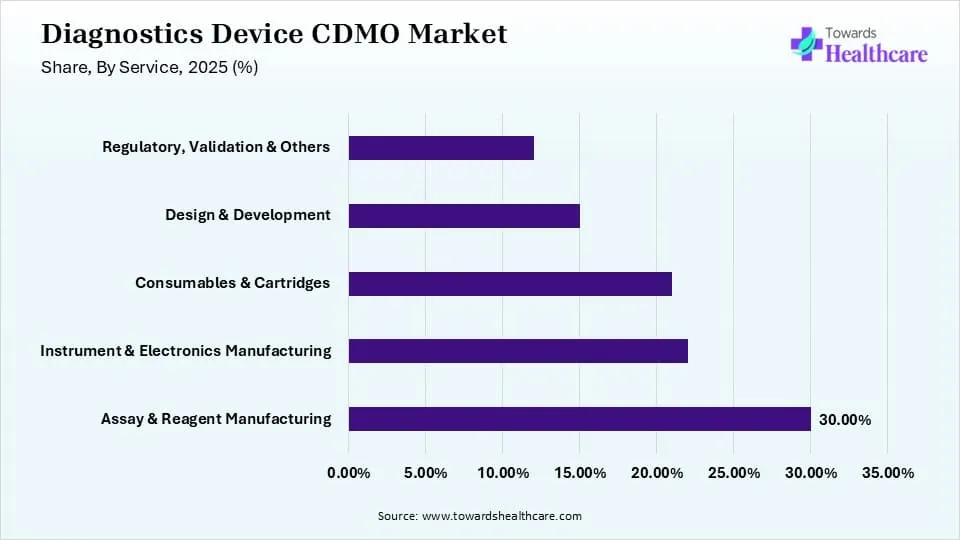
Assay & Reagent Manufacturing: This category held a 30.00% share of the diagnostics device CDMO market in 2025 and is forecast to grow at a CAGR of 8.79%throughout the forecast timeframe. Assay and reagent manufacturing leads because diagnostic tests require antibodies, enzymes, buffers, and controls produced under stringent quality systems. Growth is expected to remain slower than the overall market over the forecast period.
Instrument & Electronics Manufacturing: These services support the production of diagnostic analyzers, readers, and electronic components used across clinical testing platforms. Growth is expected to remain broadly in line with the overall market.
Consumables & Cartridges: Demand is supported by increasing production of disposable diagnostic components, including microfluidic cartridges and lateral flow test formats. Growth is expected to remain broadly in line with the overall market.
Design & Development: Increasing outsourcing by diagnostic start-ups and emerging IVD companies is driving demand for product design, prototyping, assay development, and engineering expertise. Growth is expected to exceed the overall market over the forecast period.
Regulatory, Validation & Others: Demand for regulatory documentation, product validation, and quality assurance services is increasing as manufacturers address FDA requirements and EU IVDR compliance. Growth is expected to remain broadly in line with the overall market.
Segment Outlook: Assay & Reagent Manufacturing remains the largest service segment through 2035, holding about 28.38% of the market in 2035, while Design & Development records the highest CAGR of 11.19% from 2026 to 2035. Regulatory, Validation & Others holds the smallest share today and serves more specialized needs within the diagnostics device CDMO market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
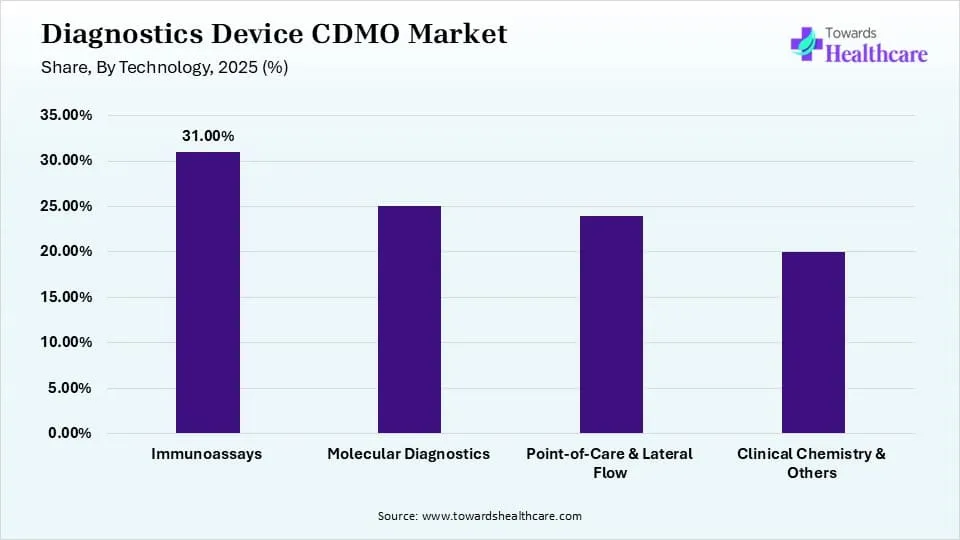
Immunoassays: Holding a 31.00% share of the diagnostics device CDMO market in 2025, this category is set to grow at a CAGR of 8.73%throughout the forecast timeframe. Immunoassays lead because routine and specialized diagnostic tests widely rely on antibody-based detection methods. Growth is expected to remain slower than the overall market over the forecast period.
Molecular Diagnostics: Increasing demand for PCR-based testing, sequencing technologies, and precision diagnostics is driving outsourcing of molecular diagnostic device development and manufacturing. Growth is expected to exceed the overall market.
Point-of-Care & Lateral Flow: Growing adoption of rapid diagnostic solutions in clinics, pharmacies and home-testing settings is supporting demand for outsourced device and test manufacturing. Growth is expected to remain broadly in line with the overall market.
Clinical Chemistry & Others: Demand is supported by continued outsourcing of clinical chemistry analyzers, testing consumables, and other diagnostic technologies. Growth is expected to remain broadly in line with the overall market.
Segment Outlook: Immunoassays remains the largest technology segment through 2035, holding about 29.14% of the market in 2035, while Molecular Diagnostics records the highest CAGR of 10.63%throughout the forecast timeframe. Clinical Chemistry & Others holds the smallest share today and serves more specialized needs within the diagnostics device CDMO market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
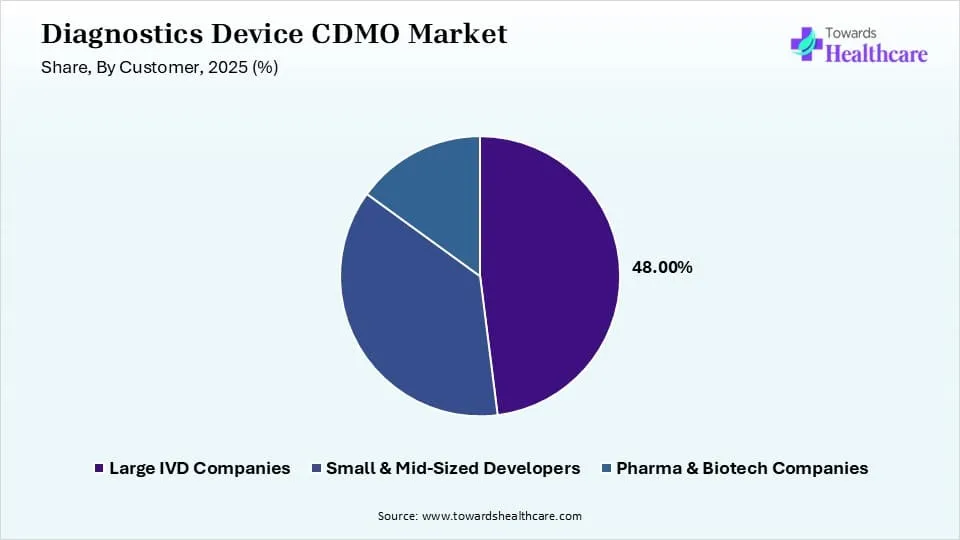
Large IVD Companies: Holding a 48.00% share of the diagnostics device CDMO market in 2025, this category is forecast to grow at a CAGR of 8.60% from 2026 to 2035. Large IVD manufacturers lead demand by outsourcing component production and excess manufacturing requirements to specialized CDMO providers. Growth is expected to remain slower than the overall market over the forecast period.
Small & Mid-Sized Developers: Limited in-house manufacturing infrastructure and financial resources encourage smaller diagnostic developers to outsource product design, development, and commercial production. Growth is expected to exceed the overall market over the forecast period.
Pharma & Biotech Companies: Increasingly outsource companion diagnostic development, assay validation, and device manufacturing to support personalized medicine and targeted therapies. Growth is expected to remain slower than the overall market over the forecast period.
Segment Outlook: Large IVD Companies remains the largest customer segment through 2035, holding about 44.60% of the market in 2035, while Small & Mid-Sized Developers records the highest CAGR of 10.50%throughout the forecast timeframe. Pharma & Biotech Companies hold the smallest share today and serve more specialized needs within the diagnostics device CDMO market.
Analyst View: Segment shares were allocated from demand, product portfolios, and pricing in each category. Assay & Reagent Manufacturing, Immunoassays and Large IVD Companies lead their categories because they meet the core needs of today's buyers. We expect Design & Development, Molecular Diagnostics and Small & Mid-Sized Developers to gain share as newer technologies, users and applications grow faster.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
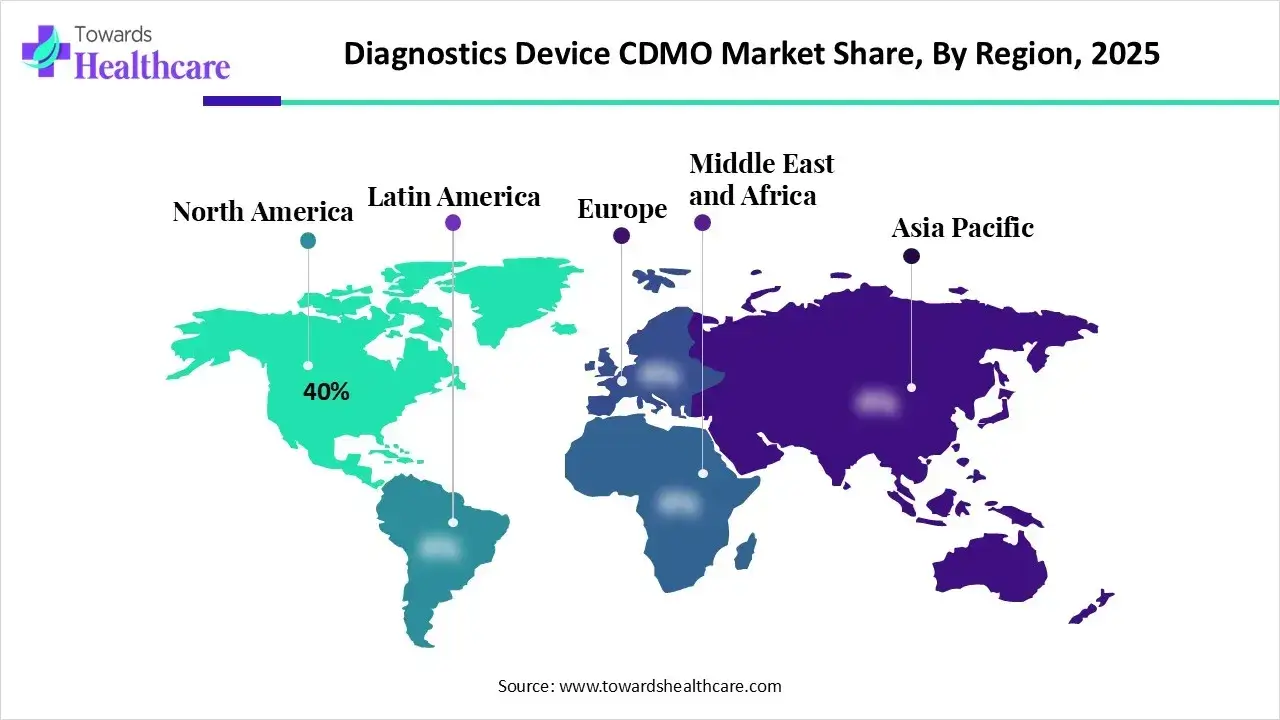
North America: Accounting for the largest regional share at 40.00% in 2025, North America is expected to register a CAGR of 8.84% from 2026 to 2035. Its strong base of IVD developers, FDA-focused contract manufacturers, and venture-backed diagnostic start-ups supports its leading position. Growth is expected to remain slower than the overall market over the forecast period.
Europe: Its established CDMO industry and increasing demand for EU IVDR regulatory support strengthen the region's position in diagnostic device outsourcing. Growth is expected to remain broadly in line with the overall market.
Asia Pacific: Driven by cost-efficient, high-quality manufacturing capabilities across China, India, Singapore and Malaysia,The region is forecast to record the fastest growth, with a CAGR of 10.44% from 2026 to 2035, exceeding the overall market average.
Latin America: Gradual improvements in healthcare infrastructure and local manufacturing capabilities are creating opportunities for CDMO providers. Growth is expected to remain broadly in line with the overall market.
Middle East & Africa: Investments in domestic healthcare manufacturing and efforts to strengthen local diagnostic supply chains are creating opportunities for CDMO providers. Growth is expected to remain broadly in line with the overall market.
Analyst View: Regional shares were built from demand, installed base, spending and supplier presence in each region. North America leads because of its mature demand base and strong suppliers. We assign Asia Pacific the highest growth premium because investment, adoption and capacity are expanding fastest there.
| Rank | Company Name | 2025 Share (%) | Key Products / Business | Headquarters |
| 1 | Jabil Healthcare | 43.21% | Diagnostic instrument and device manufacturing | United States |
| 2 | Flex | 37.04% | Medical and diagnostic device manufacturing | Singapore |
| 3 | Thermo Fisher Scientific (OEM) | 30.86% | OEM reagents and diagnostic components | United States |
| 4 | Phillips-Medisize (Molex) | 24.69% | Diagnostic consumables and devices | United States |
| 5 | Plexus | 24.69% | Diagnostic instrument design and manufacturing | United States |
| 6 | Integer Holdings | 18.52% | Device components | United States |
| 7 | Fujirebio (CDMO) | 18.52% | Assay development and manufacturing | Japan |
| 8 | Sanmina | 18.52% | Diagnostic instrument manufacturing | United States |
| 9 | Abingdon Health | 6.17% | Lateral flow CRO and CDMO | United Kingdom |
| 10 | Biomerica | 6.17% | IVD development and manufacturing | United States |
Note: Company shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
Jabil Healthcare led the diagnostics device CDMO market with an estimated 43.21% share of 2025 revenue, followed by Flex at 37.04% share and Thermo Fisher Scientific (OEM) at 30.86% share. Jabil Healthcare leads with diagnostic instrument and device manufacturing, Flex competes with medical and diagnostic device manufacturing, and Thermo Fisher Scientific (OEM) offers OEM reagents and diagnostic components. Phillips-Medisize (Molex), Plexus, Integer Holdings, Fujirebio (CDMO), Sanmina, Abingdon Health and Biomerica compete through diagnostic consumables and devices, diagnostic instrument design and manufacturing, device components, assay development and manufacturing, diagnostic instrument manufacturing, lateral flow CRO and CDMO and IVD development and manufacturing.
The top 10 companies accounted for an estimated 228.40% of 2025 revenue, while the remaining -128.40% was shared among many specialist assay, cartridge and lateral flow manufacturers. The diagnostics device CDMO market is fragmented, and competition centers on quality systems, regulatory expertise, scale-up capability, technology breadth, supply security, speed to market and cost.
Flex: Based in Singapore, Flex provides outsourced manufacturing solutions for medical and diagnostic devices. Its manufacturing expertise and global production network support diagnostic companies seeking scalable production capabilities. The company holds a Leader position in the Towards healthcare Companies Quadrant.
Thermo Fisher Scientific (OEM): A U.S.-based company, Thermo Fisher Scientific offers OEM manufacturing services, including diagnostic reagents and components. Its capabilities support IVD manufacturers across product development and supply requirements. Towards healthcare classifies the company as a Leader in its Companies Quadrant.
Phillips-Medisize (Molex): Operating under Koch Industries, Inc., Phillips-Medisize is headquartered in the United States and specializes in diagnostic consumables and device manufacturing. Its expertise supports the development and production of healthcare diagnostic solutions. The company is positioned as a Leader in the Towards healthcare Companies Quadrant.
Plexus: With headquarters in the United States, Plexus focuses on diagnostic instrument design, engineering and manufacturing. Its integrated capabilities help diagnostic companies move products from development to commercial production. Towards healthcare identifies the company as a Leader in its Companies Quadrant.
Integer Holdings: Integer Holdings is a U.S.-based manufacturer specializing in components for medical and diagnostic devices. Its engineering and manufacturing capabilities support the production requirements of healthcare technology companies. The company occupies a Leader position in the Towards healthcare Companies Quadrant.
Fujirebio (CDMO): Part of H.U. Group Holdings, Inc., Fujirebio is headquartered in Japan and provides assay development and manufacturing services. Its expertise supports diagnostic companies seeking specialized assay development and outsourced production. Towards healthcare positions the company as an Innovator in its Companies Quadrant.
Sanmina: Headquartered in the United States, Sanmina offers diagnostic instrument manufacturing supported by its electronics engineering and production capabilities. Its services help diagnostic developers scale complex instrument production. The company is classified as an Innovator in the Towards healthcare Companies Quadrant.
Abingdon Health: Based in the United Kingdom, Abingdon Health specializes in lateral flow contract research and manufacturing services. Its capabilities cover the development and production of rapid diagnostic tests for healthcare and other applications. Towards healthcare identifies the company as an Innovator in its Companies Quadrant.
Biomerica: A U.S.-based diagnostics company, Biomerica focuses on in vitro diagnostic (IVD) product development and manufacturing. Its capabilities support the development and commercialization of diagnostic testing solutions. The company holds an Innovator position in the Towards healthcare Companies Quadrant.
The diagnostics device CDMO ecosystem links material & component suppliers, cdmos, diagnostic brand owners, users and regulators, with each stage adding value before products reach end users.
| Ecosystem Stage | Role in the Market | Key Companies |
| Material & Component Suppliers | Supply antibodies, plastics and electronics | Reagent, resin and electronics suppliers |
| CDMOs | Develop and make diagnostics | Jabil, Flex, Plexus, Abingdon Health, Fujirebio |
| Diagnostic Brand Owners | Own and sell tests | IVD companies, start-ups, pharma |
| Users | Use tests | Labs, hospitals, clinics, consumers |
| Regulators | Approve devices and plants | FDA, EU IVDR notified bodies, ISO 13485 |
Sources: Company press releases, expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
Material & Component Suppliers: Supply antibodies, plastics and electronics. Key participants include Reagent, resin and electronics suppliers.
CDMOs: Develop and make diagnostics. Key participants include Jabil, Flex, Plexus, Abingdon Health, Fujirebio.
Diagnostic Brand Owners: Own and sell tests. Key participants include IVD companies, start-ups, pharma.
Users: Use tests. Key participants include Labs, hospitals, clinics, consumers.
Regulators: Approve devices and plants. Key participants include FDA, EU IVDR notified bodies, ISO 13485.
Value in the diagnostics device CDMO market flows from upstream material and technology suppliers to manufacturers and service providers, then through distribution partners to end users. Companies that integrate several stages or build long-term relationships with end users capture a larger share of this value.
The Towards healthcare Companies Quadrant positions key participants in the diagnostics device CDMO market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 share of the diagnostics device CDMO market and our assessment of its product innovation, portfolio breadth and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
Leaders: Jabil Healthcare, Flex, Thermo Fisher Scientific (OEM), Phillips-Medisize (Molex), Plexus and Integer combine high market share with broad portfolios and strong innovation.
Innovators: Fujirebio (CDMO), Sanmina, Abingdon Health and Biomerica bring newer technologies and specialised products.
By Service
By Technology
By Customer
By Region
The diagnostics device CDMO market was defined as contract development and manufacturing services for diagnostic devices, including design and development, assay and reagent manufacturing, instrument and electronics manufacturing, consumables and cartridge production, regulatory and validation support, and packaging and supply chain services, for immunoassay, molecular, point-of-care and lateral flow, clinical chemistry and other diagnostics, used by large IVD companies, small and mid-sized diagnostic developers, and pharmaceutical and biotechnology companies.
The 2025 base year was built bottom-up from demand volumes and average prices by service, technology and customer and region, and checked top-down against the market-specific revenues of leading companies and published estimates. Segment, regional and company values were allocated from service, technology and customer and region demand. Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View: The diagnostics device CDMO market is set for steady expansion as diagnostic innovation and related demand keep growing. Our estimate links value to underlying demand, installed base and pricing, so the forecast follows real adoption rather than headline hype. The main upside comes from molecular point-of-care and companion diagnostics, while the main risks are quality risks and pricing pressure.