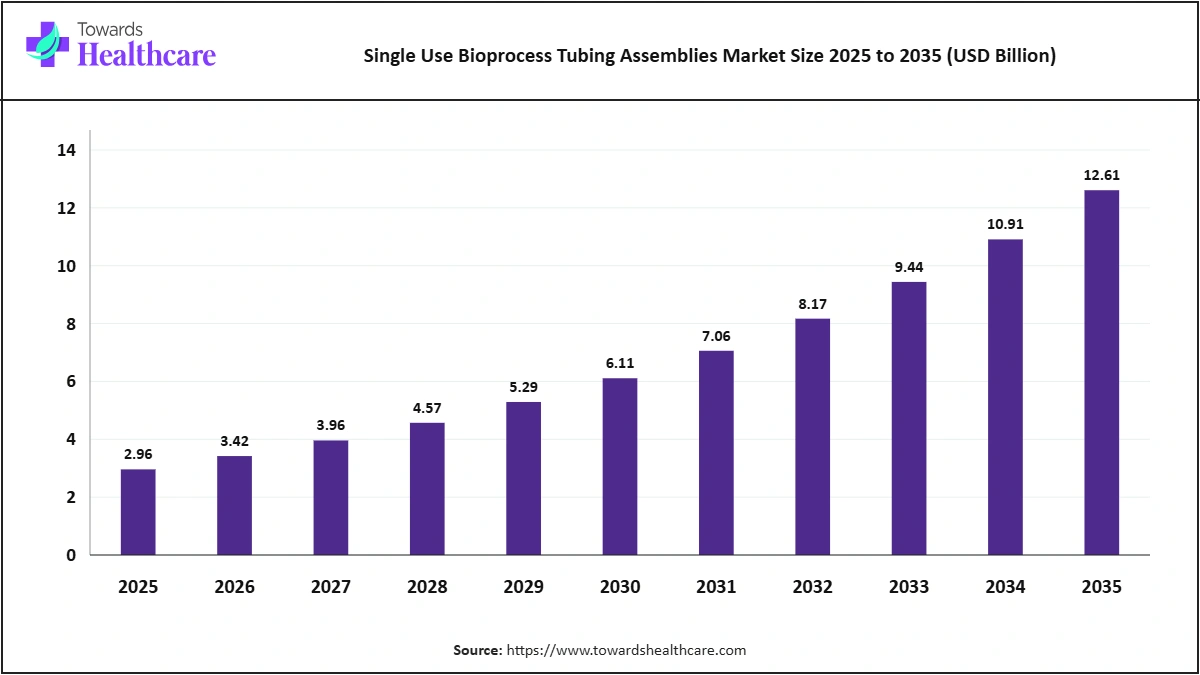
The market is projected to grow from USD 2.96 billion in 2025 to USD 12.61 billion by 2035 because single-use systems are now standard in biologics and cell therapy plants, and every batch uses new tubing sets. Biologics growth, cell and gene therapy, CDMO outsourcing, closed processing, and new Asian capacity support very strong growth. The market is expected to reach USD 6.11 billion by 2030 and sustain a CAGR of 15.60% from 2026 to 2035. Tubing assemblies carry cell culture media and buffers and are essential in cell therapy and cell-based vaccine production.
Analyst View: We built the estimate from biomanufacturing batches and single-use tubing set use per batch, multiplied by average set prices, cross-checked against published single-use assembly estimates and supplier revenues. Tubing assemblies were separated using product mix data.
Driver: Growth in biologics output and cell and gene therapy expansion drives market demand. Single-use tubing assemblies reduce cleaning requirements between production batches. CDMOs are expanding their bioprocessing capacity. Closed-system design minimizes the risk of contamination and improves process safety.
Restraint: Supply chain disruptions can delay the availability of equipment. Single-use systems result in significant post-use plastic waste generation. There are significant concerns regarding leachables, which limit adoption because of potential product contamination risks.
Opportunity: The demand for custom-designed manifolds is increasing as manufacturers increasingly prefer tubing assemblies designed to serve specific bioprocessing requirements. Expansion of biopharmaceutical manufacturing facilities in Asia Pacific drives market demand. Development of recyclable materials facilitates improvement of sustainability of single-use systems. Rising investment in fill-finish facilities fuels demand for integrated single-use tubing assemblies. Establishment of local assembly hubs helps to improve supply reliability and support regional customer requirements.
| Driver | Impact | ≈ CAGR Contribution | Time Horizon | Key Regions |
| Biologics output grows | High | +6.09 pp | Short to long term | Global, strongest in North America |
| Cell and gene therapy expands | Medium | +5.14 pp | Medium to long term | Global, fastest uptake in Asia Pacific |
| Single-use cuts cleaning | Medium | +4.38 pp | Short to medium term | Global |
| CDMOs scale | Low | +3.43 pp | Long term | Developed and emerging markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Taken together, these drivers add about 19.03 percentage points to the annual growth of the market, with biologics output growth having the largest effect. Their influence is strongest in North America, while uptake grows fastest in Asia Pacific.
| Restraint | Impact | ≈ Negative CAGR Contribution | Time Horizon | Key Regions |
| Supply bottlenecks | High | -1.54 pp | Short to medium term | Global |
| Plastic waste | High | -1.13 pp | Medium term | Price-sensitive and emerging markets |
| Validation costs | Medium | -0.76 pp | Short term | North America and other mature markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
These restraints are expected to reduce annual growth of the market by about 3.43 percentage points, led by supply bottlenecks. Their effect eases over the forecast period as suppliers, buyers and regulators adapt, leaving a net CAGR of 15.60% from 2026 to 2035.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
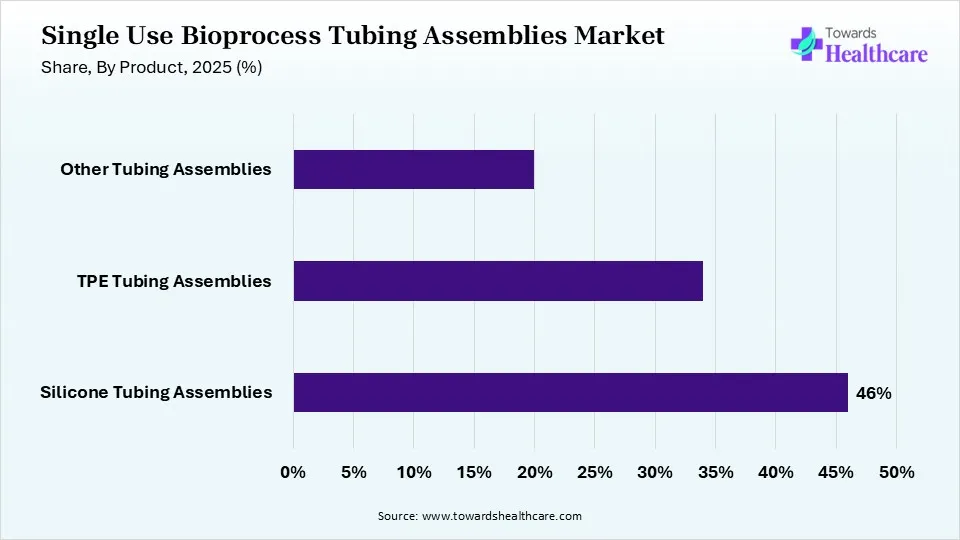
Silicone Tubing Assemblies held a market share of 46.00% in 2025 and are projected to expand at a CAGR of 14.66% during the forecast period. The leadership of silicone tubing assemblies is due to silicone being flexible, heat-resistant, and well documented for biologics production. The silicone tubing assemblies segment is expected to grow slower than the overall market over the forecast period.
TPE tubing assemblies grow fastest because TPE can be welded and sealed, supporting closed, aseptic connections. The TPE Tubing Assemblies segment is expected to grow faster than the overall market over the forecast period.
Other assemblies use PVC, PharMed and specialty tubing for pumps and transfers. The other tubing assemblies segment is expected to grow slower than the overall market over the forecast period.
Other Tubing Assemblies holds the smallest share today and serves more specialized needs within the market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
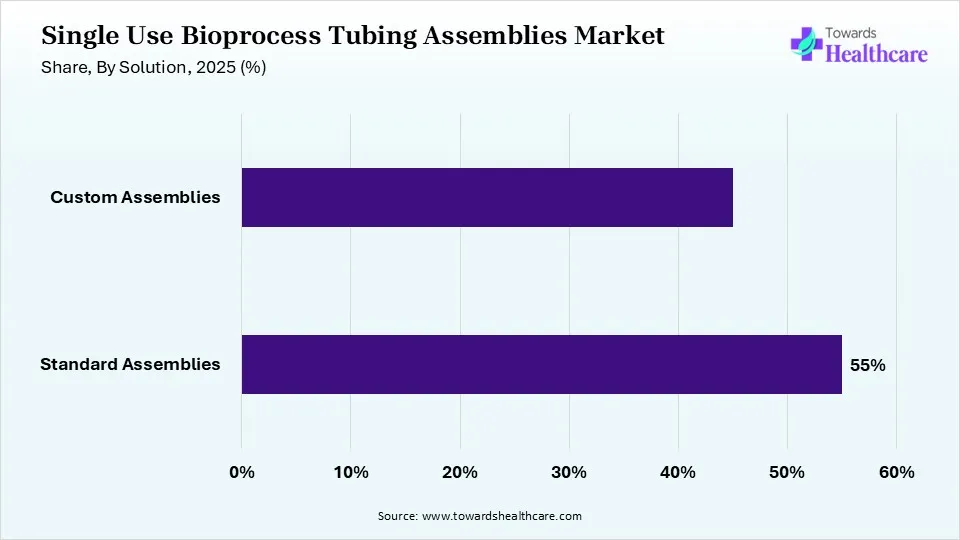
Standard Assemblies held 55.00% of the market in 2025 and are projected to expand at a CAGR of 14.86% during the forecast period. Standard assemblies hold the leading position because they are faster to source and validate. The standard assemblies segment is expected to grow slower than the overall market over the forecast period.
Custom assemblies are growing fastest as drug makers design process-specific manifolds for cell and gene therapy. The custom assemblies segment is expected to grow faster than the overall market over the forecast period.
Although Custom Assemblies starts from the smallest base, their faster growth shows how demand is shifting within the market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
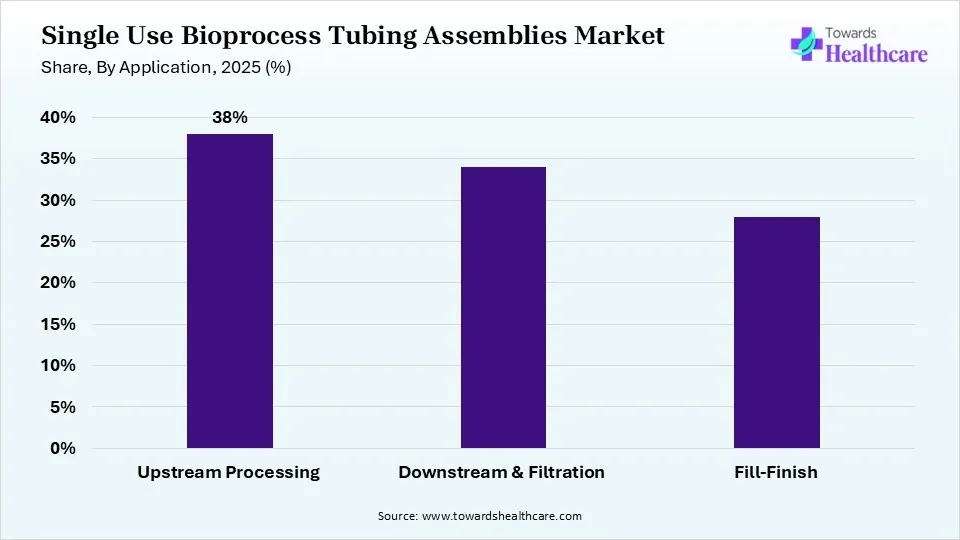
Upstream Processing held a 38.00% share in 2025 and is projected to expand at a CAGR of 14.91% from 2026 to 2035. Upstream processing uses tubing for media feeds, bioreactor transfers, and sampling. The upstream processing segment is expected to grow at a slower rate than the overall market over the forecast period.
Downstream purification and filtration use assemblies for chromatography and filtration steps. The downstream & filtration segment is expected to grow broadly in line with the overall market over the forecast period.
Fill-finish grows fastest as closed single-use filling lines spread. The fill-finish segment is expected to grow faster than the overall market over the forecast period.
Although Fill-Finish starts from the smallest base, its faster growth shows how demand is shifting within the market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
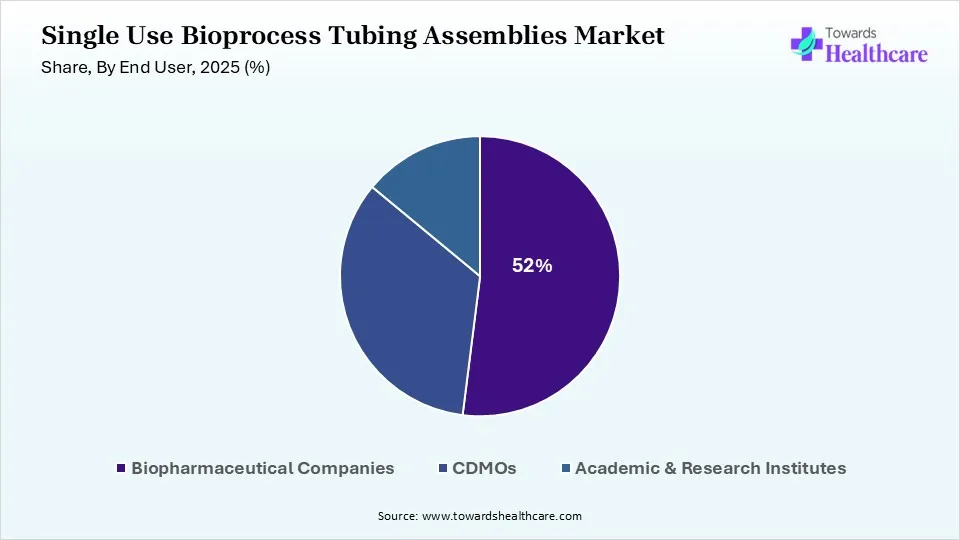
Biopharmaceutical Companies held a 52.00% share in 2025 and are projected to expand at a CAGR of 14.87% from 2026 to 2035. Biopharmaceutical companies are the largest users. The biopharmaceutical companies segment is expected to grow slower than the overall market over the forecast period.
CDMOs grow fastest as outsourcing of biologics and cell therapy rises. The CDMOs segment is expected to grow faster than the overall market over the forecast period.
Academic and research institutes use assemblies in pilot plants. The academic & research institutes segment is expected to grow slower than the overall market over the forecast period.
Academic & Research Institutes hold the smallest share today and serve more specialized needs within the single-use bioprocess tubing assemblies market.
Analyst View: Segment shares were allocated from demand, product portfolios, and pricing in each category. Silicone Tubing Assemblies, Standard Assemblies, Upstream Processing, and Biopharmaceutical Companies lead their categories because they meet the core needs of today's buyers. We expect TPE Tubing Assemblies, Custom Assemblies, Fill-Finish and CDMOs to gain share as newer technologies, users and applications grow faster.
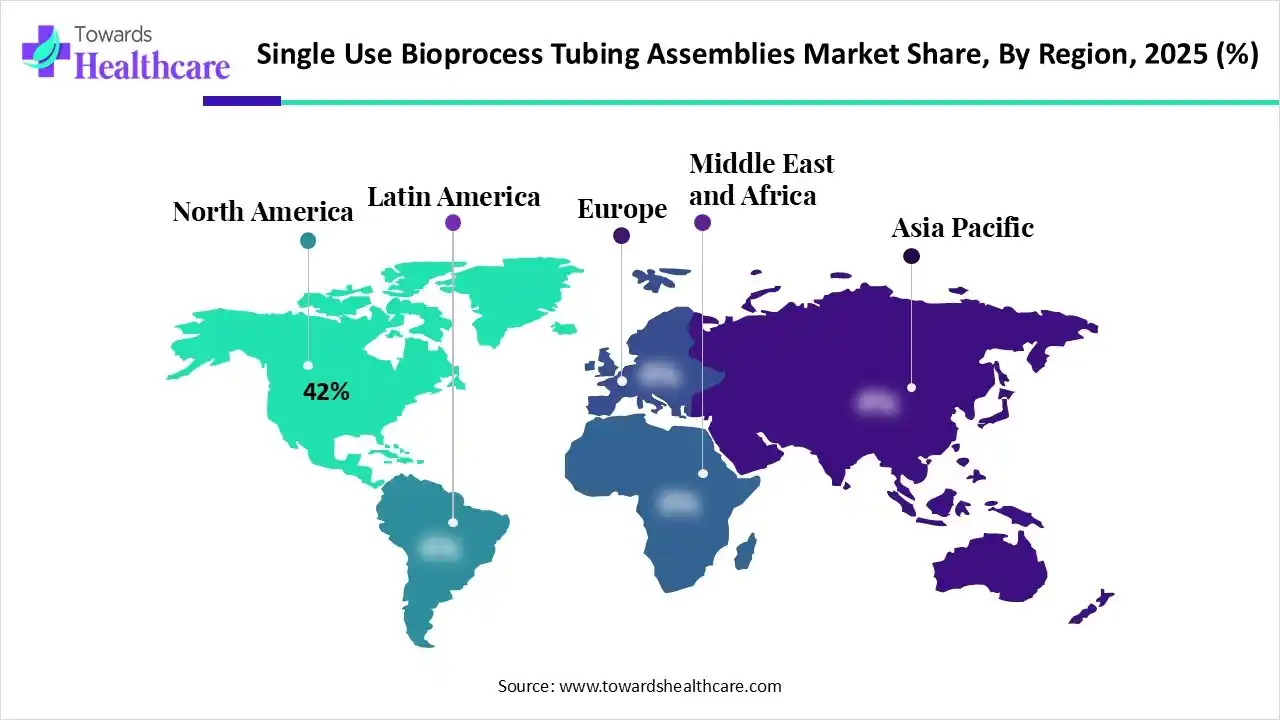
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
North America held a market share of 42.00% in 2025 and is projected to expand at a CAGR of 15.10% from 2026 to 2035. The leadership of this segment is because of large biologics, vaccine and cell and gene therapy manufacturing and suppliers such as Saint-Gobain, Avantor and Repligen. North America is expected to grow at a slower rate than the overall market between 2026 and 2035.
Europe The region benefits from strong biologics manufacturing in Germany, Ireland, and Switzerland. Europe is expected to grow broadly in line with the overall market between 2026 and 2035.
Asia Pacific Asia Pacific grows fastest with new biologics capacity in China, South Korea, and India. Asia Pacific is expected to grow faster than the overall market between 2026 and 2035.
Latin America is supported by vaccine production in Brazil. Latin America is expected to grow broadly in line with the overall market between 2026 and 2035.
Middle East & Africa The regional market is supported by new biomanufacturing in Saudi Arabia. Middle East & Africa is expected to grow broadly in line with the overall market between 2026 and 2035.
Analyst View: Regional shares were built from demand, installed base, spending, and supplier presence in each region. North America leads because of its mature demand base and strong suppliers. We assign Asia Pacific the highest growth premium because investment, adoption, and capacity are expanding fastest there.
| Rank | Company Name | 2025 Share (%) | Key Products / Business | Headquarters |
| 1 | Sartorius | 13.51% | Single-use tubing assemblies and manifolds | Germany |
| 2 | Thermo Fisher Scientific | 12.16% | BioProcess Containers and assemblies | United States |
| 3 | Cytiva | 11.15% | Single-use fluid management assemblies | United States |
| 4 | Saint-Gobain Life Sciences | 9.46% | C-Flex and Sani-Tech tubing assemblies | France |
| 5 | Avantor | 7.43% | Masterflex tubing and single-use assemblies | United States |
| 6 | Merck KGaA (MilliporeSigma) | 6.76% | Mobius single-use assemblies | Germany |
| 7 | Repligen | 4.05% | Single-use flow paths and tubing | United States |
| 8 | Parker Hannifin | 2.70% | Single-use bioprocess assemblies | United States |
| 9 | Entegris | 2.36% | Aramus single-use assemblies | United States |
| 10 | Foxx Life Sciences | 1.35% | Custom single-use assemblies | United States |
Note: Company shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Sartorius led the market with 13.51% of revenue in 2025, followed by Thermo Fisher Scientific at 12.16% share and Cytiva at 11.15% share. Sartorius leads with single-use tubing assemblies and manifolds, Thermo Fisher Scientific competes with bioProcess Containers and assemblies, and Cytiva offers single-use fluid management assemblies. Saint-Gobain Life Sciences, Avantor, Merck KGaA (MilliporeSigma), Repligen, Parker Hannifin, Entegris and Foxx Life Sciences compete through c-Flex and Sani-Tech tubing assemblies, masterflex tubing and single-use assemblies, mobius single-use assemblies, single-use flow paths and tubing, single-use bioprocess assemblies, Aramus single-use assemblies and custom single-use assemblies. The top 10 companies accounted for a 70.95% share in 2025, while the remaining 29.05% was shared among many custom assemblers and component makers. The market is moderately concentrated, and competition revolves around extractables and leachables data, sterility assurance, custom design speed, supply security, connector compatibility, and price.
Sartorius: Sartorius is headquartered in Germany. It held a 13.51% share of the market in 2025. Its offering centres on Single-use tubing assemblies and manifolds. In the Precedence Research Companies Quadrant it is positioned as a Leader.
Thermo Fisher Scientific: Thermo Fisher Scientific has its global headquarters in the United States. It held a 12.16% share in 2025. Its offering revolves around BioProcess Containers and assemblies. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Cytiva: Cytiva, part of Danaher Corporation, is headquartered in the United States. It held an 11.15% share of the single use bioprocess tubing assemblies market in 2025. It has a portfolio of Single-use fluid management assemblies. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Saint-Gobain Life Sciences: Saint-Gobain Life Sciences, part of Compagnie de Saint-Gobain S.A., is headquartered in France. It held a 9.46% share of the single use bioprocess tubing assemblies market in 2025. Its offering centres on C-Flex and Sani-Tech tubing assemblies. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Avantor: Avantor is headquartered in the United States. It held 7.43% of revenue of the market in 2025. Its offering revolves around Masterflex tubing and single-use assemblies. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Merck KGaA (MilliporeSigma): Merck KGaA (MilliporeSigma) is headquartered in Germany. It held a 6.76% share in 2025. Its offering centres on Mobius single-use assemblies. It is positioned as a leader in the Towards Healthcare companies quadrant.
Repligen: Repligen is headquartered in the United States. It held a 4.05% share of the single use bioprocess tubing assemblies market in 2025. It has a portfolio of Single-use flow paths and tubing. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
Parker Hannifin: Parker Hannifin, part of Parker-Hannifin Corporation, is headquartered in the United States. It held an estimated 2.70% share of the single use bioprocess tubing assemblies market in 2025. Its offering centres on Single-use bioprocess assemblies. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
Entegris: Entegris is headquartered in the United States. It held 2.36% of revenue in 2025. Its offering centres on Aramus single-use assemblies. It is positioned as a innovator in the Towards Healthcare companies quadrant.
Foxx Life Sciences: Foxx Life Sciences has its corporate headquarters in the United States. It held a 1.35% share of the market in 2025. Its offering centres on Custom single-use assemblies. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
The single use bioprocess tubing assemblies ecosystem links tubing & component makers, assembly suppliers, sterilization providers, users and regulators, with each stage adding value before products reach end users.
| Ecosystem Stage | Role in the Market | Key Companies |
| Tubing & Component Makers | Make tubing, connectors and fittings | Saint-Gobain, Avantor, CPC |
| Assembly Suppliers | Build and sterilise assemblies | Sartorius, Thermo Fisher, Cytiva, Merck KGaA |
| Sterilisation Providers | Gamma and X-ray sterilisation | Steris, Sotera Health |
| Users | Run biomanufacturing | Biopharma, CDMOs, research institutes |
| Regulators | Set GMP and material rules | FDA, EMA, USP |
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Tubing & Component Makers: Make tubing, connectors and fittings. Key participants include Saint-Gobain, Avantor, CPC.
Assembly Suppliers: Build and sterilise assemblies. Key participants include Sartorius, Thermo Fisher, Cytiva, Merck KGaA.
Sterilisation Providers: Gamma and X-ray sterilisation. Key participants include Steris, Sotera Health.
Users: Run biomanufacturing. Key participants include Biopharma, CDMOs, research institutes.
Regulators: Set GMP and material rules. Key participants include FDA, EMA, USP.
Value in the market flows from upstream material and technology suppliers to manufacturers and service providers, then through distribution partners to end users. Companies that integrate several stages or build long-term relationships with end users capture a larger share of this value.
The Towards Healthcare Companies Quadrant positions key participants in the single use bioprocess tubing assemblies market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 share of the single use bioprocess tubing assemblies market and our assessment of its product innovation, portfolio breadth and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Leaders: Sartorius, Thermo Fisher Scientific, Cytiva, Saint-Gobain Life Sciences, Avantor and Merck KGaA (MilliporeSigma) combine high market share with broad portfolios and strong innovation.
Innovators: Repligen, Parker Hannifin, Entegris and Foxx Life Sciences bring newer technologies and specialised products.
By Product
By Solution
By Application
By End User
By Region
The market is defined as pre-assembled, pre-sterilized single-use tubing sets used to transfer fluids in biopharmaceutical manufacturing, including silicone, thermoplastic elastomer (TPE) and other tubing with connectors, fittings, manifolds and bag interfaces, in standard and custom assemblies, for upstream processing, downstream purification, filtration and fill-finish, used by biopharmaceutical companies, contract development and manufacturing organisations and academic and research institutes. The 2025 base year was built bottom-up from demand volumes and average prices by product, solution, application and end user and region, and checked top-down against the market-specific revenues of leading companies and published estimates.
Segment, regional and company values were allocated from product, solution, application and end user and region demand. Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View: The market is set for steady expansion as biologics growth and related demand keep growing. Our estimate links value to underlying demand, installed base and pricing, so the forecast follows real adoption rather than headline hype. The main upside comes from custom assemblies and Asia Pacific capacity, while the main risks are supply bottlenecks and plastic waste.