The U.S. plasmid DNA contract manufacturing market is projected to increase from USD 214.00 million in 2025 to USD 1,281.52 million by 2035, driven by growing demand from cell and gene therapy and mRNA developers that rely on specialist CDMOs for plasmid production. Expanding gene therapy pipelines, mRNA development, increased outsourcing, clinical progress, and regulatory approvals are expected to support this growth. The market is forecast to reach USD 523.68 million by 2030, registering a CAGR of 19.60% from 2026 to 2035. Plasmids play an essential role in the development and production of cell therapies and genomics-based medicines.
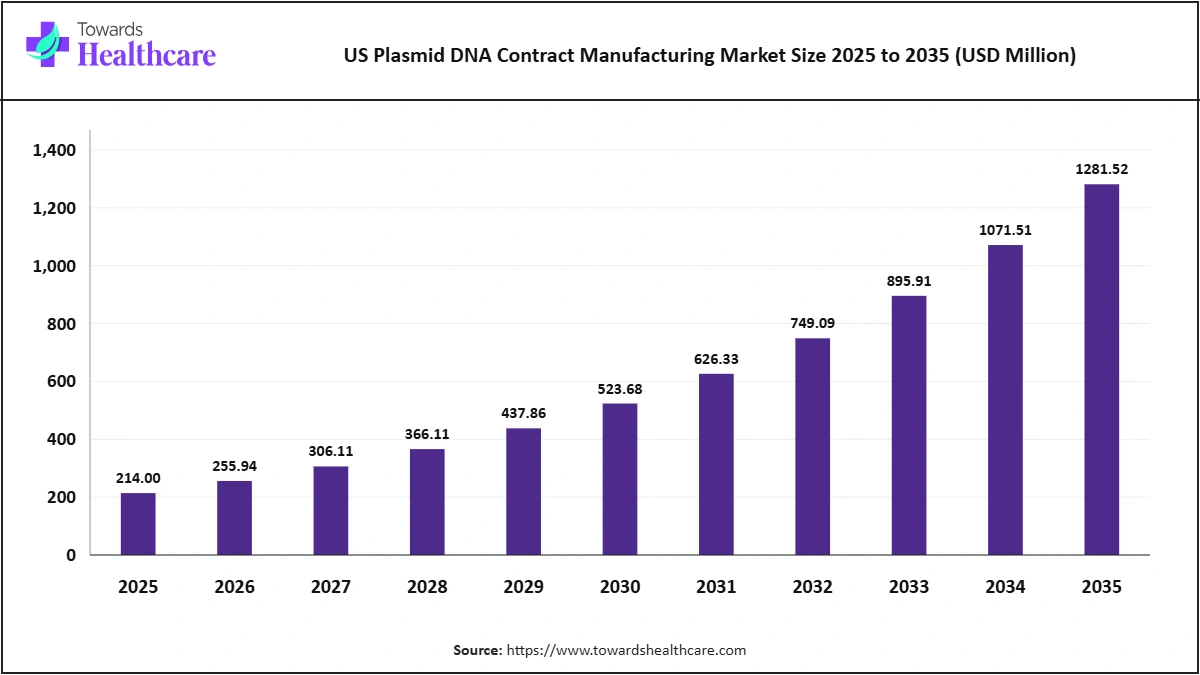
Analyst View: The market estimate was developed using U.S. plasmid production volumes by grade and their corresponding prices. It was then cross-checked against CDMO revenues and published estimates of approximately USD 146 million in 2023, with annual growth of around 19%. Based on these comparisons, our 2025 base-year estimate is slightly above the highest credible published figure.
Driver: Growth in gene therapy pipelines, expanding mRNA applications, increased outsourcing, advancing clinical programmes, and a rise in regulatory approvals are supporting market demand.
Restraint: Market growth may be constrained by fluctuations in biotech funding, high GMP manufacturing costs, the risk of excess production capacity, and competition from synthetic DNA alternatives.
Opportunity: Key opportunities include growing demand for mRNA templates, integrated manufacturing services, expanding capacity in Texas and the Southeast, faster access to GMP production slots, and the development of in vivo gene-editing therapies.
Market Drivers - Impact & CAGR Contribution (2026-2035)
| Driver | Impact | ≈ CAGR Contribution | Time Horizon | Key Regions |
| Gene therapy pipelines grow | High | +7.65 pp | Short to long term | U.S.-wide, strongest in Northeast |
| mRNA expands | Medium | +6.46 pp | Medium to long term | U.S.-wide, fastest uptake in South |
| Outsourcing rises | Medium | +5.50 pp | Short to medium term | U.S.-wide |
| Clinical programmes advance | Low | +4.30 pp | Long term | Northeast and South |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Taken together, these drivers add about 23.91 percentage points to the annual growth of the U.S. plasmid DNA contract manufacturing market, with gene therapy pipelines grow having the largest effect. Their influence is strongest in the Northeast, while uptake grows fastest in South.
Market Restraints - Impact & Negative CAGR Contribution (2026-2035)
| Restraint | Impact | ≈ Negative CAGR Contribution | Time Horizon | Key Regions |
| Biotech funding swings | High | -1.94 pp | Short to medium term | U.S.-wide |
| GMP costs | High | -1.42 pp | Medium term | Smaller and price-sensitive markets |
| Capacity gluts | Medium | -0.95 pp | Short term | Northeast and other mature markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
These restraints are expected to reduce annual growth of the U.S. plasmid DNA contract manufacturing market by about 4.31 percentage points, led by biotech funding swings. Their effect eases over the forecast period as suppliers, buyers, and regulators adapt, leaving a net CAGR of 19.60% from 2026 to 2035.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
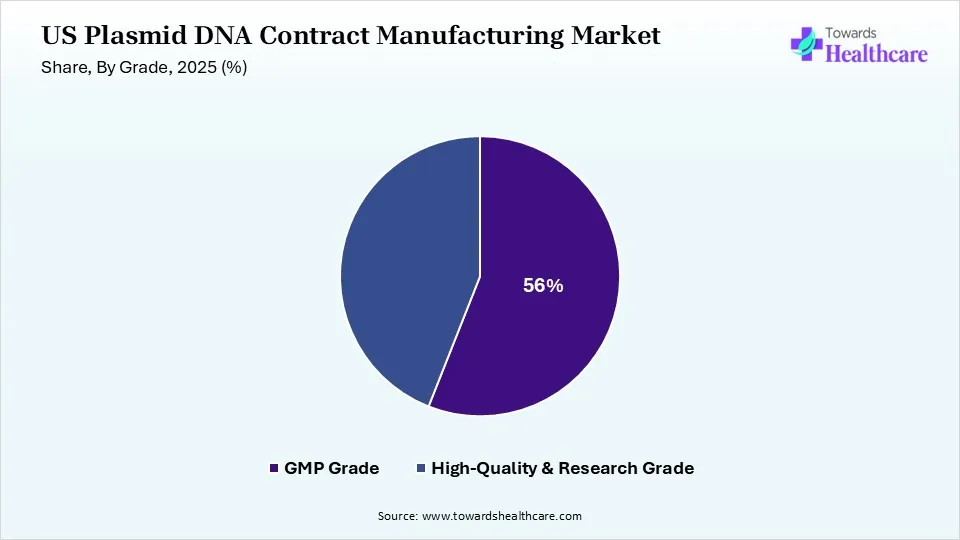
GMP Grade: This segment accounted for 56.00% of the U.S. plasmid DNA contract manufacturing market in 2025 and is projected to expand at a CAGR of 20.03% from 2026 to 2035. GMP grade leads because clinical and commercial therapies need plasmids made under strict quality systems. The GMP Grade segment is expected to grow faster than the overall market over the forecast period.
These plasmids support early-stage research and development activities. However, the segment is expected to grow at a slower pace than the overall market over the forecast period.
Strengthening its lead in the U.S. plasmid DNA contract manufacturing market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
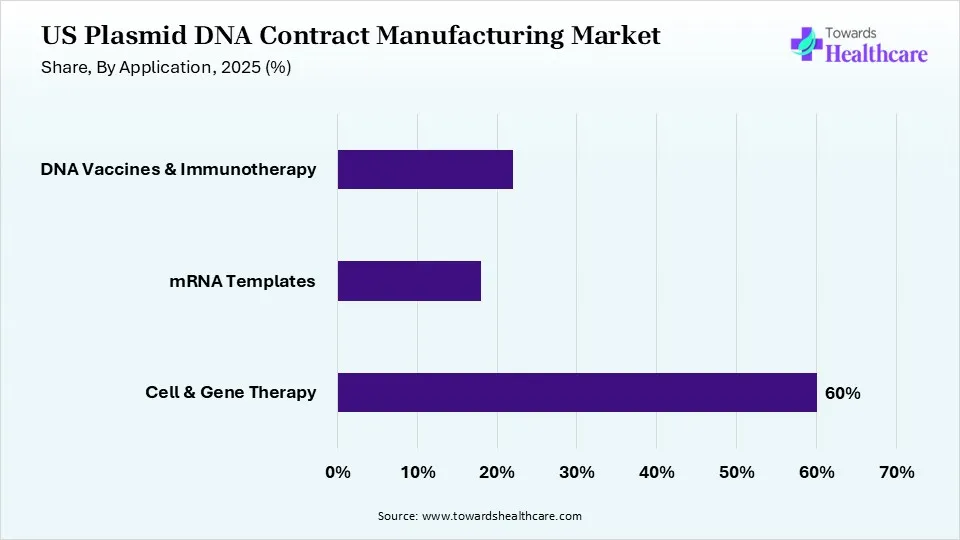
Cell & Gene Therapy: This segment valued for 60.00% of the U.S. plasmid DNA contract manufacturing market in 2025 and is projected to expand at a CAGR of 18.84% from 2026 to 2035. Cell and gene therapy leads because plasmids are used to make viral vectors. The cell & gene therapy segment is expected to grow slower than the overall market over the forecast period.
mRNA templates grow fastest as mRNA therapeutics expand. The mRNA templates segment is expected to grow faster than the overall market over the forecast period.
DNA vaccines and immunotherapy use plasmids directly. The DNA Vaccines & Immunotherapy segment is expected to grow slower than the overall market over the forecast period.
Although mRNA Templates starts from the smallest base, its faster growth shows how demand is shifting within the U.S. plasmid DNA contract manufacturing market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
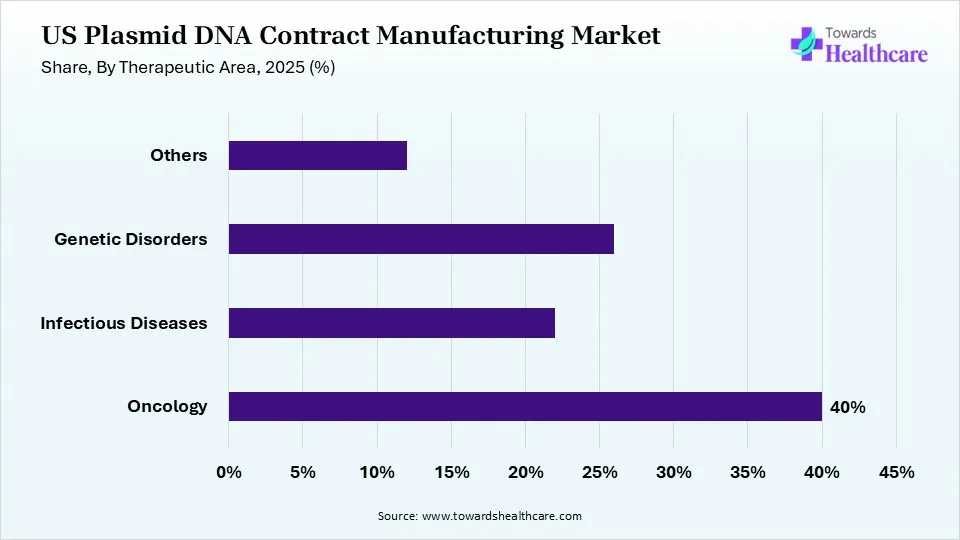
Oncology: This segment accounted for 40.00% of the U.S. plasmid DNA contract manufacturing market in 2025 and is projected to expand at a CAGR of 18.89% from 2026 to 2035. Oncology leads. The oncology segment is expected to grow slower than the overall market over the forecast period.
Infectious diseases grow fastest. The infectious diseases segment is expected to grow faster than the overall market over the forecast period.
Genetic disorders use gene therapies. The genetic disorders segment is expected to grow slower than the overall market over the forecast period.
Others complete demand. The others segment is expected to grow slower than the overall market over the forecast period.
Others hold the smallest share today and serve more specialised needs within the U.S. plasmid DNA contract manufacturing market.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
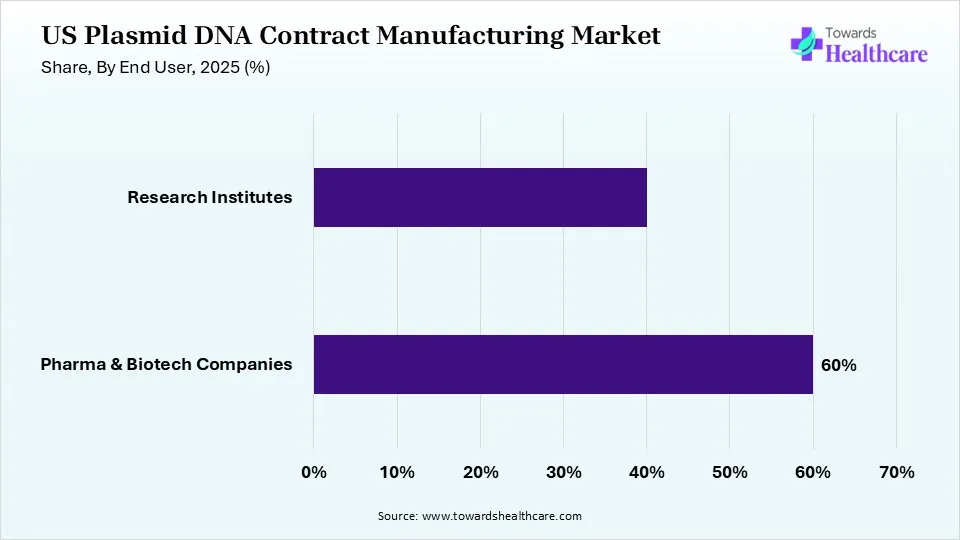
Pharma & Biotech Companies: This segment accounted for 60.00% of the U.S. plasmid DNA contract manufacturing market in 2025 and is projected to expand at a CAGR of 18.94% from 2026 to 2035. Pharmaceutical and biotechnology companies lead. The pharma & biotech companies segment is expected to grow slower than the overall market over the forecast period.
Research institutes grow fastest. The research institutes segment is expected to grow faster than the overall market over the forecast period.
Although Research Institutes start from the smallest base, its faster growth shows how demand is shifting within the U.S. plasmid DNA contract manufacturing market.
Analyst View: Segment shares were allocated from demand, product portfolios, and pricing in each category. GMP Grade, Cell & Gene Therapy, Oncology, and Pharma & Biotech Companies lead their categories because they meet today's buyers' core needs. We expect mRNA Templates, Infectious Diseases and Research Institutes to gain share as newer technologies, users and applications grow faster.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Northeast: This region accounted for 36.00% of the U.S. plasmid DNA contract manufacturing market in 2025 and is projected to expand at a CAGR of 19.07% from 2026 to 2035. The Northeast leads because of Boston-area gene therapy developers. Northeast is expected to grow slower than the overall market between 2026 and 2035.
Midwest: The Midwest has major plasmid producers, including Aldevron in North Dakota. Midwest is expected to grow broadly in line with the overall market between 2026 and 2035.
South: The South grows fastest with new GMP plasmid capacity in Texas and North Carolina. South is expected to grow faster than the overall market between 2026 and 2035.
West: The West has biotech clusters in California. West is expected to grow broadly in line with the overall market between 2026 and 2035.
Analyst View: Regional shares were built from demand, installed base, spending and supplier presence in each region. Northeast leads because of its mature demand base and strong suppliers. We assign South the highest growth premium because investment, adoption and capacity are expanding fastest there.
| Rank | Company Name | 2025 Share (%) | Key Products / Business | Headquarters |
| 1 | Aldevron | 28.97% | GMP and research plasmid DNA | United States |
| 2 | Charles River Laboratories | 13.08% | GMP plasmid manufacturing | United States |
| 3 | VGXI | 10.28% | GMP plasmid DNA | United States |
| 4 | Catalent | 7.48% | Plasmid and gene therapy manufacturing | United States |
| 5 | Thermo Fisher Scientific | 7.01% | Plasmid and viral vector services | United States |
| 6 | AGC Biologics | 4.67% | Plasmid DNA CDMO | United States |
| 7 | TriLink BioTechnologies | 3.74% | mRNA templates and plasmids | United States |
| 8 | Akron Biotech | 2.80% | GMP materials and plasmids | United States |
| 9 | Andelyn Biosciences | 2.34% | Plasmid and gene therapy CDMO | United States |
| 10 | Bionova Scientific | 1.87% | Plasmid DNA CDMO | United States |
Note: Company shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Aldevron led the U.S. plasmid DNA contract manufacturing market with an estimated 28.97% share of 2025 revenue, followed by Charles River Laboratories at 13.08% share and VGXI at 10.28% share. Aldevron leads with GMP and research plasmid DNA, Charles River Laboratories competes with GMP plasmid manufacturing, and VGXI offers GMP plasmid DNA. Catalent, Thermo Fisher Scientific, AGC Biologics, TriLink BioTechnologies, Akron Biotech, Andelyn Biosciences, and Bionova Scientific compete through plasmid and gene therapy manufacturing, plasmid and viral vector services, plasmid DNA CDMO, mRNA templates and plasmids, GMP materials and plasmids, plasmid and gene therapy CDMO, and plasmid DNA CDMO.
The top 10 companies accounted for an estimated 82.24% of 2025 revenue, while the remaining 17.76% was shared among smaller CDMOs and academic GMP facilities. The U.S. plasmid DNA contract manufacturing market is concentrated, with Aldevron the leader, and competition centres on GMP capacity, timelines, quality track record, scale, regulatory support and price.
Aldevron: Aldevron, part of Danaher Corporation, is headquartered in the United States. It held an estimated 28.97% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on GMP and research plasmid DNA. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Charles River Laboratories: Charles River Laboratories is headquartered in the United States. It held an estimated 13.08% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on GMP plasmid manufacturing. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
VGXI: VGXI, part of GeneOne Life Science, is headquartered in the United States. It held an estimated 10.28% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on GMP plasmid DNA. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Catalent: Catalent, part of Novo Holdings, is headquartered in the United States. It held an estimated 7.48% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on Plasmid and gene therapy manufacturing. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
Thermo Fisher Scientific: Thermo Fisher Scientific is headquartered in the United States. It held an estimated 7.01% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on Plasmid and viral vector services. In the Towards Healthcare Companies Quadrant it is positioned as a Leader.
AGC Biologics: AGC Biologics is headquartered in the United States. It held an estimated 4.67% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on Plasmid DNA CDMO. In the Precedence Research Companies Quadrant it is positioned as a Leader.
Andelyn Biosciences: Andelyn Biosciences is headquartered in the United States. It held an estimated 2.34% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on Plasmid and gene therapy CDMO. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
TriLink BioTechnologies: TriLink BioTechnologies, part of Maravai LifeSciences, is headquartered in the United States. It held an estimated 3.74% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on mRNA templates and plasmids. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
Akron Biotech: Akron Biotech is headquartered in the United States. It held an estimated 2.80% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on GMP materials and plasmids. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
Bionova Scientific: Bionova Scientific, part of Asahi Kasei Corporation, is headquartered in the United States. It held an estimated 1.87% share of the U.S. plasmid DNA contract manufacturing market in 2025. Its offering centres on Plasmid DNA CDMO. In the Towards Healthcare Companies Quadrant it is positioned as an Innovator.
The U.S. plasmid DNA contract manufacturing ecosystem links raw material suppliers, plasmid cdmos, vector & mrna makers, developers and regulators, with each stage adding value before products reach end users.
| Ecosystem Stage | Role in the Market | Key Companies |
| Raw Material Suppliers | Supply media, enzymes and resins | Life science suppliers |
| Plasmid CDMOs | Manufacture plasmids | Aldevron, Charles River, VGXI |
| Vector & mRNA Makers | Use plasmids downstream | Gene therapy and mRNA developers |
| Developers | Commission plasmids | Biotech and pharma |
| Regulators | Set GMP rules | FDA |
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Raw Material Suppliers: Supply media, enzymes, and resins. Key participants include Life science suppliers.
Plasmid CDMOs: Manufacture plasmids. Key participants include Aldevron, Charles River, VGXI.
Vector & mRNA Makers: Use plasmids downstream. Key participants include Gene therapy and mRNA developers.
Developers: Commission plasmids. Key participants include Biotech and pharma.
Regulators: Set GMP rules. Key participants include the FDA.
Value in the U.S. plasmid DNA contract manufacturing market flows from upstream material and technology suppliers to manufacturers and service providers, then through distribution partners to end users. Companies that integrate several stages or build long-term relationships with end users capture a larger share of this value.
The Towards Healthcare Companies Quadrant positions key participants in the U.S. plasmid DNA contract manufacturing market by market strength, reflecting revenue scale, market share, and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity, and partnerships. Positions reflect each company's estimated 2025 share of the U.S. plasmid DNA contract manufacturing market and our assessment of its product innovation, portfolio breadth and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Towards Healthcare database and Towards Healthcare analysts.
Leaders: Aldevron, Charles River Laboratories, VGXI, Catalent, Thermo Fisher Scientific and AGC Biologics combine high market share with broad portfolios and strong innovation.
Innovators: TriLink BioTechnologies, Akron Biotech, Andelyn Biosciences and Bionova Scientific bring newer technologies and specialised products.
By Grade
By Application
By Therapeutic Area
By End User
By Region
The U.S. plasmid DNA contract manufacturing market was defined as contract manufacturing of plasmid DNA in the United States, including research-grade, high-quality, and GMP-grade plasmids, process development and analytical services, for cell and gene therapy, mRNA templates, DNA vaccines and immunotherapy, in oncology, infectious disease, genetic disorders and other areas, for pharmaceutical and biotechnology companies and research institutes. The 2025 base year was built bottom-up from demand volumes and average prices by grade, application, therapeutic area, end user and region, and checked top-down against the market-specific revenues of leading companies and published estimates. Segment, regional and company values were allocated from grade, application, therapeutic area and end user and region demand.
Key estimates were verified by cross-checking company disclosures, regulatory and industry data, and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional, and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
The U.S. plasmid DNA contract manufacturing market is set for steady expansion as gene therapy pipelines and related demand keep growing. Our estimate links value to underlying demand, installed base, and pricing, so the forecast follows real adoption rather than headline hype. The main upside comes from mRNA templates and integrated services, while the main risks are biotech funding swings.
1.3.1 Market Value (USD) and Annual Growth
1.3.2 Historical Market Analysis
1.3.3 Market Growth Analysis and CAGR 2026–2035
2.2.1 Gene therapy pipelines grow
2.2.2 mRNA expands
2.2.3 Outsourcing rises
2.2.4 Clinical programmes advance
2.4.1 Biotech funding swings
2.4.2 GMP costs
2.4.3 Capacity gluts
2.4.4 Synthetic DNA alternatives
2.7.1 mRNA templates
2.7.2 Integrated services
2.7.3 Texas and Southeast capacity
2.7.4 Faster GMP slots
2.8.1 Enzymatic and synthetic DNA alternatives
2.8.2 GMP capacity expansion
2.8.3 Faster turnaround
2.8.4 mRNA template demand
2.8.5 Integrated plasmid-to-vector services
2.8.6 High-quality grade adoption
3.1.1 GMP Grade: Market Share and CAGR
3.1.2 High-Quality & Research Grade: Market Share and CAGR
3.2.1 Cell & Gene Therapy: Market Share and CAGR
3.2.2 mRNA Templates: Market Share and CAGR
3.2.3 DNA Vaccines & Immunotherapy: Market Share and CAGR
3.3.1 Oncology: Market Share and CAGR
3.3.2 Infectious Diseases: Market Share and CAGR
3.3.3 Genetic Disorders: Market Share and CAGR
3.3.4 Others: Market Share and CAGR
3.4.1 Pharma & Biotech Companies: Market Share and CAGR
3.4.2 Research Institutes: Market Share and CAGR
4.1.1 Market Size and Forecast, 2025–2035
4.1.2 Market Share by Grade
4.1.3 Demand Drivers, Regulation and Local Competition
4.2.1 Market Size and Forecast, 2025–2035
4.2.2 Market Share by Grade
4.2.3 Demand Drivers, Regulation and Local Competition
4.3.1 Market Size and Forecast, 2025–2035
4.3.2 Market Share by Grade
4.3.3 Demand Drivers, Regulation and Local Competition
4.4.1 Market Size and Forecast, 2025–2035
4.4.2 Market Share by Grade
4.4.3 Demand Drivers, Regulation and Local Competition
5.5.1 Product Portfolio Benchmarking
5.5.2 Geographic Presence Benchmarking
5.5.3 Technology and Innovation Benchmarking
6.1.1 Instrument list price and discount analysis
6.1.2 Consumables and reagent pricing per test or sample
6.1.3 Service contract and subscription pricing
6.1.4 Academic vs. biopharma pricing tiers
7.1.1 Pharmaceutical and biotechnology companies
7.1.2 Academic and government research institutes
7.1.3 CROs, CDMOs and core facilities
7.1.4 Clinical and diagnostic laboratories
9.1.1 Key raw materials and component sourcing
9.1.2 OEM and contract manufacturing
9.1.3 Distributor and e-procurement channels
9.1.4 Cold chain and logistics requirements
11.1.1 Automation and high-throughput workflows
11.1.2 Digital, cloud and AI-enabled analysis
11.1.3 Next-generation platforms and consumables
11.1.4 Patent and IP landscape
12.1.1 Research-use-only vs. IVD regulatory pathways
12.1.2 GMP and quality standards for bioprocessing
12.1.3 Biosafety and laboratory standards
12.1.4 Data integrity and compliance requirements
17.1.1 Company Overview
17.1.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.1.3 Financial Performance and Market Share
17.1.4 Recent Developments and Strategy
17.1.5 SWOT Analysis
17.2.1 Company Overview
17.2.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.2.3 Financial Performance and Market Share
17.2.4 Recent Developments and Strategy
17.2.5 SWOT Analysis
17.3.1 Company Overview
17.3.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.3.3 Financial Performance and Market Share
17.3.4 Recent Developments and Strategy
17.3.5 SWOT Analysis
17.4.1 Company Overview
17.4.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.4.3 Financial Performance and Market Share
17.4.4 Recent Developments and Strategy
17.4.5 SWOT Analysis
17.5.1 Company Overview
17.5.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.5.3 Financial Performance and Market Share
17.5.4 Recent Developments and Strategy
17.5.5 SWOT Analysis
17.6.1 Company Overview
17.6.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.6.3 Financial Performance and Market Share
17.6.4 Recent Developments and Strategy
17.6.5 SWOT Analysis
17.7.1 Company Overview
17.7.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.7.3 Financial Performance and Market Share
17.7.4 Recent Developments and Strategy
17.7.5 SWOT Analysis
17.8.1 Company Overview
17.8.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.8.3 Financial Performance and Market Share
17.8.4 Recent Developments and Strategy
17.8.5 SWOT Analysis
17.9.1 Company Overview
17.9.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.9.3 Financial Performance and Market Share
17.9.4 Recent Developments and Strategy
17.9.5 SWOT Analysis
17.10.1 Company Overview
17.10.2 U.S. Plasmid DNA Contract Manufacturing Product Portfolio
17.10.3 Financial Performance and Market Share
17.10.4 Recent Developments and Strategy
17.10.5 SWOT Analysis