The North America laboratory chairs market is anticipated to grow from USD 236.00 million in 2025 to USD 406.96 million by 2035, supported by increasing investments in laboratory infrastructure, workplace ergonomics, and specialized research environments. New laboratory construction and renovation projects are creating consistent demand for seating designed to accommodate different laboratory workflows, including microscopy, sample preparation, biosafety cabinet operations, and prolonged bench work.
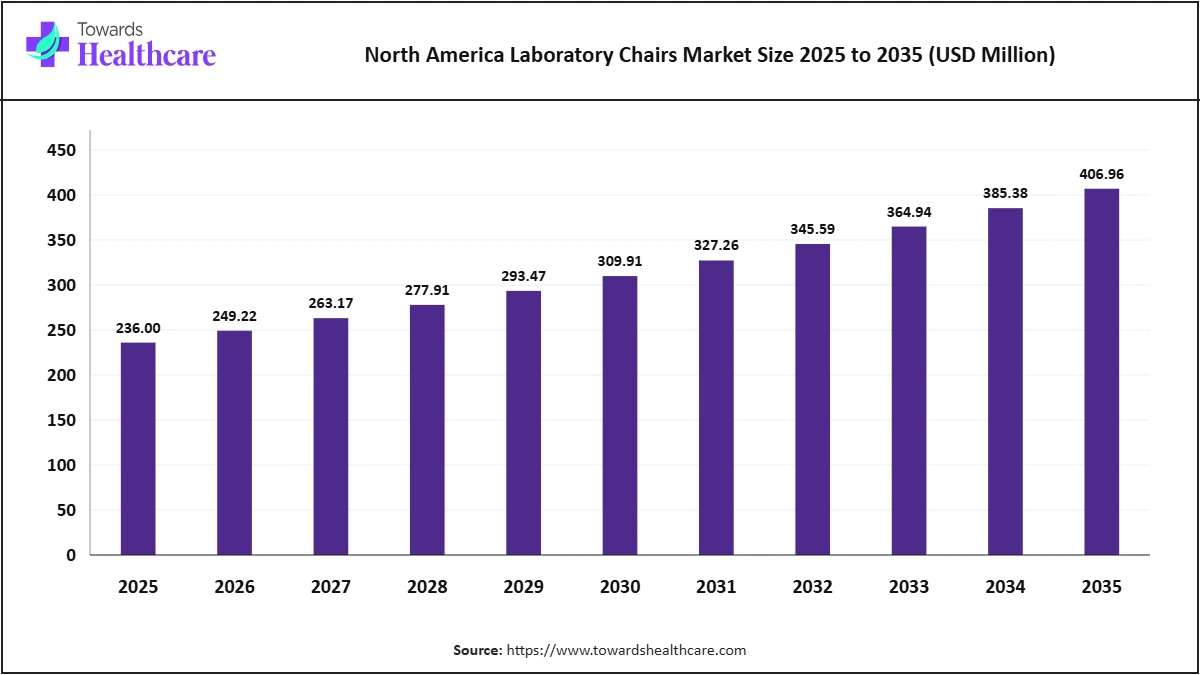
The rise in cleanroom technologies and ESD-protected environments is driving demand for specialized seating in pharmaceutical, biotechnology, and semiconductor facilities. These settings require chairs with specific materials and contamination-control features. Additionally, a focus on employee health is prompting investments in ergonomic, adjustable seating, with vinyl and polyurethane being favored for their chemical resistance and ease of maintenance. The market is expected to reach USD 309.91 million by 2030, maintaining a CAGR of 5.6% from 2026 to 2035.
Analyst View: We developed the market estimate using a bottom-up assessment of laboratory seating demand across new and renovated facilities, replacement requirements, and average chair selling prices. The analysis considers laboratory seat installations across pharmaceutical, biotechnology, academic, clinical, and industrial environments. Demand estimates were cross-checked against the product portfolios and market-specific activities of leading seating manufacturers and laboratory furniture suppliers. Published estimates for this specialized market are relatively limited, making a demand-based assessment particularly important. The forecast reflects continued laboratory infrastructure investment, increasing ergonomic requirements, and the expansion of cleanroom and ESD-protected environments.
The North America laboratory chairs market is driven by increasing laboratory construction, growing awareness of ergonomic workplace requirements, and expanding cleanroom infrastructure. Pharmaceutical and biotechnology companies are investing in research facilities, manufacturing laboratories, and quality-control environments that require specialized seating. Academic institutions and hospitals are also upgrading laboratory infrastructure to accommodate advanced research and diagnostic activities.
Ergonomic considerations are essential for laboratory professionals performing repetitive tasks and sitting for long periods. Key features like adjustable seating, lumbar support, and height customization improve comfort and efficiency. Additionally, there is a growing demand for certified cleanroom and ESD seating due to increased investments in cleanroom environments and specialized manufacturing facilities.
Budget limitations remain a challenge among smaller research laboratories, academic institutions, and independent testing facilities. Specialized laboratory chairs often involve higher initial procurement costs than conventional office seating because of their chemical-resistant materials, ergonomic features, and cleanroom or ESD requirements.
Long product life also limits replacement frequency, reducing recurring demand. Low-cost imports create pricing pressure for established manufacturers, while fluctuations in laboratory construction investment can influence purchasing activity. Furthermore, some smaller laboratories may prioritize essential equipment and infrastructure over specialized seating upgrades, limiting market penetration.
The expansion of semiconductor cleanrooms, cell therapy laboratories, and advanced biotechnology manufacturing facilities is creating new opportunities for specialized laboratory seating manufacturers. These environments require chairs that meet stringent cleanliness, contamination-control, and ESD requirements.
Mexico represents an emerging growth opportunity because of expanding pharmaceutical, clinical, and industrial laboratory infrastructure. Manufacturers can strengthen their competitive positions through bundled laboratory furniture contracts, customized seating solutions, sustainable product development, and partnerships with laboratory planners and construction companies.
The preference for integrated laboratory procurement is creating opportunities for suppliers to offer seating alongside casework, workbenches, storage systems, and other laboratory infrastructure.
| Driver | Impact | ≈ CAGR Contribution | Time Horizon | Key Regions |
| Lab construction grows | High | +2.19 pp | Short to long term | North America-wide, strongest in U.S. |
| Ergonomics matter | Medium | +1.84 pp | Medium to long term | North America-wide, fastest uptake in Mexico |
| Cleanrooms expand | Medium | +1.57 pp | Short to medium term | North America-wide |
| Staff wellbeing is a priority | Low | +1.23 pp | Long term | U.S. and Mexico |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards Healthcare analysts.
The North America laboratory chairs market is projected to grow by 6.83 percentage points annually, primarily driven by laboratory construction and increased investments in research infrastructure and clinical facilities. Growing ergonomic awareness is boosting demand for specialized seating, as employers aim to enhance laboratory working conditions. Additionally, cleanroom expansion, particularly in pharmaceutical manufacturing and semiconductor sectors, is driving demand for certified seating solutions. The U.S. shows the strongest influence from these factors, while Mexico is expected to see faster adoption due to expanding industrial infrastructure.
| Restraint | Impact | ≈ Negative CAGR Contribution | Time Horizon | Key Regions |
| Budget limits | High | -0.55 pp | Short to medium term | North America-wide |
| Long product life | High | -0.41 pp | Medium term | Smaller and price-sensitive markets |
| Low-cost imports | Medium | -0.27 pp | Short term | U.S. and other mature markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Towards Healthcare database, and Towards Healthcare analysts.
Annual growth in the North America laboratory chairs market is expected to decline by about 1.23 percentage points due to budget limitations, long product lifecycles, and competition from low-cost imports. Budget constraints heavily impact smaller research institutions and independent laboratories. Despite these challenges, expansion in laboratory infrastructure, rising ergonomic requirements, and demand for specialized seating types may lead to a projected net CAGR of 5.6% from 2026 to 2035.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
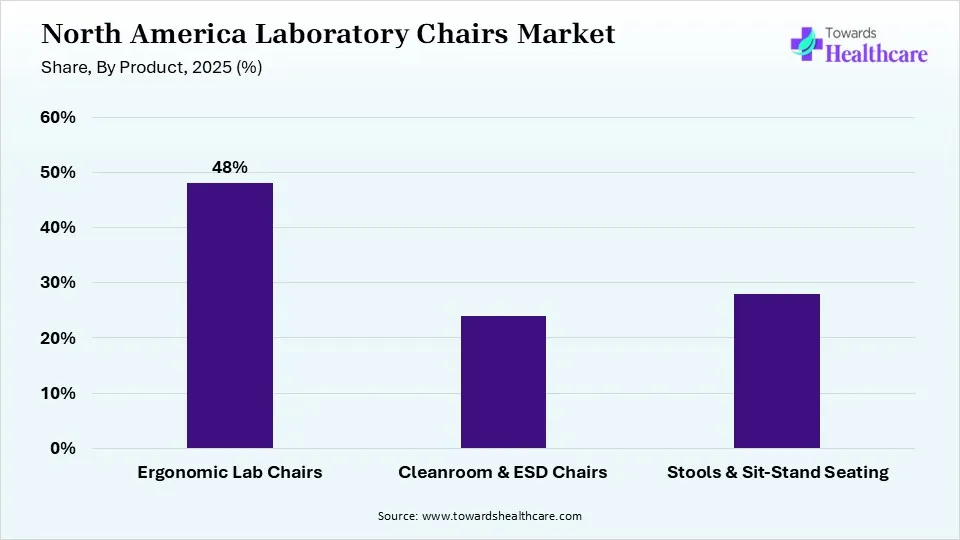
Ergonomic Lab Chairs: This segment accounted for 48% (USD 113.28 million) of the North America laboratory chairs market in 2025 and is projected to expand at a CAGR of 4.87% from 2026 to 2035. Ergonomic laboratory chairs dominate because research professionals, laboratory technicians, and scientists frequently perform tasks requiring prolonged sitting and repetitive movements.
These chairs serve controlled laboratory and manufacturing environments where contamination control and electrostatic discharge (ESD) protection are essential. Rising demand from pharmaceutical manufacturing facilities, biotechnology laboratories, semiconductor cleanrooms, and electronics testing environments is driving the adoption of specialized seating products with specific material and performance requirements.
Laboratory stools and sit-stand seating are commonly used at workbenches, microscopy stations, sample preparation areas, and biological safety cabinets. These products provide flexibility in environments where workers frequently change positions or move between different laboratory tasks. Adjustable stools and sit-stand products are particularly useful in compact laboratories and specialized research facilities. Increasing interest in flexible laboratory layouts and workplace ergonomics is expected to support continued segment growth.
Their increasing importance reflects the expansion of pharmaceutical cleanrooms, semiconductor manufacturing, and advanced biotechnology facilities. Although the segment currently represents a smaller share of demand, its specialized requirements and higher growth potential are expected to strengthen its market position.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
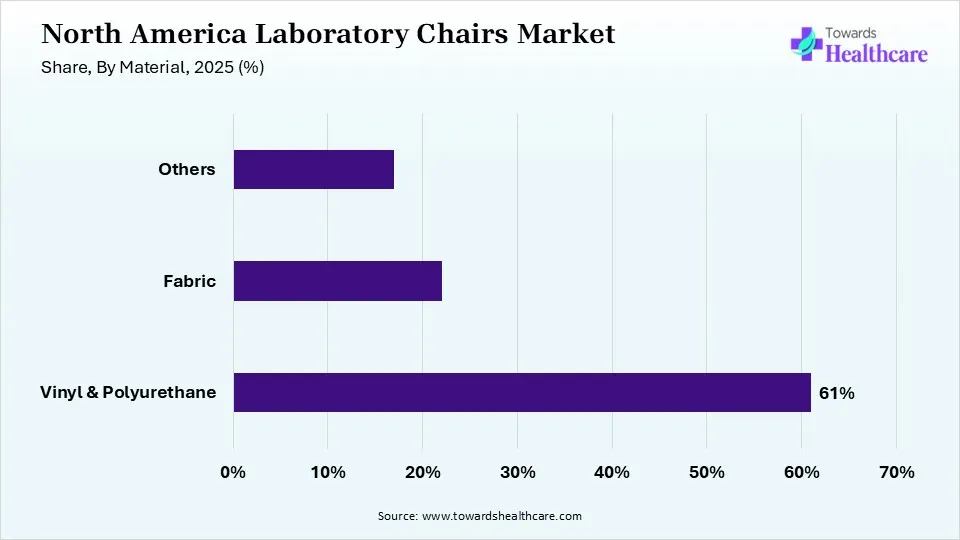
Vinyl & Polyurethane: This segment accounted for 61% (USD 143.96 million) of the North America laboratory chairs market in 2025 and is projected to expand at a CAGR of 5.75% from 2026 to 2035. Vinyl and polyurethane seating materials are widely used because they offer practical advantages in laboratory environments, including resistance to chemicals, ease of cleaning, and long-term durability. Materials suitable for pharmaceutical laboratories, hospitals, biotechnology facilities, and industrial testing environments are essential for regular cleaning and contamination control. Their diverse chair designs and price ranges promote widespread adoption, while the growing demand for specialized, cleanroom-compatible upholstery is anticipated to enhance this market segment.
These chairs are primarily used in dry laboratories, research offices, administrative areas, and other environments with limited chemical exposure and contamination risks. Their comfort and design flexibility make them suitable for workspaces involving diverse tasks. However, disinfection requirements limit their use in laboratory settings. Continued investment in research facilities and laboratory infrastructure is expected to support demand.
Key materials include antimicrobial upholstery, advanced polymers, and customized seating surfaces designed for specialized laboratory applications. Demand across environments requiring enhanced hygiene, durability, and compatibility with controlled conditions supports segment growth. Increasing adoption of customized seating solutions and ongoing material innovation further strengthen market prospects.
Its combination of chemical resistance, cleaning convenience, and durability makes it particularly suitable for laboratory environments. Fabric and other materials are expected to maintain relatively stable positions in dry laboratories, administrative research environments, and specialized applications.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
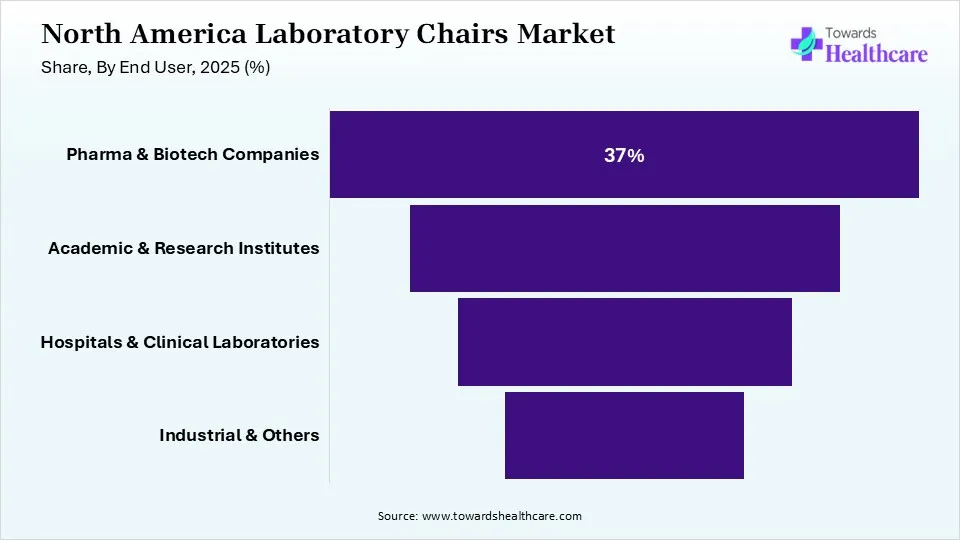
Pharma & Biotech Companies: This segment accounted for 37% (USD 87.32 million) of the North America laboratory chairs market in 2025 and is projected to expand at a CAGR of 5.11% from 2026 to 2035. Pharmaceutical and biotechnology companies represent the largest end-user category because their operations require extensive laboratory infrastructure for drug discovery, formulation development, quality testing, and biomanufacturing.
Universities, government research institutions, and independent research centers purchase laboratory seating for teaching laboratories, advanced research facilities, and scientific testing environments.
Increasing requirements for durable laboratory seating across diagnostic testing, sample handling, pathology, and microbiology activities support segment growth.
The segment includes industrial laboratories, semiconductor testing facilities, food testing laboratories, environmental testing centers, and other specialized industrial environments.
However, Industrial & Others is projected to register the fastest growth, with a CAGR of 7.01%. Increasing investments in semiconductor cleanrooms, industrial testing, and advanced manufacturing laboratories are expected to gradually increase the segment's contribution to market demand.
Analyst View: Segment shares were developed by assessing laboratory seating demand, procurement patterns, product requirements, and average selling prices across product, material, and end-user categories. Ergonomic Lab Chairs, Vinyl & Polyurethane, and Pharma & Biotech Companies currently dominate their respective segments because they address the core requirements of laboratory buyers. However, Cleanroom & ESD Chairs and Industrial & Others are expected to gain market share as specialized laboratory applications expand.
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Towards healthcare database, and Towards healthcare analysts.
U.S.: The United States accounted for 85% (USD 200.60 million) of the North America laboratory chairs market in 2025 and is projected to expand at a CAGR of 5.46% from 2026 to 2035. The country's leadership is supported by a strong life sciences ecosystem, pharmaceutical manufacturing, and clinical research infrastructure, along with a wide network of universities. Major biotechnology and pharmaceutical hubs, like Boston, San Diego, and the Research Triangle, boost investment in laboratory facilities. The increasing construction of research sites and cleanroom expansions, coupled with workplace ergonomics requirements, is expected to fuel continued market growth.
Canada: Demand for ergonomic seating and laboratory furniture in Canada is driven by research universities, pharmaceutical companies, and biotechnology firms, particularly in Toronto, Montreal, and Vancouver. Investments in life sciences and healthcare modernization are anticipated to foster regional growth.
Mexico: Expansion of pharmaceutical manufacturing, clinical laboratories, industrial testing facilities, and healthcare infrastructure drives demand for laboratory seating solutions.
Analyst View: Country-level market shares were developed by assessing laboratory infrastructure, installed seating demand, spending patterns, industrial activity, and supplier presence. The United States maintains a substantial lead because of its mature research and life sciences ecosystem. Canada is expected to experience stable expansion, supported by academic and biotechnology investments. Mexico receives the highest growth premium because of its expanding pharmaceutical, clinical, and industrial laboratory infrastructure.
| Rank | Company Name | 2025 Share (%) | Key Products / Business | Headquarters |
| 1 | BioFit Engineered Products | 14.41% | Cleanroom, ESD and lab seating | United States |
| 2 | Bevco Ergonomic Seating | 11.02% | Ergonomic lab and cleanroom chairs | United States |
| 3 | Neutral Posture | 7.63% | Lab and cleanroom seating | United States |
| 4 | Steelcase | 5.93% | Healthcare and lab seating | United States |
| 5 | Cramer | 5.08% | Lab stools and seating | United States |
| 6 | Lab Products (Avantor/VWR) | 4.24% | Lab seating distributed through VWR | United States |
| 7 | Kewaunee Scientific | 3.81% | Laboratory furniture and seating | United States |
| 8 | Fisher Scientific (Thermo Fisher) | 3.81% | Lab seating and furniture | United States |
| 9 | Global Industrial | 3.39% | Industrial and lab seating | United States |
| 10 | Herman Miller (MillerKnoll) | 2.97% | Ergonomic and lab seating | United States |
Note: Company shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
BioFit Engineered Products led the North American laboratory chairs market with an estimated 14.41% share of 2025 revenue, followed by Bevco Ergonomic Seating at 11.02% and Neutral Posture at 7.63%. BioFit Engineered Products maintains a competitive position through its cleanroom, ESD, and specialized laboratory seating portfolio. Bevco Ergonomic Seating focuses on ergonomic laboratory and cleanroom chairs, while Neutral Posture provides seating solutions designed for laboratory and controlled environments.
Other significant participants include Steelcase, Cramer, Lab Products (Avantor/VWR), Kewaunee Scientific, Fisher Scientific (Thermo Fisher), Global Industrial, and Herman Miller (MillerKnoll). These companies compete through healthcare and laboratory seating, specialized stools, integrated laboratory furniture, industrial seating, and ergonomic product portfolios.
The top 10 companies accounted for an estimated 62.29% of total market revenue in 2025, while the remaining 37.71% was distributed among regional furniture manufacturers, specialized laboratory seating producers, and distributors. The North America laboratory chairs market remains fragmented, with competition determined by ergonomic performance, chemical resistance, cleanroom compatibility, ESD certification, product durability, warranty coverage, distributor reach, and pricing. Manufacturers are increasingly differentiating their offerings through customized products, application-specific upholstery, and integrated laboratory furniture solutions.
BioFit Engineered Products: Headquartered in the United States, BioFit Engineered Products held an estimated 14.41% share of the market in 2025. Its product portfolio focuses on cleanroom, ESD, and specialized laboratory seating. The company serves laboratories and controlled environments requiring durable and application-specific seating solutions. In the Towards healthcare Companies Quadrant, BioFit Engineered Products is positioned as a Leader.
Bevco Ergonomic Seating: Headquartered in the United States, Bevco Ergonomic Seating accounted for an estimated 11.02% share of the market in 2025. Its portfolio includes ergonomic laboratory chairs and cleanroom seating designed for specialized research and manufacturing environments. The company competes through adjustable seating solutions, product customization, and application-specific designs. In the Towards healthcare Companies Quadrant, it is positioned as a Leader.
Neutral Posture: Headquartered in the United States, Neutral Posture held an estimated 7.63% share of the North American laboratory chairs market in 2025. Its offering centers on laboratory and cleanroom seating designed to support ergonomic requirements in specialized work environments. In the Towards healthcare Companies Quadrant, the company is positioned as a Leader.
Steelcase: Headquartered in the United States, Steelcase accounted for an estimated 5.93% share of the North America laboratory chairs market in 2025. Its offering includes healthcare and laboratory seating, supported by its broader expertise in workplace furniture and ergonomic product design. In the Towards healthcare Companies Quadrant, Steelcase is positioned as a Leader.
Cramer: Headquartered in the United States, Cramer held an estimated 5.08% share of the laboratory chairs market in North America in 2025. Its product offering includes laboratory stools and seating solutions designed for workbenches, research environments, and specialized laboratory applications. In the Towards healthcare Companies Quadrant, Cramer is positioned as a Leader.
Lab Products (Avantor/VWR): Headquartered in the United States, Lab Products (Avantor/VWR) accounted for an estimated 4.24% share of the market in 2025. Its market presence is supported by laboratory seating products distributed through the VWR network. The company benefits from established laboratory procurement relationships and a broad distribution platform. In the Towards healthcare Companies Quadrant, it is positioned as a Leader.
Kewaunee Scientific: Headquartered in the United States, Kewaunee Scientific held an estimated 3.81% share of the market in 2025. Its offering focuses on laboratory furniture and integrated laboratory infrastructure solutions, including seating. The company's acquisition of Nu Aire strengthened its broader laboratory solutions portfolio. In the Towards healthcare Companies Quadrant, Kewaunee Scientific is positioned as an Innovator.
Fisher Scientific (Thermo Fisher): Headquartered in the United States, Fisher Scientific, part of Thermo Fisher Scientific, accounted for an estimated 3.81% share of the North American laboratory chairs market in 2025. Its offering includes laboratory seating and furniture distributed through its extensive laboratory supply network. The company benefits from established customer relationships across pharmaceutical, academic, clinical, and industrial laboratories. In the Towards healthcare Companies Quadrant, it is positioned as an Innovator.
Global Industrial: Headquartered in the United States, Global Industrial held an estimated 3.39% share of the North America laboratory chairs market in 2025. Its product offering includes industrial and laboratory seating for commercial, manufacturing, and research environments. Its distribution capabilities and broad industrial product portfolio support its competitive position. In the Towards healthcare Companies Quadrant, Global Industrial is positioned as an Innovator.
Herman Miller (MillerKnoll): Headquartered in the United States, Herman Miller, part of MillerKnoll, accounted for an estimated 2.97% share of the North America laboratory chairs market in 2025. Its offering includes ergonomic and specialized seating solutions supported by its broader workplace furniture expertise. In the Towards healthcare Companies Quadrant, the company is positioned as an Innovator.
The North America laboratory chairs ecosystem links seating makers, furniture suppliers, distributors, lab planners & builders, and users, with each stage adding value before products reach end users.
| Ecosystem Stage | Role in the Market | Key Companies |
| Seating Makers | Design and build chairs | BioFit, Bevco, Neutral Posture, Cramer |
| Furniture Suppliers | Bundle seating with casework | Kewaunee, Steelcase, MillerKnoll |
| Distributors | Sell to labs | Avantor (VWR), Fisher Scientific, Global Industrial |
| Lab Planners & Builders | Specify lab interiors | Architects, lab planners |
| Users | Buy seating | Pharma, universities, hospitals, industry |
Sources: Company press releases, expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
Seating Makers: This stage involves the design and manufacture of laboratory chairs, stools, ergonomic seating, and specialized cleanroom and ESD products. Key participants include BioFit, Bevco, Neutral Posture, Cramer.
Furniture Suppliers: Laboratory furniture suppliers integrate seating products with casework, workbenches, storage systems, and broader laboratory infrastructure. These companies provide comprehensive laboratory furnishing solutions and support facility planning and installation. Key participants include Kewaunee, Steelcase, MillerKnoll.
Distributors: Distributors connect manufacturers with laboratory customers by offering product sourcing, procurement support, inventory management, and technical assistance. They provide access to a broad range of laboratory furniture and seating products. Key participants include Avantor (VWR), Fisher Scientific, Global Industrial.
Lab Planners & Builders: Laboratory planners, architects, engineering consultants, and construction firms specify laboratory interiors and seating requirements during facility development and renovation. Their specifications influence product selection, ergonomic standards, cleanroom compatibility, and procurement decisions.
Users: End users purchase laboratory seating for research, clinical, pharmaceutical, biotechnology, and industrial applications. Key customer groups include pharmaceutical companies, universities, hospitals, clinical laboratories, and industrial testing facilities.
The North American laboratory chairs value chain involves seating manufacturers, material suppliers, furniture integrators, and distribution partners. Laboratory planners and builders shape product specifications, while end users focus on ergonomics, durability, environmental compatibility, and budget when making purchasing decisions. Companies that integrate various stages of the ecosystem or build lasting relationships with laboratory operators and construction partners can effectively capture value through comprehensive procurement contracts and recurring customer relationships.
The Towards healthcare Companies Quadrant positions key participants in the North America laboratory chairs market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 share of the North America laboratory chairs market and our assessment of its product innovation, portfolio breadth and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Towards healthcare database and Towards healthcare analysts.
Leaders: BioFit Engineered Products, Bevco Ergonomic Seating, Neutral Posture, Steelcase, Cramer and Lab Products (Avantor/VWR) combine high market share with broad portfolios and strong innovation.
Innovators: Kewaunee Scientific, Fisher Scientific (Thermo Fisher), Global Industrial and Herman Miller (MillerKnoll) bring newer technologies and specialised products.
By Product
By Material
By End User
By Country
The North America laboratory chairs market was defined as chairs and stools designed for laboratory use in the United States, Canada and Mexico, including ergonomic lab chairs, cleanroom and ESD chairs, stools and sit-stand seating, made with vinyl and polyurethane, fabric and other materials, used by pharmaceutical and biotechnology companies, academic and research institutes, hospitals and clinical laboratories, and industrial and other laboratories. The 2025 base year was built bottom-up from demand volumes and average prices by product, material and end user and region, and checked top-down against the market-specific revenues of leading companies and published estimates. Segment, country and company values were allocated from product, material and end user and country demand. Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast.
Analyst View: The North America laboratory chairs market is anticipated to grow steadily through 2035, driven by investments in laboratory construction and specialized infrastructure, alongside a focus on ergonomics and employee wellbeing. Ergonomic Lab Chairs dominate due to the need for adjustable seating suitable for extended use. Key materials like vinyl and polyurethane are favored for their durability and ease of maintenance. The pharmaceutical and biotechnology sectors are the largest end-users due to their robust laboratory needs. Growth is expected from Cleanroom & ESD Chairs and industrial laboratory developments, particularly in Mexico. Challenges include budget constraints and competition from low-cost imports, while manufacturers focusing on ergonomic innovation are likely to enhance their market position.
1.1.1 Market Definition and Scope of Study
1.1.2 Inclusions and Exclusions
1.1.3 Currency, Units and Base Year
1.2.1 By Product
1.2.2 By Material
1.2.3 By End User
1.3.1 Market Value (USD) and Annual Growth
1.3.2 Historical Market Analysis
1.3.3 Market Growth Analysis and CAGR 2026-2035
2.2.1 Lab construction grows
2.2.2 Ergonomics matter
2.2.3 Cleanrooms expand
2.2.4 Staff wellbeing is a priority
2.4.1 Budget limits
2.4.2 Long product life
2.4.3 Low-cost imports
2.4.4 Lab construction cycles
2.7.1 Semiconductor cleanrooms
2.7.2 Cell therapy labs
2.7.3 Mexico labs
2.7.4 Bundled furniture contracts
2.8.1 Ergonomic sit-stand seating
2.8.2 Cleanroom and ESD certification
2.8.3 Antimicrobial upholstery
2.8.4 Seating bundled with lab furniture
2.8.5 Sustainable materials
2.8.6 Flexible lab layouts
3.1.1 Ergonomic Lab Chairs: Market Share and CAGR
3.1.2 Cleanroom & ESD Chairs: Market Share and CAGR
3.1.3 Stools & Sit-Stand Seating: Market Share and CAGR
3.2.1 Vinyl & Polyurethane: Market Share and CAGR
3.2.2 Fabric: Market Share and CAGR
3.2.3 Others: Market Share and CAGR
3.3.1 Pharma & Biotech Companies: Market Share and CAGR
3.3.2 Academic & Research Institutes: Market Share and CAGR
3.3.3 Hospitals & Clinical Laboratories: Market Share and CAGR
3.3.4 Industrial & Others: Market Share and CAGR
4.1.1 Market Size and Forecast, 2025-2035
4.1.2 Market Share by Product
4.1.3 Demand Drivers, Regulation and Local Competition
4.2.1 Market Size and Forecast, 2025-2035
4.2.2 Market Share by Product
4.2.3 Demand Drivers, Regulation and Local Competition
4.3.1 Market Size and Forecast, 2025-2035
4.3.2 Market Share by Product
4.3.3 Demand Drivers, Regulation and Local Competition
5.5.1 Product Portfolio Benchmarking
5.5.2 Geographic Presence Benchmarking
5.5.3 Technology and Innovation Benchmarking
6.1.1 Instrument list price and discount analysis
6.1.2 Consumables and reagent pricing per test or sample
6.1.3 Service contract and subscription pricing
6.1.4 Academic vs. biopharma pricing tiers
7.1.1 Pharmaceutical and biotechnology companies
7.1.2 Academic and government research institutes
7.1.3 CROs, CDMOs and core facilities
7.1.4 Clinical and diagnostic laboratories
9.1.1 Key raw materials and component sourcing
9.1.2 OEM and contract manufacturing
9.1.3 Distributor and e-procurement channels
9.1.4 Cold chain and logistics requirements
11.1.1 Automation and high-throughput workflows
11.1.2 Digital, cloud and AI-enabled analysis
11.1.3 Next-generation platforms and consumables
11.1.4 Patent and IP landscape
12.1.1 Research-use-only vs. IVD regulatory pathways
12.1.2 GMP and quality standards for bioprocessing
12.1.3 Biosafety and laboratory standards
12.1.4 Data integrity and compliance requirements
17.1.1 Company Overview
17.1.2 North America Laboratory Chairs Product Portfolio
17.1.3 Financial Performance and Market Share
17.1.4 Recent Developments and Strategy
17.1.5 SWOT Analysis
17.2.1 Company Overview
17.2.2 North America Laboratory Chairs Product Portfolio
17.2.3 Financial Performance and Market Share
17.2.4 Recent Developments and Strategy
17.2.5 SWOT Analysis
17.3.1 Company Overview
17.3.2 North America Laboratory Chairs Product Portfolio
17.3.3 Financial Performance and Market Share
17.3.4 Recent Developments and Strategy
17.3.5 SWOT Analysis
17.4.1 Company Overview
17.4.2 North America Laboratory Chairs Product Portfolio
17.4.3 Financial Performance and Market Share
17.4.4 Recent Developments and Strategy
17.4.5 SWOT Analysis
17.5.1 Company Overview
17.5.2 North America Laboratory Chairs Product Portfolio
17.5.3 Financial Performance and Market Share
17.5.4 Recent Developments and Strategy
17.5.5 SWOT Analysis
17.6.1 Company Overview
17.6.2 North America Laboratory Chairs Product Portfolio
17.6.3 Financial Performance and Market Share
17.6.4 Recent Developments and Strategy
17.6.5 SWOT Analysis
17.7.1 Company Overview
17.7.2 North America Laboratory Chairs Product Portfolio
17.7.3 Financial Performance and Market Share
17.7.4 Recent Developments and Strategy
17.7.5 SWOT Analysis
17.8.1 Company Overview
17.8.2 North America Laboratory Chairs Product Portfolio
17.8.3 Financial Performance and Market Share
17.8.4 Recent Developments and Strategy
17.8.5 SWOT Analysis
17.9.1 Company Overview
17.9.2 North America Laboratory Chairs Product Portfolio
17.9.3 Financial Performance and Market Share
17.9.4 Recent Developments and Strategy
17.9.5 SWOT Analysis
17.10.1 Company Overview
17.10.2 North America Laboratory Chairs Product Portfolio
17.10.3 Financial Performance and Market Share
17.10.4 Recent Developments and Strategy
17.10.5 SWOT Analysis