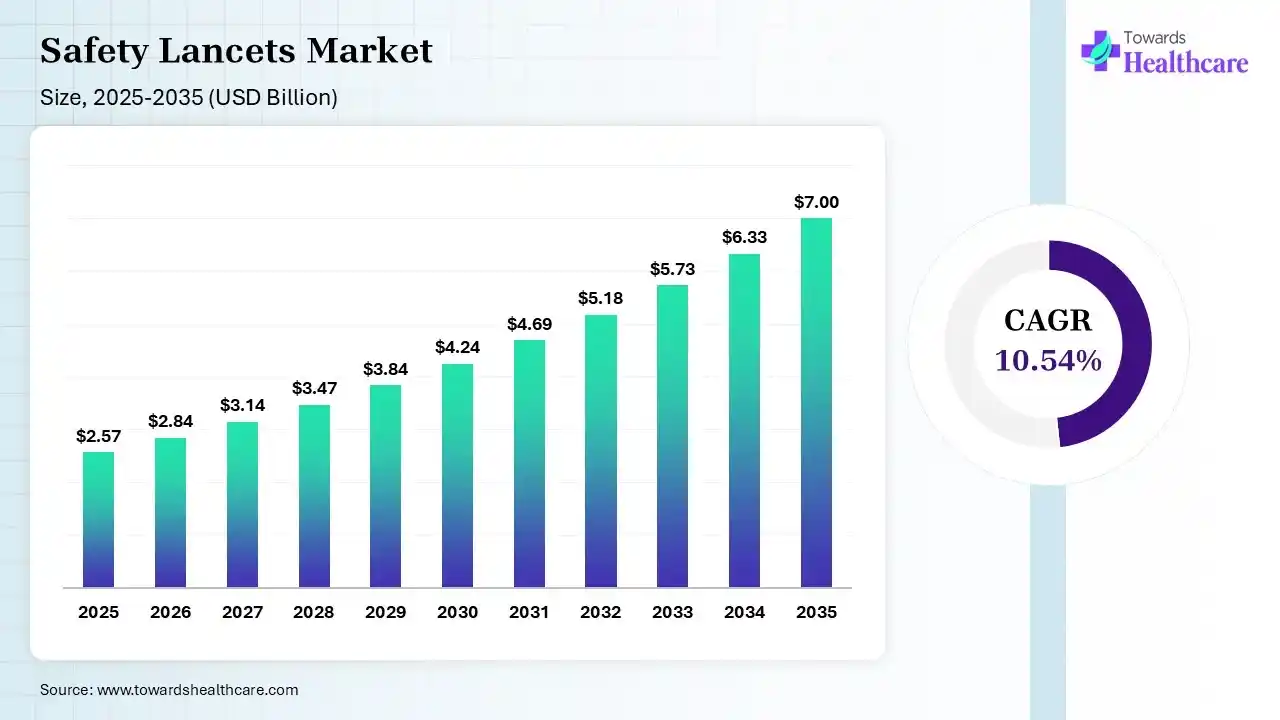
The safety lancets market size stood at US$ 2.57 billion in 2025, grew to US$ 2.84 billion in 2026, and is forecast to reach US$ 7.00 billion by 2035, expanding at a CAGR of 10.54% from 2026 to 2035.
Safety Engineering Is Converting Routine Capillary Sampling Into a Higher-Value, Compliance-Driven Device Market
Market estimates vary materially depending on whether safety lancets are defined narrowly as single-use safety-engineered capillary blood-sampling devices or more broadly within the overall lancet category. The report therefore distinguishes the dedicated safety-lancet market from the broader lancet ecosystem to avoid double counting.
The market is structurally driven by diabetes and other conditions requiring repeated blood sampling, expansion of point-of-care diagnostics, increasing home testing, pediatric and neonatal sampling requirements, and regulatory emphasis on sharps-injury prevention. Safety engineering is increasingly becoming a procurement criterion rather than a product differentiator alone.
Lancets are small, sharp needles used to puncture the skin to withdraw a minuscule quantity of blood. However, standard lancets carry the risk of needlestick injuries. Safety lancets are a safer alternative to standard lancets as they contain retractable needles, thereby preventing accidental pricks and reducing the risk of infection. Safety lancets are more specific and personalized to every patient type, as they can puncture and penetrate to a predetermined depth during sample collection. These lancets are commonly used to withdraw blood during blood glucose monitoring. They are also used in various tests such as lipid profiles, HbA1C, and blood typing.
The rising prevalence of chronic disorders like diabetes and cholesterol increases the demand for safety needles. The rising needlestick injuries from standard lancets promote the use of safety lancets. Additionally, technological advancements and the latest innovations in safety lancets boost market growth.
Safety lancets are single-use medical devices designed to obtain small blood samples through a controlled skin puncture while reducing the risk of accidental needlestick injuries. The track and trace solution market is growing as manufacturers and healthcare providers seek stronger product identification, supply-chain visibility, inventory control, and protection against counterfeit devices. Key trends include barcode serialization, QR-based identification, RFID tagging, connected inventory systems, and digital product authentication. Technological advancements in IoT enable real-time tracking, automated verification, and improved supply-chain monitoring. Major drivers include increasing blood glucose testing, growing adoption of home-based diagnostics, infection-control requirements, rising safety awareness, and the need for efficient product recalls. Future opportunities include smart packaging, automated inventory tracking, AI-enabled demand forecasting, digital authentication, and integrated platforms connecting manufacturers, distributors, diagnostic centers, hospitals, pharmacies, and home healthcare users.
Safety lancet pricing is fundamentally a per-device consumables economics question, with realized ASP varying by activation mechanism, penetration depth, needle or blade configuration, sterility requirements, packaging, application, purchase volume, geography, and sales channel. Market offerings span basic single-use safety formats through more specialized pressure- or contact-activated and pediatric or neonatal designs, creating meaningful price differentiation even within the same broad product category.
Our analysis indicates that pricing is increasingly reflecting the total value of safety and workflow simplification, rather than the physical cost of the lancet alone. Automatic retraction, concealed needles, controlled penetration, activation reliability, and reduced handling exposure can support a premium over conventional or less-engineered devices, while institutional buyers continue to exert downward pressure through high-volume procurement and standardized contracts. Our assessment is that the market will remain bifurcated between cost-driven high-volume products and differentiated safety formats where clinical workflow, user confidence, and injury-risk reduction provide greater pricing headroom.
In our view, the most significant implication is that manufacturers cannot pursue ASP expansion independently of demonstrable product differentiation. High-volume hospital and diagnostic-laboratory contracts are likely to remain particularly price-sensitive, whereas pediatric, neonatal, home-testing and specialized sampling applications can provide greater scope for value-based differentiation. The competitive opportunity therefore lies in balancing manufacturing efficiency and low unit cost with safety performance, comfort and application-specific functionality, particularly as emerging-market adoption expands the addressable volume base.
The development of blood self-sampling devices or lancing devices increases the demand and use of safety lancets. These devices automatically collect blood samples from the skin, offering a standardized and safe approach to obtaining blood samples. This benefits children, the geriatric population, and adults having a fear of piercing their skin. Hence, the advent of self-sampling devices increases patient adherence. These devices enable interoperability and interface with the current total lab automation. Additionally, they are affordable, sustainable, and of high quality. The devices either collect blood from the upper arm or prick the finger. Blood sampling can maintain laboratory testing for patients who live far away from the hospital. The increasing investments in microfluidics and demand for safe, latest innovations and painless withdrawal of blood potentiate the market growth.
Patients from numerous developing countries are unaware of the safety lancets for withdrawing capillary blood. Most of the people use conventional lancets as they are a cheaper alternative and easily available. Safety lancets are also not preferred due to pain, fear and anxiety. This hampers the market growth.
The safety lancets value chain spans medical-grade raw materials, needles or blades and plastic components, precision molding and assembly, safety-mechanism integration, sterilization, packaging, quality testing, distribution, and healthcare delivery channels.
Our analysis indicates that the greatest supply-chain differentiation occurs at the intersection of precision component manufacturing and safety-mechanism assembly, where tight tolerances, activation reliability, sterility requirements, and quality-control standards can raise manufacturing complexity relative to basic lancet formats. At the upstream end, availability and pricing of medical-grade metals, polymers, packaging materials, and specialized components can influence production economics, while downstream distributors and institutional procurement systems exert pressure on pricing and inventory efficiency. Our assessment is that supply-chain resilience, not manufacturing capacity alone, is becoming a meaningful competitive capability as suppliers seek to support higher volumes without compromising product consistency or regulatory compliance.
In our view, the most significant strategic implication is that companies with greater control over critical components, manufacturing processes, quality assurance, and regional distribution can reduce exposure to supply disruptions and improve cost predictability. Localization of production and dual-sourcing strategies may become increasingly relevant where transportation costs, regulatory requirements, geopolitical exposure, or customer expectations for dependable supply create vulnerabilities. From our assessment, this creates opportunities for manufacturers and component suppliers that can combine precision manufacturing, scalable automation, validated sterilization, efficient packaging, and regional fulfillment while maintaining competitive unit economics.
The principal demand engine is the growing requirement for capillary blood sampling, particularly where testing is repeated over long periods. Home diagnostics adds another structural driver because products must be intuitive enough for non-professional users while maintaining safe post-use containment.
Regulatory and occupational-safety requirements further reinforce adoption. In the U.S., engineering controls and safer medical devices are explicitly embedded in bloodborne-pathogen exposure-control requirements, while facilities are required to consider commercially available safer devices.
The principal restraints are low unit economics in high-volume procurement, price sensitivity in emerging markets, disposable-device waste, qualification requirements, and competition from conventional low-cost lancets.
Key Coverage
North America held the largest share of the safety lancets market in 2025. The rising prevalence of diabetes and other disorders, advanced healthcare infrastructure, increasing investments, and technological advancements drive the market. In 2022, around 38.4 million people in the US and around 5.7 million people in Canada were suffering from both type 1 and 2 diabetes. According to the Centers for Disease Control and Prevention, more than half of the US citizens are suffering from cholesterol. The Occupational Safety and Health Administration promotes the use of safety lancets among healthcare workers who perform finger-prick blood sampling in the workplace to prevent needlestick injuries. The Canadian Government governs the use of glucometers, test strips, and lancets for regular monitoring of blood glucose levels with an aim to prevent serious diabetes complications and long-term hospitalizations. The market is also driven by increasing awareness, and the presence of key players augment market growth.
U.S. Safety Lancets Market Driven by Advanced Healthcare Adoption
The U.S. market is expanding through widespread diabetes screening, high adoption of advanced point-of-care diagnostics, strong demand for automated safety features, and established medical-device distribution networks. Growing utilization of self-testing technologies and increasing preference for ergonomically designed lancets are creating additional opportunities for manufacturers across hospitals, pharmacies, laboratories, and homecare environments.
Canada’s Safety Lancets Market Benefits from Accessible Healthcare
Canada is notably growing due to increasing preventive health screening, expansion of community-based healthcare services, and rising demand for convenient diagnostic equipment in remote and underserved areas. Growing use of portable testing devices and emphasis on reducing occupational exposure among healthcare workers are encouraging healthcare facilities to adopt safer blood-collection solutions.
Asia-Pacific is projected to host the fastest-growing safety lancets market in the coming years. The rising geriatric population, increasing prevalence of diabetes and other chronic illnesses, increasing investments, and demand for point-of-care diagnostics drive the market. The rising prevalence of chronic disorders potentiates regular testing for these disorders, thereby increasing the demand for safety lancets. China accounts for more than half of the familial hypercholesterolemia cases in the world. In the Asia-Pacific region, familial hypercholesterolemia accounts for almost 15 million cases. Several organizations conduct training sessions to increase awareness of the use of safety lancets in the region.
India’s Safety Lancets Market Gains from Expanding Diagnostics
India is significantly growing due to rapid expansion of diagnostic centers, increasing affordability of blood-testing devices, and growing availability of medical products beyond major cities. Rising consumer awareness of personal health monitoring and the development of organized retail and pharmacy networks are improving access to safety lancets and supporting their broader adoption.
China’s Safety Lancets Market Strengthened by Domestic Manufacturing
China is notably expanding through strong domestic medical-device production, increasing modernization of healthcare facilities, and wider deployment of diagnostic services in developing regions. Improvements in local manufacturing capabilities are supporting product availability and cost competitiveness, while growing investment in community healthcare and preventive diagnostics is creating additional demand for efficient blood-sampling devices.
Europe is expected to grow significantly in the safety lancets market during the forecast period. The increasing diseases is increasing the use as well as demand for the safety lancets in Europe. At the same time, due to their easy and safe use, their adoption in homecare settings is also increasing.
The growing incidence of diseases is increasing the use of safety lancets in the healthcare sector. Furthermore, due to its advantages of reducing the risk of infections, it also contributes to the same. Thus, all these factors promote the market growth.
The industries in Germany are focusing on the development of safety lancets due to their increasing use. At the same time, its use in the homecare setting is also rising as they are easy to use. This, in turn, is also supported by the government.
UK Safety Lancets Market Supported by Community Healthcare
The UK market is significantly growing through increasing community-based diabetes services, broader availability of self-monitoring programs, and demand for user-friendly diagnostic devices. Growing emphasis on reducing healthcare-associated risks and improving patient convenience is encouraging the adoption of single-use safety lancets across primary care, pharmacies, specialist clinics, and home-based testing environments.
By type, the pressure-activated safety lancet segment held the largest share in the safety lancets market in 2025. A pressure-activated safety lancet is a device that withdraws blood by placing it on the finger and applying very little pressure, enabling the needle to prick the skin and retract it. It does not contain a button to aid the needle to come out. It is widely preferred due to its simplicity, sterility, and pain-masking ability. It increases patient adherence as it offers safety and comfort for the patient.
The side button safety lancet segment is projected to expand rapidly in the safety lancet market in the coming years. A side button safety lancet consists of a button that automatically retracts and locks, protecting against accidental needlestick injuries. Its spring-loaded action helps ensure a swift, gentle action with controlled penetration.
By end-use, the hospitals & clinics segment registered its dominance over the global market in 2025. Hospitals & clinics have sufficient facilities and tools for point-of-care diagnosis. Numerous patients prefer hospitals & clinics for testing purposes as they are governed by stringent regulations and provide high-quality testing services. Additionally, hospitals & clinics have suitable facilities for disposing of the safety lancets. In hospitals & clinics, patients can undergo blood testing for several other disorders, but at-home care testing is not available.
The home diagnostics segment is expected to grow at the fastest rate in the market during the forecast period. Home diagnostics are the most preferred option for geriatric patients. The availability of at-home care testing devices for blood glucose monitoring and HbA1C levels potentiates the market growth.
Tentative Leading Company Universe - 23 Companies Shaping the Safety Lancets Market
| Company | Headquarters | Market Position | Core Strength | Major Applications/Segments | |
| 1 | Becton, Dickinson and Company | U.S. | Global leader | Safety medical devices | Clinical blood sampling |
| 2 | F. Hoffmann-La Roche | Switzerland | Global leader | Diabetes diagnostics | Glucose/clinical testing |
| 3 | B. Braun | Germany | Global medical-device player | Safety and clinical devices | Hospitals/diagnostics |
| 4 | Terumo Corporation | Japan | Global device supplier | Blood-management technology | Clinical sampling |
| 5 | Nipro Corporation | Japan | Global device supplier | Diabetes/blood sampling | Glucose/clinical |
| 6 | Owen Mumford | UK | Safety-lancet specialist | Unistik portfolio | Adult/pediatric/neonatal |
| 7 | HTL-STREFA | Poland | Specialist manufacturer | Safety lancets | Glucose/diagnostics |
| 8 | SARSTEDT | Germany | Preanalytics specialist | Capillary sampling | Clinical/laboratory |
| 9 | Greiner Bio-One | Austria | Laboratory specialist | Blood collection | Clinical diagnostics |
| 10 | Unisto | Switzerland | Safety-device specialist | Single-use safety devices | Blood sampling |
| 11 | Gerresheimer | Germany | Medical-device manufacturer | Drug/device manufacturing | Specialty medical devices |
| 12 | Merit Medical Systems | U.S. | Interventional-device player | Disposable medical devices | Clinical applications |
| 13 | Ypsomed | Switzerland | Diabetes-device specialist | Diabetes technology | Home glucose testing |
| 14 | ARKRAY | Japan | Diabetes diagnostics specialist | Glucose monitoring | Diabetes testing |
| 15 | AgaMatrix | U.S. | Diabetes technology player | Glucose-testing ecosystem | Home diagnostics |
| 16 | Medline Industries | U.S. | Healthcare supply leader | Medical consumables | Hospitals/clinics |
| 17 | Cardinal Health | U.S. | Distribution/medical supplies | Healthcare distribution | Institutional demand |
| 18 | McKesson | U.S. | Distribution/medical supplies | Healthcare channels | Pharmacy/home care |
| 19 | Narang Medical | India | Regional supplier | Medical consumables | Emerging markets |
| 20 | Sterimed Group | France | Medical-device specialist | Sterile disposable products | Clinical use |
| 21 | Improve Medical Technology | China | Emerging specialist | Safety blood-sampling devices | Asia/emerging markets |
| 22 | SafePoint Technologies | U.S. | Safety-device specialist | Engineered safety products | Clinical safety |
| 23 | DarioHealth | U.S. | Digital-health ecosystem | Diabetes monitoring | Home diagnostics |
The safety lancets market remains competitively fragmented across global medical-device manufacturers, diabetes-care specialists, diagnostic consumables suppliers, and regional private-label producers, with competitive position influenced by product breadth, safety-engineering capabilities, manufacturing scale, regulatory reach, pricing, and channel access. The market’s projected expansion, from approximately USD 2.57 billion in 2025 to USD 7 billion by 2035, representing an estimated 10.54% CAGR, creates substantial room for both established suppliers and focused specialists to gain share as healthcare providers increasingly adopt safer blood-sampling devices.
Our analysis indicates that market share leadership is likely to be determined less by unit volume alone and more by the ability to combine high-volume manufacturing economics with differentiated safety features, reliable activation mechanisms, broad application coverage, and institutional procurement access. Large suppliers can leverage scale and established distribution to compete for standardized hospital and diagnostic volumes, while specialist manufacturers can target faster-growing niches such as pediatric, neonatal, home-testing, and application-specific sampling. Our assessment is that competitive share is therefore increasingly shaped by the intersection of cost position, product performance, regulatory credentials, and customer or channel penetration, rather than by product availability alone.
In our view, the most significant strategic implication is that share gains will increasingly come from capability expansion and targeted portfolio positioning rather than broad-based price competition. Suppliers with manufacturing flexibility, differentiated safety designs, geographic reach, and the ability to meet high-volume tenders can strengthen their position, while smaller players may gain ground through specialized products, private-label partnerships, or underserved regional markets. The report therefore evaluates competitive positioning through market share estimates, revenue contribution, product portfolio breadth, technology differentiation, geographic presence, manufacturing footprint, distribution reach, and strategic developments to distinguish scale advantages from genuine competitive differentiation.
The safety lancets market comprises established medical-device manufacturers, diabetes-care specialists, diagnostic consumables suppliers, and specialized regional producers competing across different combinations of safety mechanisms, penetration configurations, applications, and geographic markets. With the overall market estimated at approximately USD 2.57 billion in 2025 and projected to reach USD 7 billion by 2035, the scale of the opportunity makes company-level differences in product breadth, manufacturing scale, regulatory access, distribution reach, and innovation increasingly important to future competitive positioning.
Our analysis indicates that competitive differentiation is increasingly determined by the ability to combine cost-efficient production with reliable safety engineering and application-specific product development. Companies with broad portfolios and established institutional channels can address high-volume demand, while more specialized participants can compete through differentiated pediatric, neonatal, home-testing, or ergonomically optimized designs. Our assessment is that evaluating companies solely on revenue or product presence can obscure meaningful capability differences; manufacturing footprint, technology ownership, geographic penetration, regulatory coverage, customer concentration, and innovation activity provide a more complete view of sustainable competitive advantage.
In our view, the most significant implication is that future market-share gains will depend on how effectively individual companies align their portfolios with the fastest-growing applications and procurement requirements. Suppliers capable of simultaneously delivering competitive unit economics, consistent quality, dependable supply, and differentiated safety performance may have greater scope to expand across institutional and emerging-market channels, while narrower portfolios may leave companies exposed to commoditization or tender-driven pricing pressure. The company profiles therefore assess each participant through a consistent strategic lens covering business positioning, product portfolio, technology capabilities, manufacturing footprint, geographic reach, applications served, distribution model, strategic initiatives, and competitive strengths and gaps.
By Type
By End-Use
By Region