Gene Vector Market Expands Rapidly with Global Biotech Boom
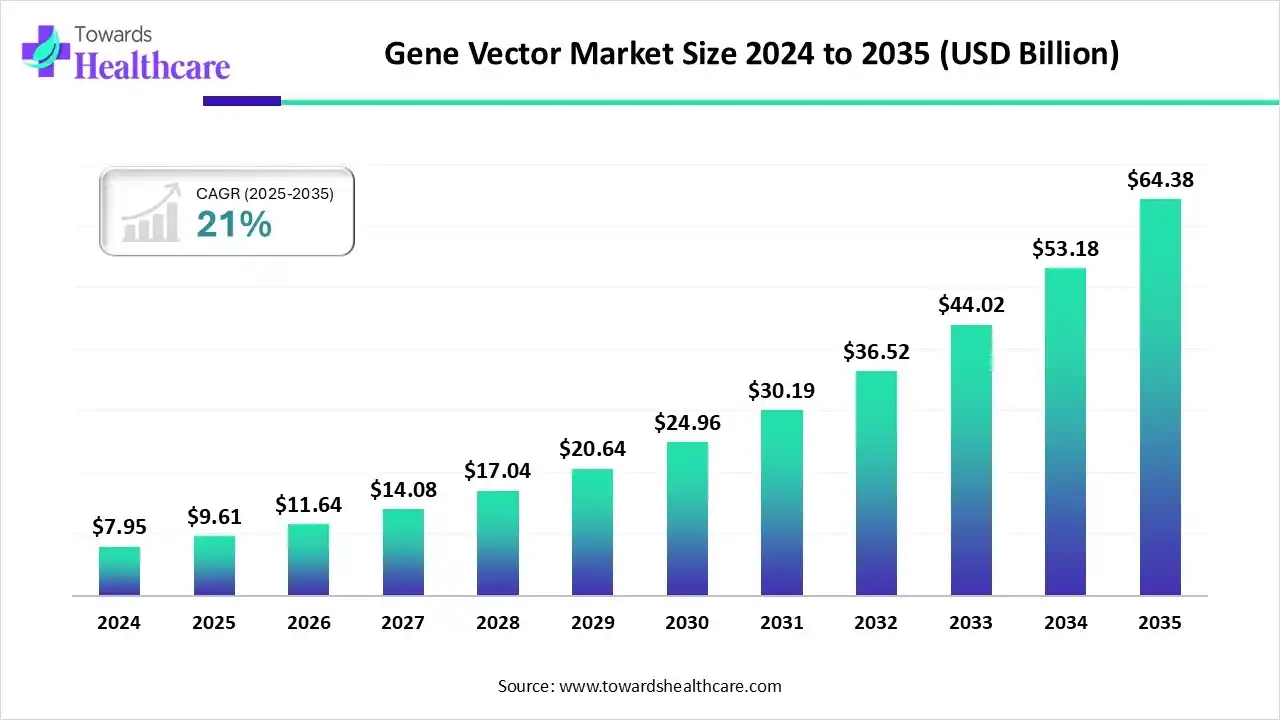
Based on market forecasts, the global gene vector market, projected at USD 9.61 billion in 2025, is expected to reach USD 64.38 billion by 2035, growing at a CAGR of 21% over the forecast period. The gene vector market is growing due to rising demand for gene and cell therapy. North America’s dominance can be attributed to the rising demand for personalized medicine.
Last updated
21 April 2026 |
Primary source: Towards Healthcare
| Report:
6412 | Derived values are labelled
Gene Vector Market Size, Key Players with Trends and Insights
The global gene vector market size is calculated at US$ 9.61 billion in 2025, grew to US$ 11.64 billion in 2026, and is projected to reach around US$ 64.38 billion by 2035. The market is expanding at a CAGR of 21% between 2026 and 2035.
The development of more sophisticated gene editing technologies, the growing demand for personalized medicine, and the rising incidence of infectious diseases, cancer, and genetic disorders are some of the factors propelling the growth of the gene vector market. Numerous products that deliver therapeutic genes via viral vectors have been approved for use in the treatment of infectious diseases, cancer, and monogenic disorders.
Key Takeaways
Gene vector industry poised to reach USD 9.61 billion by 2025.
Forecasted to grow to USD 64.38 billion by 2035.
Expected to maintain a CAGR of 21% from 2026 to 2035.
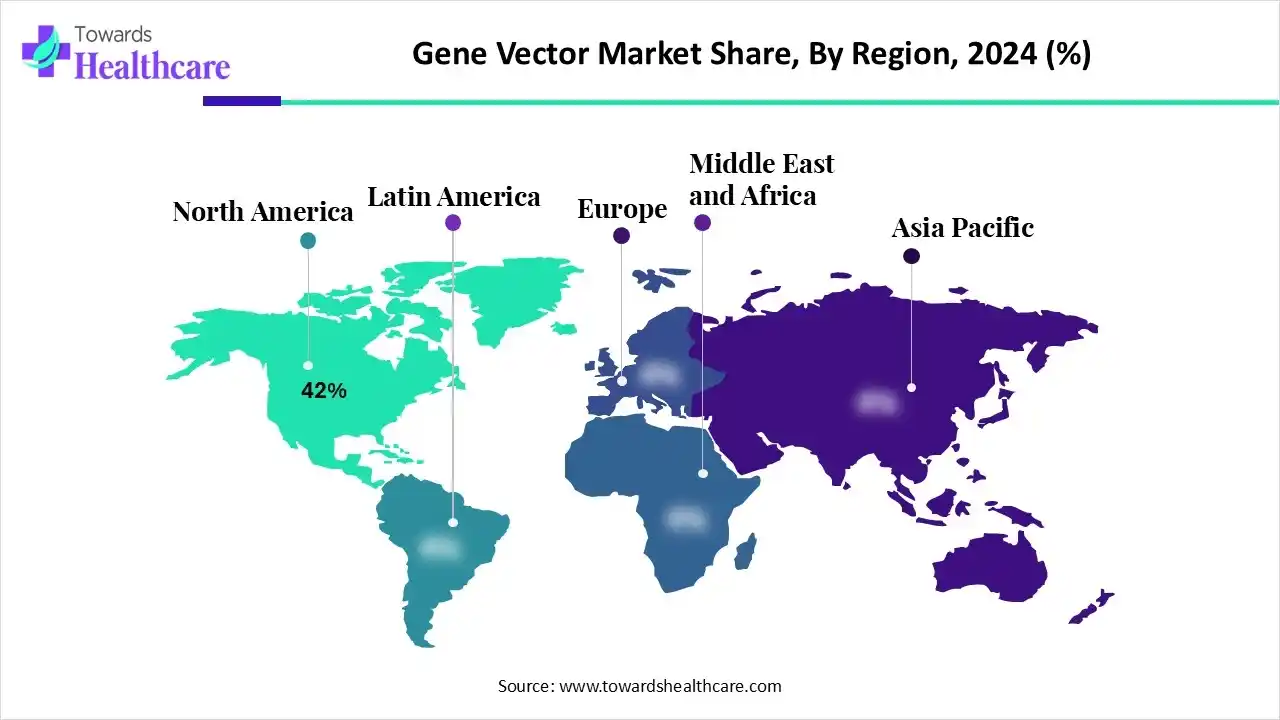
North America dominated the gene vector market in 2024, with a revenue of 42%.
Asia Pacific is expected to grow at the fastest CAGR during the forecast period.
By type, the viral vectors segment dominated the market with a revenue of 65% in 2024.
By type, the non-viral vectors & delivery segment is expected to grow at the fastest CAGR during the forecast period.
By application, the commercial therapeutics segment dominated the market with a revenue of 40% in 2024.
By application, the clinical development/trial supply segment is expected to grow at the fastest CAGR during the forecast period.
By form, the bulk GMP viral vector drug substance segment dominated the gene vector market with a revenue of 45% in 2024.
By form, the formulated drug product/fill-finish segment is expected to grow at the fastest CAGR during the forecast period.
By end-user, the biopharmaceutical & gene-therapy developers segment dominated the market with a revenue of 55% in 2024.
By end-user, the academic & research institutes segment is expected to grow at the fastest CAGR during the forecast period.
Executive Summary Table
Table
Scope
Market Size in 2025
USD 9.61 Billion
Projected Market Size in 2035
USD 64.38 Billion
CAGR (2026 - 2035)
21%
Leading Region
North America by 42%
Market Segmentation
By Type, By Application, By Form, By End-User Industry, By Region
The gene vector market comprises the development, manufacturing, and supply of delivery vehicles, viral (AAV, adenovirus, lentivirus) and non-viral (plasmids, lipid nanoparticles, polymeric carriers, nanoparticles), used to transport genetic material (DNA, RNA, gene-editing tools) into cells for research, gene therapy, and vaccine applications. It includes specialized vector CDMOs, reagent and plasmid suppliers, equipment and consumable manufacturers, and platform technology providers that together support discovery, clinical development, and commercial-scale production of gene-based medicines and vaccines.
Gene Vector Market Outlook
Industry Growth Overview: The market for gene vectors is anticipated to expand dramatically, reaching a valuation of tens of billions, driven by the growing demand for gene therapy. Two important factors are the prevalence of genetic disorders rising and ongoing innovation.
Global Expansion: Despite North America's dominance, the Asia-Pacific is the market with the fastest rate of growth because of investments and sizable patient populations. Strategic alliances are also being used to expand into emerging markets.
Major Investors: Governments, venture capital, and biotechnology and pharmaceutical companies are important investors. Partnerships, acquisitions, and increased R&D spending support market growth and guarantee ongoing innovation.
How is AI Transforming the Gene Vector Market?
Capsid optimization could be accelerated while development time and manufacturing costs are decreased, thanks to the development of artificial intelligence (AI), especially machine learning. An essential component of artificial intelligence (AI), machine learning (ML) allows computers to learn from data and make decisions using algorithms without requiring a lot of programming.
Segmental Insights
Type Insights
Why the Viral Vectors Dominating the Gene Vector Market?
The viral vectors segment dominated the market, accounting for 65% of revenue in 2024, as viruses have evolved to efficiently deliver their genetic payload to cells, making them the most powerful and efficient gene delivery vehicles. In cancer applications, viral vectors have received the most attention. Additionally, viral vectors have been used to treat monogenic illnesses. Additionally, viral vectors have been used to treat monogenic illnesses.
Non-Viral Vectors & Delivery
The non-viral vectors & delivery segment is expected to grow at the highest rate in the gene vector market during 2025-2034, as non-viral vectors are widely used in gene therapy and are essential tools for therapeutic gene delivery. Because of their low immunogenicity, good biocompatibility, ease of synthesis and modification, and affordability, non-viral vectors are frequently developed and used in clinical practice. Interestingly, non-viral vectors can enhance therapeutic effects, prolong circulation time, improve cargo uptake, and deliver cargo to specific locations.
Services, Reagents & Platform Support
The services, reagents & platform support segment is growing significantly in the market due to comprehensive gene vector services, including extensive GMP CDMO production and manufacturing facilities. High-quality reagents, including plasmids, capsids, and enzymes, as well as thorough analytical, QC, and characterization services for safety and potency, support this.
Application Insights
How the Commercial Therapeutics Dominate the Gene Vector Market in 2024?
The commercial therapeutics segment dominated the market, accounting for 40% of revenue in 2024. In order to treat illnesses like cancer, genetic disorders, and infectious diseases, a gene vector introduces therapeutic genetic material into target cells. These can be non-viral (like lipid nanoparticles) or viral (like AAV, lentivirus), with viral vectors predominating in the market because of their high efficiency.
Clinical Development/Trial Supply
The clinical development/trial supply segment is expected to grow at the fastest CAGR in the gene vector market during 2025-2034. Gene vectors used in clinical development and trial supply require careful production, strict cold chain logistics, and reliable tracking for efficacy and safety. To deliver a viable therapeutic, the intricate supply chain necessitates precise coordination.
Vaccines & Preventive Applications
The vaccines & preventive applications segment is growing significantly in the market. New platforms for vaccine design, such as those based on viral vectors and virus-like particles (VLPs), have emerged to get around the drawbacks of traditional vaccines. Vaccines using viral vectors are very effective and provide protection quickly.
Form Insights
Which Form Dominated the Gene Vector Market in 2024?
The bulk GMP viral vector drug substance segment accounted for 45% of market revenue in 2024 because of its demonstrated clinical effectiveness and high efficiency in delivering genetic material. Although there are other non-viral approaches, viral vectors are better at transducing (transferring genes into) target cells, which allows for more successful treatment outcomes for a variety of illnesses.
Formulated Drug Product/Fill-Finish
The formulated drug product/fill-finish segment is expected to grow at the fastest rate in the gene vector market during 2025-2034. This crucial final step in delivering cutting-edge treatments to patients is represented by fill/finish operations for medications and vaccines based on viruses and viral vectors. It can take years to become proficient in aseptic fill/finish. Through experience with a variety of products and regulatory interactions, CDMOs with a proven track record have already mastered these obstacles and improved their procedures.
Plasmids & Raw Materials
The plasmids & raw materials segment is growing significantly in the market. For many years, plasmids and plasmid DNA (pDNA) have been essential elements in the molecular biology of recombinant DNA. A key component of the production of viral vector ATMP is its use as a precursor raw material.
End-User Industry Insights
Which End-User Industry Dominated the Gene Vector Market in 2024?
The biopharmaceutical & gene-therapy developers segment dominated the market, accounting for 55% of revenue in 2024. Pharmaceutical firms have been creating treatments to cure or stop illnesses. In order to repair genetic mutations or introduce functional genes to replace or inhibit the mutated gene, biopharma companies utilize genetic material to create genomic gene, cell, and gene editing treatments.
Academic & Research Institutes
The academic & research institutes segment is expected to grow at the fastest CAGR in the gene vector market during 2025-2034. Viral and non-viral gene vectors are used by academic and research institutions to introduce genetic material into cells for gene therapy and research. The National Institutes of Health (.gov), King's College London, the San Raffaele Telethon Institute for Gene Therapy, and the Center for Stem Cell Research (CSCR) are a few notable organizations.
CDMOs/CMOs
The CDMOs/CMOs segment is growing significantly in the market. The choice to outsource development is more crucial than ever in the rapidly evolving field of biotechnology. A wider range of capabilities and integrations is now available thanks to the evolution of the CDMO model. The hybrid idea of a CDMO that supports manufacturing and scale-up processes emerged as a result of the need for "development support" over time, which included formulation, method development, and analytical testing.
Which Region is Dominating the Gene Vector Market?
North America dominated the gene vector market in 2024, accounting for 42% of revenue. Major factors driving the growth of the market in North America include the presence of numerous academic research institutions active in the fields of molecular biology and genetics, the region's well-established biotech and pharmaceutical industries, and improvements in the research and development infrastructure in the United States and Canada.
Rising Wave of Gene Therapies Fuels Vector Demand in the U.S.
The ASGCT reported 679 clinical-stage asset indications in Q2 2025, up from 645 in Q1. Approximately 2,210 (49%) of the 4,469 therapies that were monitored were gene therapies, while 962 (22%) were non-genetically modified cell therapies. About 83% of genetically modified cell therapies target oncology, with CAR-T accounting for 55% of these treatments.
Importance of Government Support for Promoting Market Growth in the Asia Pacific
Asia Pacific is estimated to host the fastest-growing gene vector market during the forecast period as the region makes large investments in the development of biotechnology and therapeutics. Leading the way in this expansion are South Korea, Japan, and China. Governments are supporting infrastructure upgrades and the approval of clinical trials. Both established pharmaceutical companies and new biotech startups are focusing on new delivery technologies and local production.
China’s Cell Therapy Trials Surge Nationwide
Clinical trials for cell therapy have advanced quickly in China in recent years. Clinical trials for cell therapy are increasing quickly in China, reaching a peak of 43 in 2022 and 61 in 2023. Furthermore, China's cell therapy clinical trials encompass a wide range of cell types, indications, and targets. Furthermore, there are cell therapy clinical trials spread across 16 provinces in China. Jiangsu, Beijing, and Shanghai are the top three provinces.
Rising Investments: Major Promoter in Europe
Europe is expected to grow at a significant CAGR in the gene vector market during 2025-2034. Growing funding for gene therapy research and an encouraging regulatory environment from the European Medicines Agency (EMA) are the main drivers of the region's expansion. Two major factors driving market expansion are the increasing prevalence of genetic diseases and the need for cutting-edge therapeutic solutions. Leading nations with big players like Novartis and Boehringer Ingelheim are the UK, France, and Germany.
Germany Unveils National Roadmap to Boost Gene and Cell Therapy Innovation
A roadmap for enhancing healthcare and bolstering Germany as a gene and cell therapy hub was created in June 2024 by about 150 experts from different stakeholder groups, including several scientists from the German Center for Infection Research (DZIF) network. The Berlin Institute of Health (BIH) at Charité was tasked by the German Federal Ministry of Education and Research (BMBF) to supervise and coordinate the strategy's development.
South America: Gene Vectors Fuel Biotech Expansion
South America is expected to grow significantly in the gene vector market during the forecast period. South America’s biotech sector is growing as healthcare systems integrate gene-based therapies. Governments fund clinical trials for rare diseases and cancer, while regional biotech hubs collaborate with global firms to advance vector manufacturing and strengthen therapeutic innovation pipelines.
Brazil: Biotechnology’s Powerhouse in the Making
Brazil’s pharmaceutical ecosystem is rapidly evolving, driven by ANVISA’s support for gene and cell therapy development. Local biotech firms expand viral-vector production, while national programs invest in advanced therapy research to boost healthcare self-sufficiency and regional export potential.
MEA: Advancing Genomic Medicine and Biotech Research
The Middle East and Africa are expected to grow at a lucrative CAGR in the gene vector market during 2025-2034. The Middle East and Africa are investing heavily in genomic medicine, with biotech startups focusing on vector-based therapies. Governments strengthen healthcare infrastructure, enable clinical trial networks, and foster collaborations with global pharma players to advance innovative treatment accessibility.
UAE: Precision Health Meets Biotech Innovation
The UAE is transforming into a biotech and healthcare innovation hub. National genome projects and research grants drive vector-based therapy studies, while pharma investments enhance local manufacturing capacity, clinical research facilities, and regulatory frameworks for cutting-edge biopharmaceutical growth.
Gene Vector Market Value Chain Analysis
R&D
Finding and confirming a target gene for a particular disease is the first stage of research and development. The gene is then modified to create a vector, usually a virus, that can deliver the gene to target cells safely and effectively. The vector is created in host cells and purified to a very pure bulk drug substance as part of upstream procedures.
Clinical Trials and Regulatory Approvals
Clinical trials use phased testing, starting with safety evaluation in small cohorts and progressing to large-scale efficacy studies, to assess the gene vector's safety and effectiveness in human subjects. Health agencies thoroughly examine all clinical data, manufacturing specifics, and safety profiles before granting regulatory approval.
Formulation and Final Dosage Preparation
Using excipients, formulation development stabilizes the purified vector to stop deterioration during transportation and storage. To guarantee consistency and sterility prior to patient administration, final dosage preparation entails sterile filtration, accurate fill-and-finish into containers, and rigorous quality control testing.
Company Landscape
Lonza Group AG
Company Overview: Lonza is a major global CDMO focused on biologics, cell & gene therapies, and viral vector manufacturing services.
Corporate Information (Headquarters, Year Founded, Ownership Type): Headquarters in Basel, Switzerland; founded in 1897; publicly listed company.
History and Background: Originally a chemicals business, Lonza over the decades shifted into life-sciences manufacturing and now supports advanced therapy development, including vector production.
Key Milestones / Timeline: In H1 2025, Lonza achieved CHF 3.6 billion sales with CER growth of 19% and core EBITDA margin at 29.6%. The CDMO business grew CER 23.1% with a margin of ~30.2%. In October 2025, the company reaffirmed full-year guidance and signed a significant long-term supply agreement for its Vacaville, U.S. site.
Business Overview: Provides end-to-end services including process development, plasmid DNA supply, viral vector manufacturing (AAV, lentivirus), and commercial support for gene therapy programs.
Business Segments / Divisions: Divided into three CDMO platforms: Integrated Biologics, Advanced Synthesis, and Specialized Modalities.
Geographic Presence: Global manufacturing and R&D presence across Europe, North America (including U.S. sites like Houston and Vacaville), and Asia-Pacific.
Key Offerings: Includes viral vector platforms (AAV, lentivirus, adenovirus), stable producer cell line development for AAV >1E12 vg/mL titers with >30% full capsid. Offers cGMP manufacturing at ~2,000 L scale.
End-Use Industries Served: Biopharma and biotechnology companies developing gene and cell therapies for oncology, rare diseases, and genetic disorders.
Key Developments and Strategic Initiatives:
Mergers & Acquisitions: Acquired U.S. manufacturing site in Vacaville to bolster U.S. footprint.
Partnerships & Collaborations: Teamed up with firms Excellos and Akadeum in August 2025 to improve the cell and gene-therapy manufacturing landscape.
Product Launches / Innovations: Developed a case study on a stable producer cell line for AAV vectors with significantly higher titers than transient methods.
Capacity Expansions / Investments: Announced new 100,000 sq ft viral/immunotherapy facility in Houston to more than double viral gene therapy capacity.
Regulatory Approvals: Supports clients with regulatory services for gene therapies; strong GMP readiness.
Distribution channel strategy: Operates a B2B CDMO model providing manufacturing services to biotech and pharma rather than direct commercial product sales.
Technological Capabilities / R&D Focus: Focus on scalable vector manufacturing, advanced analytics, stable cell lines, and robust process development.
Core Technologies / Patents: Proprietary cell-line platforms and vector production technologies; e.g., stable producer cell line for AAV.
Research & Development Infrastructure: Multiple development centers and manufacturing sites globally delivering from early-stage to commercial manufacturing readiness.
Competitive Positioning: Recognized as a leader among vector CDMOs with a strong global footprint, high utilization, and broad capabilities in gene-therapy manufacturing.
Strengths & Differentiators: Large-scale global operations, advanced vector platforms, strong contract pipeline, strategic U.S. manufacturing expansion.
Market Presence & Ecosystem Role: Plays a pivotal enabling role for gene-therapy developers by supplying scalable manufacturing, process development, and regulatory readiness.
SWOT Analysis:
Strengths: Global CDMO leadership in the gene-therapy space, advanced platforms, strong financial performance.
Weaknesses: High capital expenditure required for manufacturing expansion, reliance on external biotech/pharma clientele.
Opportunities: Growth in approved gene therapies, increased outsourcing of manufacturing in advanced therapies.
Threats: Manufacturing overcapacity risk, regulatory or supply-chain disruptions, intense competition among CDMOs.
Recent News and Updates:
July 2025: H1 results beat estimates; CDMO business margin ~30.2% and upgraded FY guidance.
October 2025: Confirmed full-year guidance and significant new long-term U.S. contract for the Vacaville site.
December 2024: Announced exit of Capsules & Health Ingredients business to focus fully on CDMO growth.
Press Releases: Announced strategic operating model “One Lonza” effective April 2025 to streamline into three platforms.
Thermo Fisher Scientific Inc.
Company Overview: Thermo Fisher is a global life-sciences tools and services company that also offers viral vector CDMO manufacturing and bioprocessing solutions for gene therapies.
Corporate Information (Headquarters, Year Founded, Ownership Type): Headquartered in Waltham, Massachusetts, USA; founded in 1956; publicly traded company.
History and Background: Started as an analytical instrumentation company, expanded significantly into life sciences, biologics, and cell & gene therapy manufacturing via acquisitions and internal growth.
Key Milestones / Timeline: In 2025, the company announced a U.S. manufacturing investment strategy and acquisition of Sanofi’s Ridgefield, New Jersey site to expand manufacturing capacity. In 2025, it also acknowledged the strategic expansion of its pharma-services capacity.
Business Overview: Operates in equipment, consumables, analytical instruments, and CDMO manufacturing services (including viral vectors) serving pharma, biotech, and research institutions.
Business Segments / Divisions: Segments include Life Sciences Solutions, Analytical Instruments, Specialty Diagnostics, Laboratory Products, and Biopharma Services (viral vector manufacturing).
Geographic Presence: Global presence with manufacturing and R&D sites across North America, Europe, and Asia-Pacific.
Key Offerings: Viral vector manufacturing systems (AAV, lentivirus, retrovirus, adenovirus), plasmid DNA supply, advanced purification/filtration technologies, single-use bioreactors, and CDMO services.
End-Use Industries Served: Pharmaceutical and biotechnology firms developing gene therapies, diagnostics labs, research organizations, and contract manufacturing.
Key Developments and Strategic Initiatives:
Mergers & Acquisitions: Announced acquisition of Sanofi’s Ridgefield site in 2025 to bolster U.S. manufacturing footprint.
Partnerships & Collaborations: Investment announced in April 2025 to enhance U.S. innovation and manufacturing support.
Product Launches / Innovations: Expanded gene-therapy portfolio, including AAV manufacturing media and advanced purification resins (2021).
Capacity Expansions / Investments: Plainville, Massachusetts, viral vector facility (~300,000 sq ft) opened in 2022, doubling capacity.
Distribution channel strategy: Supplies consumables and equipment globally, and offers CDMO manufacturing services via its pharma-services business.
Technological Capabilities / R&D Focus: Focus on scalable manufacturing, automation, purification, and integrated cell & gene therapy workflows.
Core Technologies / Patents: Proprietary purification, filtration, and bioprocessing systems enhanced via the acquisition of Novasep’s Henogen viral-vector unit (~€725 m) in 2021.
Research & Development Infrastructure: Multiple research and manufacturing centers globally dedicated to advanced therapy support.
Innovation Focus Areas: Automation, scalable vector production, single-use bioreactors, and cost reduction in gene-therapy manufacturing.
Competitive Positioning: Broadly diversified across life sciences with a strong presence in gene-therapy manufacturing solutions; provides both tools & services.
Strengths & Differentiators: Massive global scale, diversified portfolio beyond gene therapies, strong supply chain, and manufacturing infrastructure.
Market Presence & Ecosystem Role: Key supplier of manufacturing capacity and bioprocess tools to the gene-therapy ecosystem; enables end-to-end workflows.
SWOT Analysis:
Strengths: Large resource base, global infrastructure, diversified services.
Weaknesses: Some manufacturing compliance issues (see news) and operational adjustments such as layoffs.
Opportunities: Growing gene-therapy outsourcing, demand for scalable manufacturing solutions.
October 2024: Documents revealed FDA violations at the Greenville, U.S., plant related to drug manufacturing quality control.
July 2025: Announced acquisition of Sanofi’s Ridgefield facility to expand U.S. manufacturing capabilities and strengthen position in essential medicines production.
Press Releases:
April 24, 2025: Announced investment to enhance U.S. innovation and support customers’ manufacturing.
Top Vendors in the Gene Vector Market & Their Offerings
Company
Offerings
Contribution to Gene Vector Market
Focus Area
Merck KGaA (MilliporeSigma)
Provides viral vector manufacturing, plasmid DNA, and gene-editing tools.
Expands global viral vector capacity and invests in advanced therapy production platforms.
AAV, lentiviral manufacturing, and process optimization.
Catalent
Offers end-to-end viral vector development and GMP manufacturing.
Enhances capacity through facility expansions and automation to support gene therapy demand.
Cell and gene therapy CDMO services.
WuXi AppTec
Provides viral vector CDMO, plasmid DNA, and analytical testing.
Expands global footprint and accelerates time-to-market for gene therapies.
Integrated vector development and manufacturing.
Samsung Biologics
Develops scalable viral vector production platforms.
Invests in biomanufacturing infrastructure and global partnerships.
Advanced therapies and bioprocess optimization.
Charles River Laboratories
Offers viral vector testing, safety, and development support.
Strengthens supply chain through end-to-end preclinical and manufacturing services.
Analytical and biosafety solutions for gene therapies.
In October 2025, in order to overcome the drawbacks of conventional transient transfection-based production and bring AAV manufacturing standards closer to those set for antibody-based biologics, Asimov introduced its AAV Edge Stable Producer system.
In February 2025, Fuse Vectors, a biotech startup based in Copenhagen, announced €4.9 million in pre-Seed funding to advance the development of gene therapy using its cell-free viral vector technology.
Segments Covered in the Report
By Type
Viral Vectors
AAV (Adeno-associated virus)
Lentiviral vectors
Adenoviral vectors
Retroviral vectors
Other viral (HSV, vaccinia, etc.)
Non-Viral Vectors & Delivery
mRNA / LNP (lipid nanoparticle) delivery
Plasmid DNA
Oligonucleotide / naked DNA delivery
Nanoparticles / polymeric / peptide carriers
Services, Reagents & Platform Support
GMP CDMO / large-scale manufacturing services
Reagents, kits & raw materials (plasmids, capsids, enzymes)
CROs, Clinical Labs & Translational Service Providers
Vaccines & Preventive Health Manufacturers
Agriculture / Veterinary / Other Industrial Uses
By Region
North America
U.S.
Canada
Mexico
Rest of North America
South America
Brazil
Argentina
Rest of South America
Europe
Western Europe
Germany
Italy
France
Netherlands
Spain
Portugal
Belgium
Ireland
UK
Iceland
Switzerland
Poland
Rest of Western Europe
Eastern Europe
Austria
Russia & Belarus
Türkiye
Albania
Rest of Eastern Europe
Asia Pacific
China
Taiwan
India
Japan
Australia and New Zealand
ASEAN Countries (Singapore, Malaysia)
South Korea
Rest of APAC
MEA
GCC Countries
Saudi Arabia
United Arab Emirates (UAE)
Qatar
Kuwait
Oman
Bahrain
South Africa
Egypt
Rest of MEA
FAQ
Finding : The gene vector market in 2026 is valued at USD 11.64 billion and is projected to climb to USD 64.38 billion by 2035, with a CAGR of 21%.
Finding : North America is currently leading the gene vector market share by 42% due to a strong presence of the biotechnology industry.
Finding : The gene vector market comprises five segments type, application, form, end-user industry, and region.
Meet the Team
Shivani Zoting
Principal Consultant
Shivani Zoting is a dedicated research analyst specializing in the healthcare industry. With a strong academic foundation, a B.Sc. in Biotechnology and an MBA in Pharmabiotechnology, she brings a unique blend of scientific understanding and strategy.
Aditi Shivarkar is a seasoned professional with over 14 years
of experience in healthcare market research. As a content
reviewer, Aditi ensures the quality and accuracy of all market
insights and data presented by the research team.
We use cookies that are necessary to make our site work. We may also use additional cookies to analyze,
improve, and personalize our content and your digital experience.
You can manage your cookie preferences using the
Privacy Policy
For more information, see our
Terms and Conditions
.
Cookie Preference Center
We use cookies which are necessary to make our site work.
We may also use additional cookies to analyze, improve and personalize
our content and your digital experience.
For more information, please read our
Cookie Policy
.
You may choose not to allow some types of cookies.
Blocking some cookies may impact your experience of the site.